


Earnings jump puts BorgWarner in focus
BorgWarner (BWA) moved into the spotlight after its third quarter update, where net income and earnings per share rose compared with last year, even though reported sales were slightly lower.
BorgWarner’s recent earnings update landed after a choppy period for the share price, with a 30-day share price return of down 8.4% and a 90-day move of down 13.2%. Even though the year-to-date share price return sits near 20% and the 1-year total shareholder return is about 32%, this suggests that longer term holders have still seen gains, while shorter term momentum has cooled as investors reassess growth prospects and risk around the current US$55.93 level.
Compare BorgWarner's earnings-driven story with other auto and industrial plays by reviewing a hand picked list of 26 high quality undervalued stocks that also pair solid cash flows with sturdier balance sheets.
Bulls point to BorgWarner’s higher earnings and long term returns, while bears focus on the recent share pullback and softer sales. As you weigh the numbers, which side does the current valuation appear to favor?
Most Popular Narrative: 31% Undervalued
On the most followed narrative, BorgWarner’s fair value sits at $81.53 against the recent $55.93 share price. This frames the current debate around whether the market is underestimating its future cash generation and capital return plans.
Expansion into data center power through the turbine generator program, supported by a 2 GW plant in North Carolina and expected revenue of about US$300 million in 2027 at mid teens incremental margins, adds a new earnings stream that is not fully tied to light vehicle cycles and could support operating margin and EPS resilience.
See why 24 investors see BorgWarner as 31% undervalued.
Result: Fair Value of $81.53 (UNDERVALUED)
Still, that story frays if BorgWarner’s combustion heavy portfolio loses volume faster than expected, or if the battery unit’s drag on sales and margins lingers longer.
Find out about the key risks to this BorgWarner narrative.
Another View on BorgWarner’s Valuation
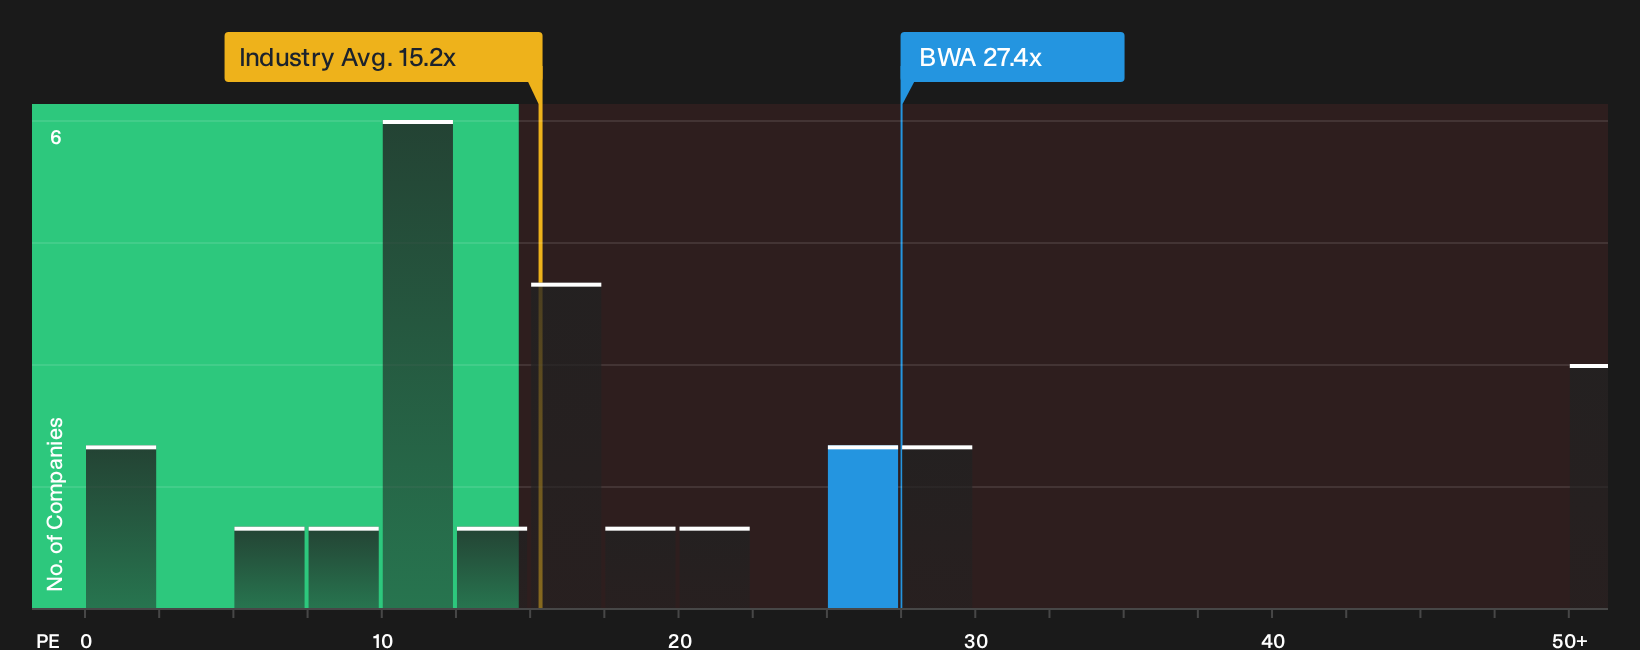
While BorgWarner looks cheap against an $81.53 fair value narrative, the current P/E of 27.4x tells a different story. It sits well above the US Auto Components industry at 15.7x, peers at 13.5x and even its own fair ratio of 17.2x. Is that a margin of safety or a valuation air pocket?
Before you lean on this earnings multiple too heavily, it helps to see how the underlying numbers stack up in a fuller valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BorgWarner’s outlook can leave the story feeling indecisive. Move quickly, test the data for yourself, and weigh both sides with 4 key rewards and 2 important warning signs
Looking for more BorgWarner-sized investment ideas?
If you stop with BorgWarner, you risk missing other opportunities. Broaden your watchlist now with a few focused stock ideas pulled from different angles.
- Zero in on potential mispricings by scanning a curated pool of 26 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- Build a sturdier portfolio core by focusing on companies filtered through a list of solid balance sheet and fundamentals (24 results) for financial resilience.
- Get in early on lesser-known opportunities by reviewing a 19 high quality undiscovered gems that already show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com