


- Proto Labs is set to report earnings after previously reporting US$149.3 million in quarterly revenue, which was 10.6% higher year on year and ahead of analyst expectations.
- The upcoming release has drawn attention because analysts expect around 10.1% year on year revenue growth and EPS guidance above consensus, with focus on Proto Labs' execution in digital manufacturing services.
- We will now look at how Proto Labs' investment narrative could be affected by the upcoming earnings report and revenue expectations.
Proto Labs Investment Narrative Recap
To hold Proto Labs, you need to believe its digital manufacturing platform can keep attracting higher requirement work in CNC machining and injection molding, while 3D printing and Europe do not turn into lasting drags. The near term catalyst is clear. This week’s earnings will show whether the recent revenue trend and margin improvements are holding up.
The biggest operational risk right now sits in Europe and in any further softness in 3D printing. If the upcoming quarter shows only modest change in these areas, the impact on the broader Proto Labs investment case is limited, even if near term sentiment moves around the print.
Recent commentary around Proto Labs has highlighted restructuring in its European operations, including consolidation of legal entities and ERPs and a sharper focus on core industries. That program matters directly to the current earnings setup because Europe has shifted recently from revenue decline to growth in constant currency but remains a key swing factor for profitability.
If this week’s results show that European changes are gaining traction, investors get more confidence that a former drag could become a contributor over time. If progress looks patchy, the market may question how quickly the business can translate its digital manufacturing strengths into more consistent regional margins and reduce dependence on stronger US performance.
Proto Labs Earnings Assumptions In Focus
Expectations around Proto Labs now lean heavily on a clear set of analyst assumptions that tie earnings, margins and valuation together. The consensus view anchors on earnings today of about US$30.5 million and a path to US$74.0 million of profit by 2029, with revenue growth modeled at 7.9% a year over the next three years and profit margins rising from 5.4% to 10.5% across the same period. That earnings bridge implies roughly a 2.4x increase from the current profit base. This sets a high bar for execution as the business works through its mix shift and European restructuring.
Proto Labs' narrative projects US$704.5 million revenue and US$74.0 million earnings by 2029. This requires 7.9% yearly revenue growth and roughly a 2.4x earnings increase from US$30.5 million today.
Analysts tie these profit and growth assumptions directly into their valuation work on Proto Labs. To match the current consensus view, the stock would need to support a P/E of 42.9x on those 2029 earnings, compared with 67.2x cited around mid 2026 and a sector reference point of 24.8x for US machinery peers. That implies the market would still treat the business as higher quality than the broader group, just not at the multiple previously ascribed, if the forecast revenue and earnings path plays out as modeled.
The fair value framework being used also builds in a discount rate of 8.28% to 8.3% and modest share count growth of about 1.03% per year. Taken together, these inputs underpin a consensus price target of US$101.25 per share, framed against a recent quote around US$85.61 and a spread of US$91.00 to US$110.00 across individual analyst targets. For readers, the key question is whether the projected 7.9% annual revenue climb, margin improvement, and roughly 2.4x earnings step up feel realistic given Proto Labs' exposure to CNC machining, injection molding, 3D printing, and the ongoing clean up in Europe.
Uncover how Proto Labs' fair value indicates an 11% potential upside to its current price before the market closes.
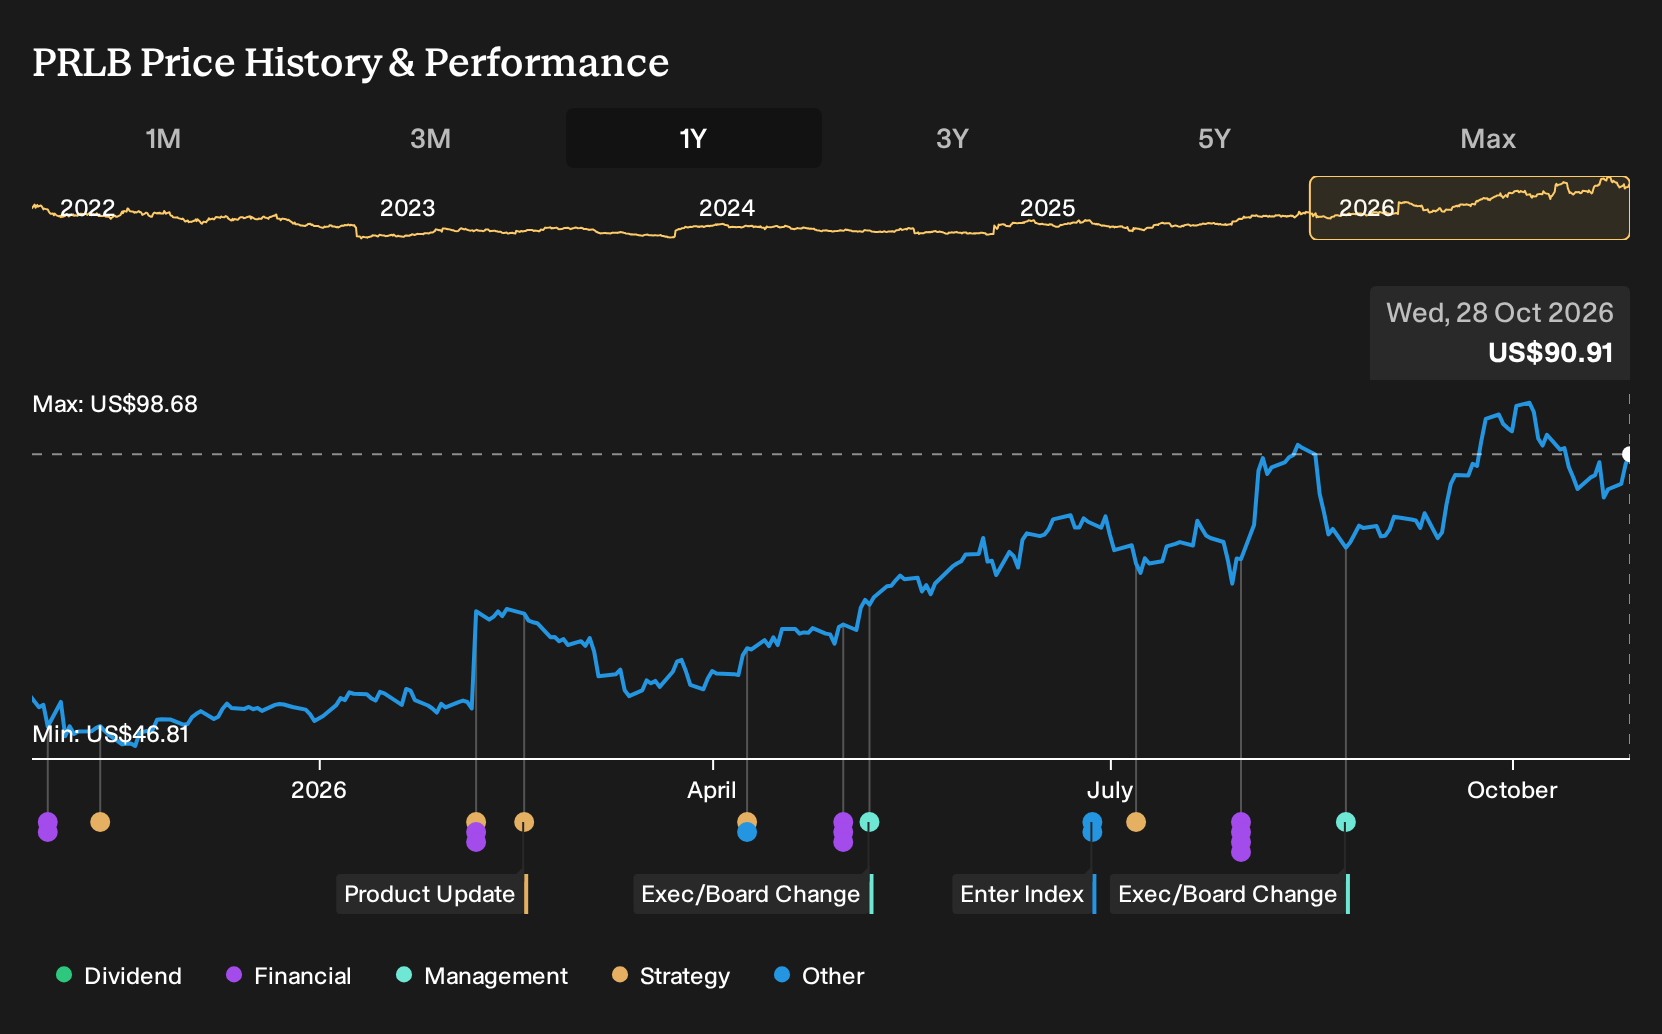
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$90.48 and US$110, with one end flagging Proto Labs as closer to the lower bound and another near the top of that band. Those views sit alongside real risks in Europe and 3D printing, so you are weighing upbeat expectations against execution pressure.
Explore 2 other Proto Labs fair value estimates, including one that suggests it could be worth just $90.48.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Proto Labs research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Proto Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Proto Labs' overall financial health at a glance.
Looking For More Ideas Beyond Proto Labs?
If Proto Labs has sharpened your focus on quality and execution, it can help to line it up against other potential opportunities that share some of the traits you care about most. The Simply Wall St Screener lets you quickly compare different sets of companies through a few focused lenses.
- If you want resilience first and foremost, filter for companies with steadier profiles by reviewing a set of 32 resilient stocks with low risk scores that may better match a cautious approach.
- If balance sheet strength matters most to you, use the tool to surface a list of solid balance sheet and fundamentals (24 results) that combines financial stability with room for a long term thesis.
- If you are hunting for value where others might not be looking yet, widen your research with a 19 high quality undiscovered gems that could complement or contrast with the Proto Labs story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com