


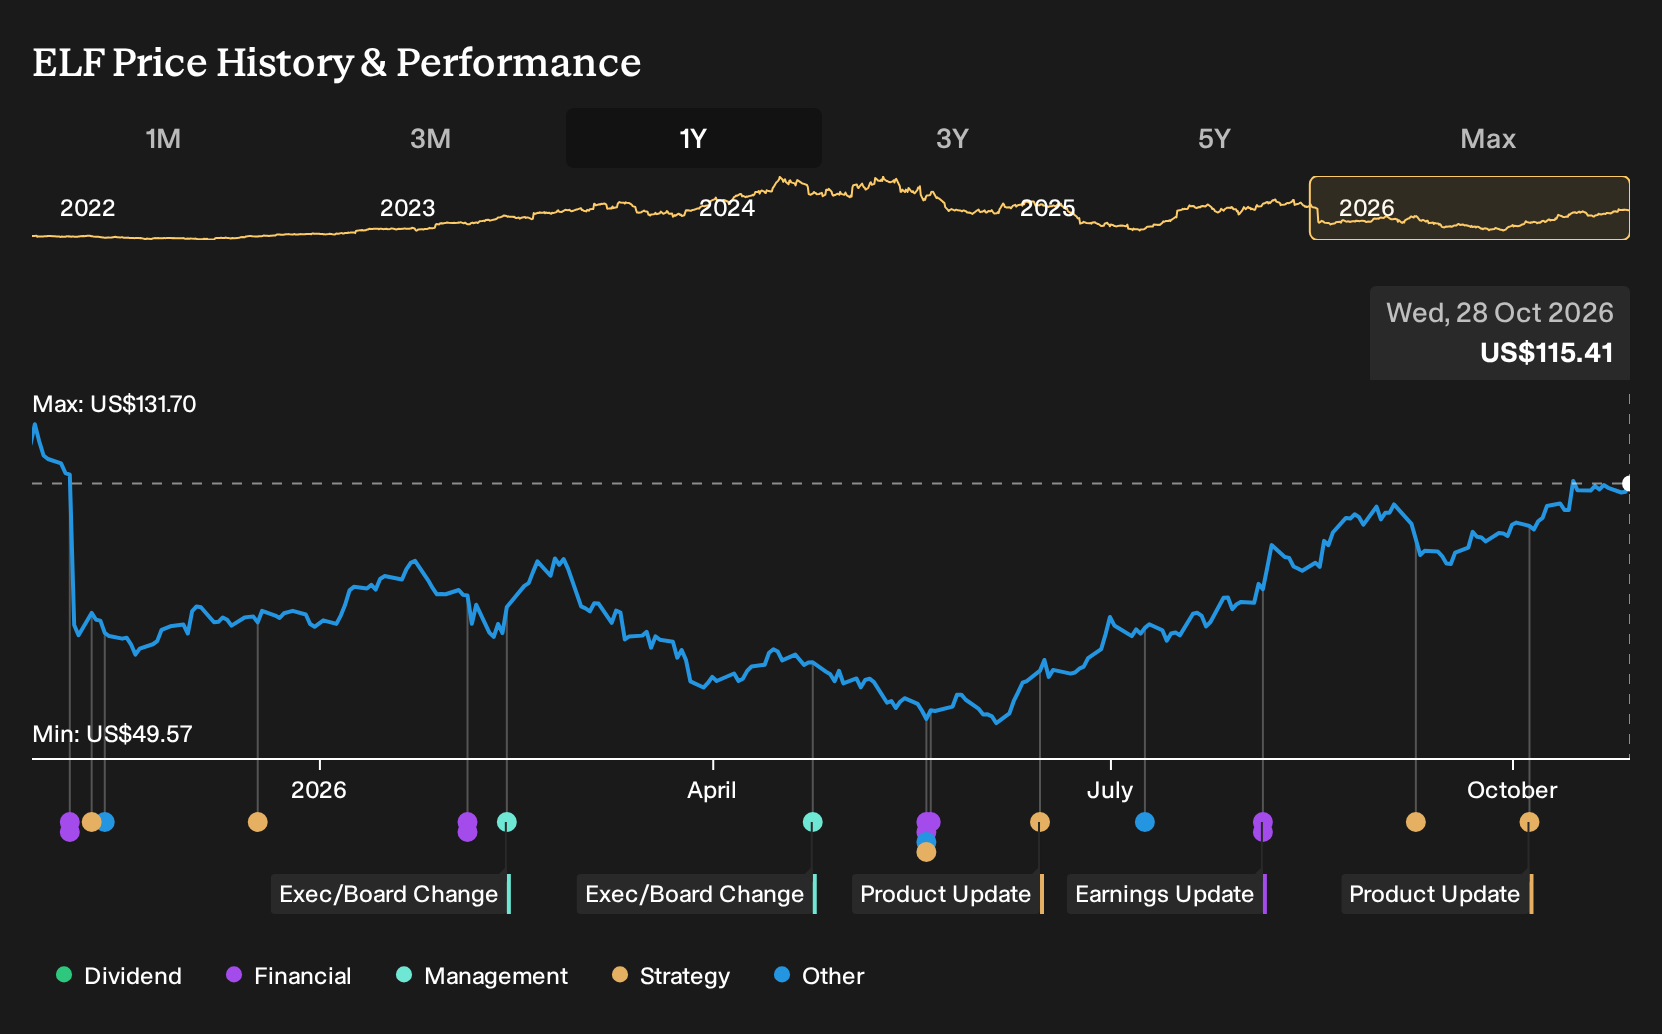
- e.l.f. Beauty is set to report September 2026 quarter results on 4 November, with earnings expected to decline year over year despite higher revenue.
- The mix of rising sales, pressure on quarterly profitability, and shifting analyst estimates highlights execution and cost discipline as key near term questions.
- We will now explore how e.l.f. Beauty's earnings uncertainty and expected profit pressure could influence the broader investment narrative.
e.l.f. Beauty Investment Narrative Recap
To own e.l.f. Beauty, you need to believe the company can keep turning heavy marketing, new product launches, and international rollouts into solid, profitable growth without letting costs run away. Earnings for the September 2026 quarter are expected to soften even as sales rise, which puts near term focus squarely on operating efficiency.
The main short term catalyst is whether management can show that elevated SG&A and marketing at 23% to 25% of net sales are starting to translate into better unit economics. The biggest immediate risk is that this spend, along with tariff related price cuts, compresses margins further without enough volume or mix benefit.
The Naturium acquisition offers useful context for this earnings setup. It signals e.l.f. Beauty’s push to broaden beyond the core cosmetics line into skin care, alongside brands like e.l.f. SKIN and rhode, and gives the group more levers across categories and channels when marketing dollars are this high.
For you, the question is whether Naturium and the wider multi brand portfolio ease some of the concentration risk around rhode and help diversify profit drivers if one label slows. Execution around integrating Naturium, supporting it with already heavy marketing budgets, and maintaining margin discipline sits close to the heart of the current catalyst and risk balance.
e.l.f. Beauty Forecasts And Implied Earnings Path
Analyst models for e.l.f. Beauty rest on a few clear numerical pillars that you can review for yourself. The projections assume revenue expands by 10.7% per year over the next three years while profit margins rise from 3.4% today to 8.0% by around 2029. Consensus earnings are expected to reach US$191.4 million by that year, compared with earnings today of US$59.6 million. This implies an increase of about US$131.8 million in annual profit. To match those income projections, forecasts point to revenue of US$2.4b in 2029 and a P/E of 40.7x on those future earnings, with analysts using a 7.8% to 7.82% discount rate in their valuation work.
e.l.f. Beauty's narrative projects revenue of US$2.4b and earnings of US$191.4 million by 2029. This rests on forecast yearly revenue growth of 10.7% and an earnings increase of about US$131.8 million from current earnings of US$59.6 million.
Uncover why e.l.f. Beauty's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster between about US$107.58 and US$137, with one estimate anchoring the high end. That spread already shows how far opinions can stretch. When you factor in the upcoming 4 November earnings risk around heavy marketing spend and rhode reliance, you have plenty of reasons to compare multiple viewpoints before acting on e.l.f. Beauty.
Explore 3 other e.l.f. Beauty fair value estimates, including one that suggests as much as 7% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your e.l.f. Beauty research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for e.l.f. Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate e.l.f. Beauty's overall financial health at a glance.
Looking For More Ideas Beyond e.l.f. Beauty?
Once you have formed a view on e.l.f. Beauty, it can help to compare that thesis with other companies that have different balance sheets, risk profiles, or payout policies. The Simply Wall St Screener is a quick way to line up those alternatives side by side and see how they stack up on the factors you care about most.
- If you care most about quality at a reasonable price, scan a curated pool of companies that combine fundamentals and value through our 26 high quality undervalued stocks.
- If capital preservation sits near the top of your checklist, narrow the field to businesses that appear more resilient on our risk scoring by checking the 32 resilient stocks with low risk scores.
- If you prefer income to price swings, focus your search on stocks that currently offer higher yields using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com