


The DoorDash move to buy Instacart has turned online delivery into a live test of who really controls the digital checkout. When one US$17b deal pulls restaurant orders and grocery baskets under a single roof, every logistics and marketplace stock tied to that flow of goods suddenly matters more. This piece unpacks how that shock can influence sentiment and reveals three stocks directly exposed to the news.
The stocks in this article are a small sample of what that DoorDash and Instacart shock touches, and the full screen surfaced 37 more mid to large cap logistics and marketplace infrastructure companies with equally compelling stories that are not covered below. To identify and analyze higher conviction ideas built around this supply chain and payments theme, go straight to the Digital Commerce Logistics & Marketplace Infrastructure screener.
Toast (TOST)
Toast plugs directly into the Digital Commerce Logistics & Marketplace Infrastructure theme by giving restaurants the software, payments rails, and online ordering tools that connect kitchens to delivery apps and digital checkouts.
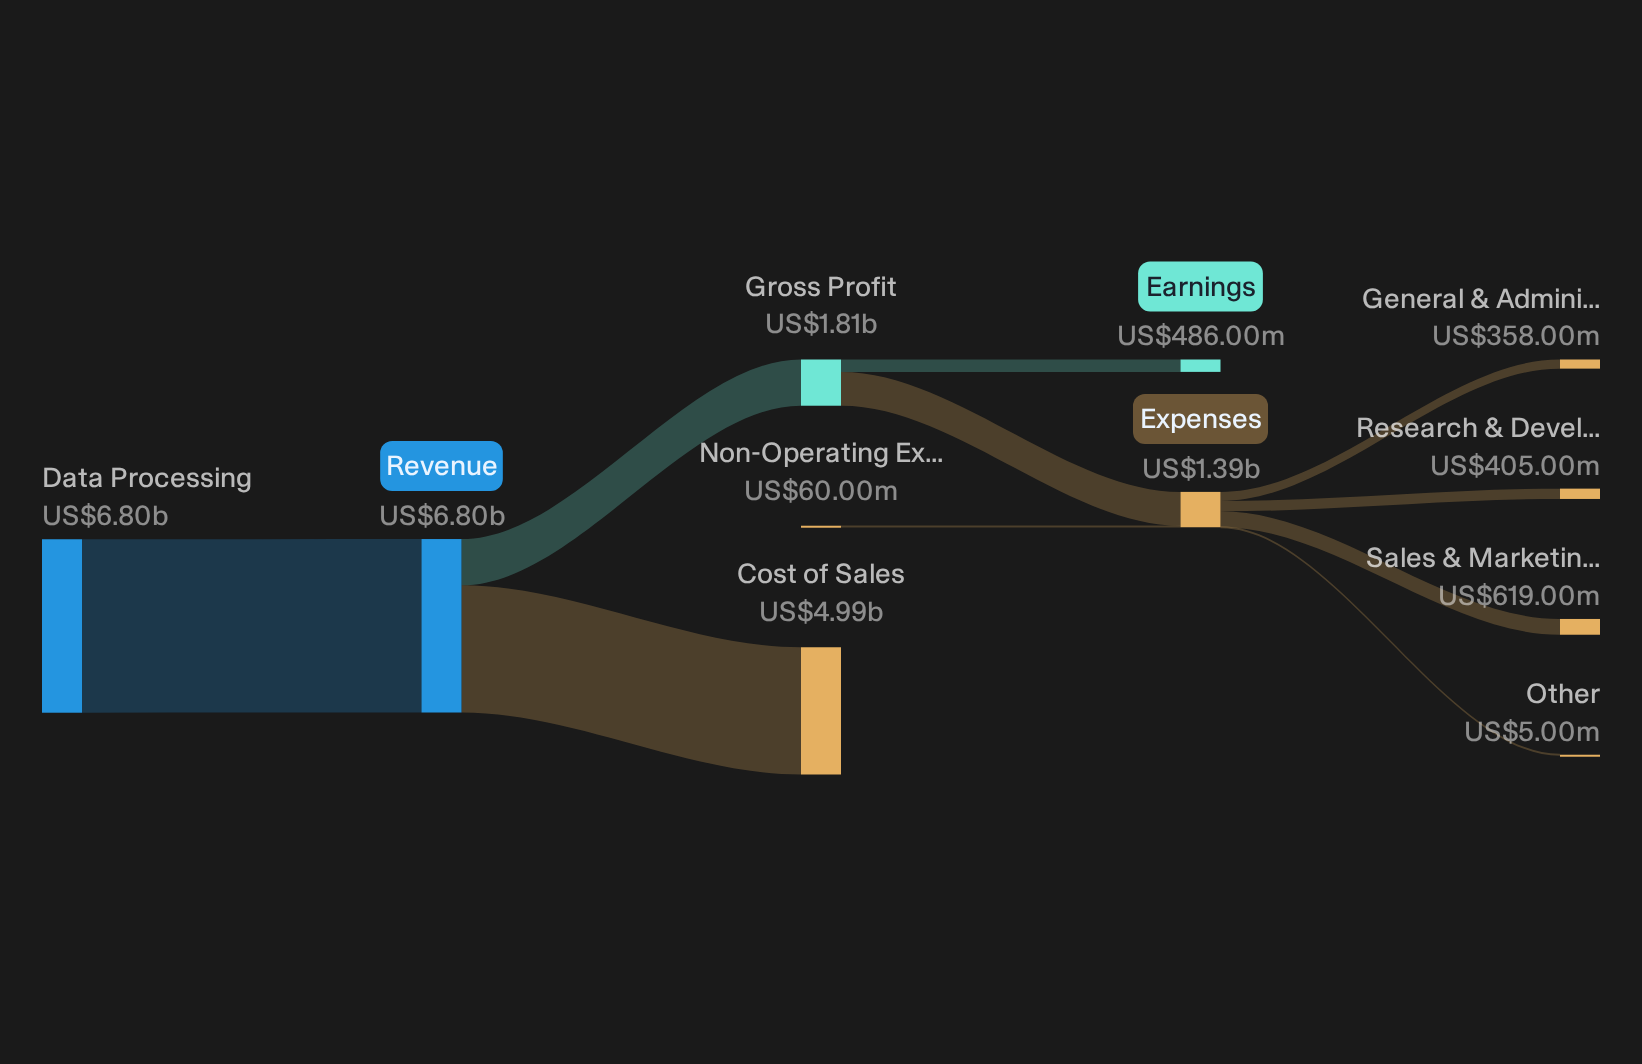
Toast runs a cloud platform that helps restaurants manage point of sale, kitchen operations, online ordering, delivery links, payroll, and payments. The group reports all revenue under data processing, which generated about US$6.8b, and the business carries a market value near US$18.4b.
Toast IQ and Toast IQ Grow are being used as the base for an agentic platform that can take over ongoing workflows such as marketing, scheduling, bookkeeping and payroll. This can shift Toast from mainly software fees to higher value service revenue streams and support higher recurring gross profit over time.
What happens to Toast’s earnings power if one less visible cost pressure breaks in its favor?
If that pressure eases, read the full narrative for Toast to see how Toast’s model could accelerate, what might cap that momentum, and which risks really matter.
Pattern Group (PTRN)
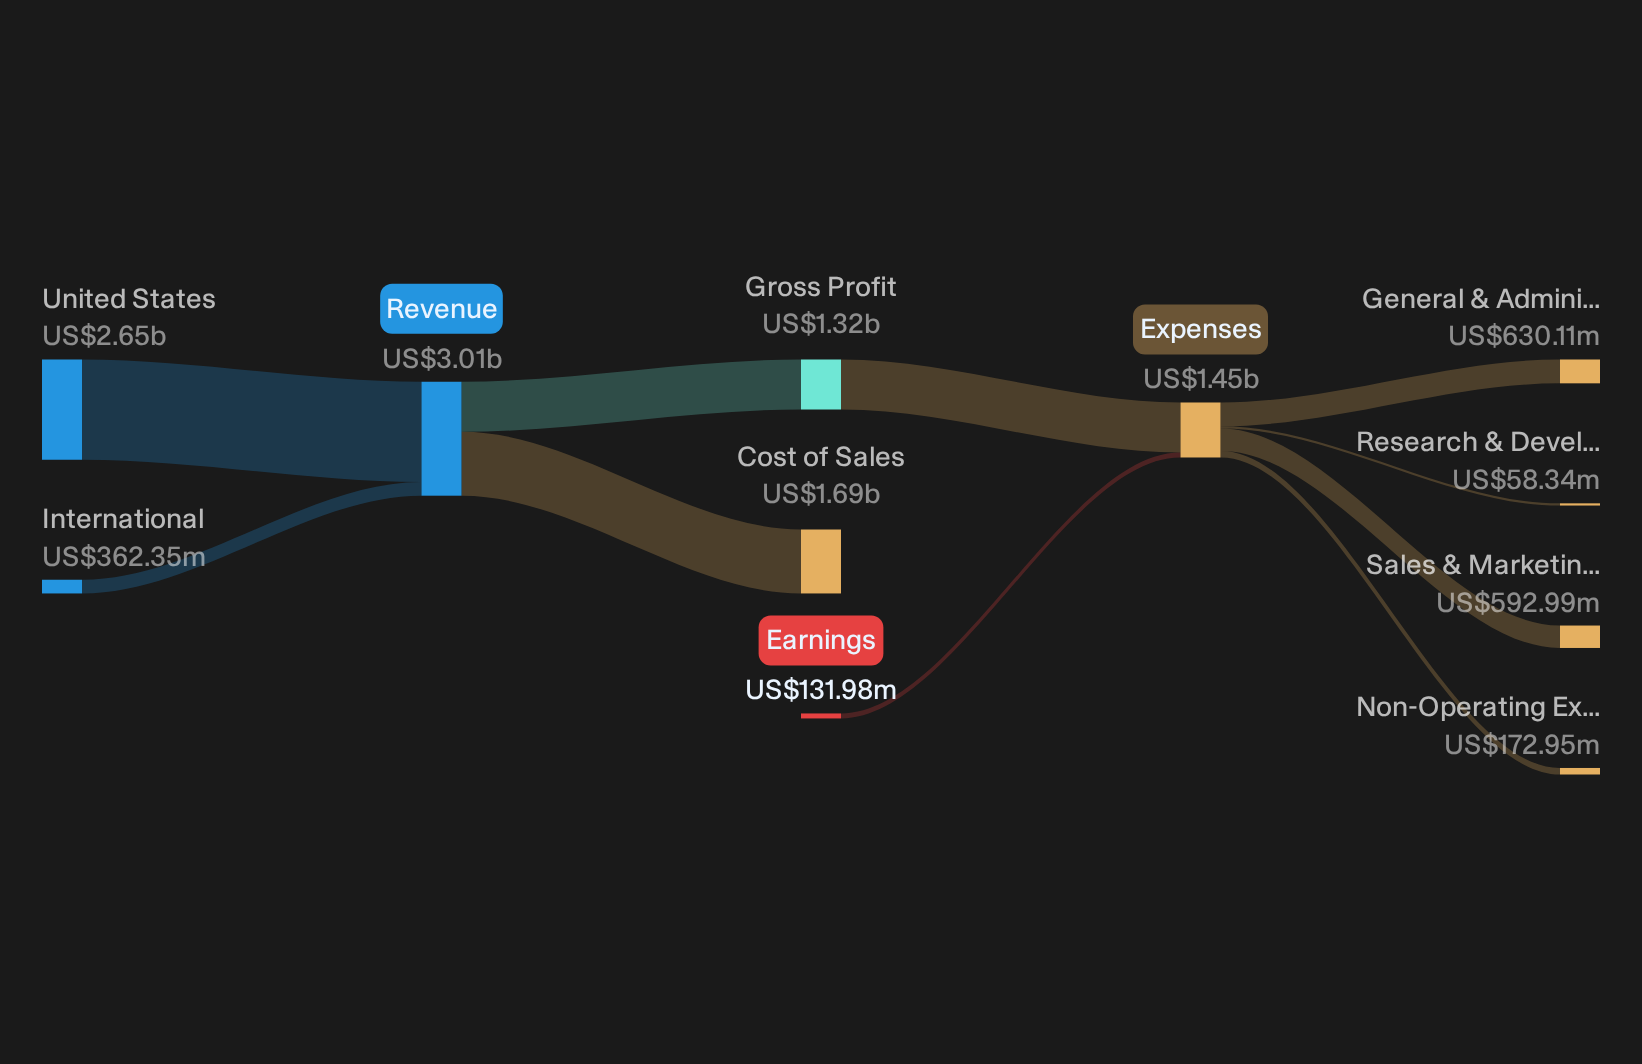
Pattern Group plugs into the Digital Commerce Logistics & Marketplace Infrastructure theme by running an e-commerce accelerator that buys stock from brands and uses its own tools to sell across online marketplaces, with about US$3.0b from online retailers and a roughly US$3.0b market cap.
Pattern Group matters in this theme because it sits where marketplace algorithms, logistics promises, and brand budgets all collide, and its heavy use of AI to manage that complexity is exactly where the DoorDash and Instacart shock pushes more attention.
Reliance on AI-native optimization across traffic, conversion, price and availability means any slowdown in AI model gains or higher AI token and R&D costs could outpace the benefit to brand partners.
For Pattern Group, a single shift in how those AI driven costs or performance trends land could be the difference between rising margins and a squeeze.
If that margin swing is what you care about, read the full narrative for Pattern Group to see how Pattern Group could turn AI spend into accelerating operating leverage.
Vertex (VERX)
Vertex plugs into the Digital Commerce Logistics & Marketplace Infrastructure theme by handling complex indirect tax and e-invoicing for retailers and wholesalers, generating about US$787 million from software and programming, with a roughly US$2.4b market cap that anchors it firmly in mid-cap territory.
Vertex matters because every extra order flowing through large marketplaces needs accurate, compliant tax handling in the background, and this business is built for that heavier traffic.
Regulatory mandates for real-time e-invoicing in large European economies, including the September 2026 French requirement and the January 2027 German requirement, are expected to direct more invoice volume onto Vertex e-invoicing platforms, which could add to subscription revenue and transaction driven revenue.
The real swing factor is how one less visible shift in customer adoption shapes the blend of high-margin recurring income over the next few years.
That shift in mix is exactly what matters now, and the full narrative for Vertex breaks down how Vertex revenue quality could accelerate or stall as adoption patterns change.

Seeking Alternatives Before The Crowd?
Fresh themes move first. Breakout stories gain momentum while screens are still quiet and headlines have not caught them yet. Use these curated shortlists before the crowd and consider acting promptly.
- Spot cash generators with room to move by reviewing a curated 26 high quality undervalued stocks that balances strong fundamentals with prices that still look reasonable.
- Track capital moving into automation by scanning 93 robotics and automation stocks built around businesses wiring machines, warehouses, and factories for the next productivity jump.
- Follow the grid upgrade story by checking 43 power grid technology and infrastructure stocks focused on companies supplying hardware and software that keep electricity flowing as demand shifts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com