


Key Points
Shares of MP Materials have fallen hard so far in 2026.
The mining company's future output is backed by the Pentagon.
But that security comes at a cost, and the stock still trades at a premium.
Rare-earth materials miner MP Materials (NYSE: MP) has been through the wringer. Once paraded as America's best hope of breaking China's stronghold on rare-earth materials, MP Materials became something of a Wall Street darling. That enthusiasm has cooled considerably, and MP now trades more than 60% lower than last year's high of about $100.
Now at around $38 a share, is MP worth buying? To get at that question, let's take a closer look at the agreement that helped MP reach its recent highs.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
MP's Pentagon partnership comes with a catch
MP's biggest tailwind has been the trade tension between China and the U.S. If these superpowers were on friendly terms, the trade of rare-earth materials between them -- or rather from China to the U.S. -- might not be so uncomfortable. But that is not the case, and the U.S. has been very anxious to break dependence on rare-earth materials and magnets from its economic rival.
That narrative explains, in part, why the Department of Defense purchased $400 million in MP stock last July. That massive investment in MP was also a major catalyst for MP stock, which had been trading in the $20s and $30s before the announcement. Shares surged almost 50% on the news, eventually surpassing $70 in August 2025.
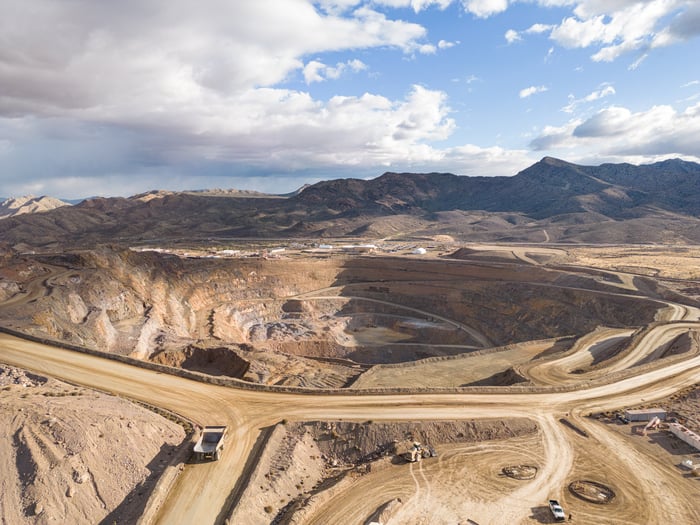
Image source: MP Materials.
As part of the partnership, the Pentagon has also agreed to purchase the magnets produced at MP's second factory, called 10X, while also guaranteeing that the facility will make at least $140 million in annual earnings before interest, taxes, depreciation, and amortization (EBITDA) once it reaches full production (about 7,000 metric tons of magnets annually).
It's important to be specific here: The Pentagon guarantees that MP has a buyer, but it doesn't have to be the final buyer. If, for example, another customer wants to buy those magnets for a higher price, the Pentagon could allow the transaction.
But here's the catch: MP has agreed to give the Pentagon the first $30 million above the $140 million EBITDA floor, plus 50% of the profits above $170 million EBITDA. So, using the $140 million EBITDA floor, if 10X generates $250 million in annual EBITDA, MP keeps $180 million, while the government gets $70 million.
Economic security for MP, in other words, could come at a cost. Of course, having a guaranteed buyer is also pretty attractive, especially with MP investing $1.25 billion in 10X. But the profit-sharing also limits how much MP could make from 10X's sales. And that's something worth considering when deciding how much to pay for MP stock.
Should you buy MP Materials?
MP is a promising mining company with government backing and an operating mine. Still, I'm not so sure every investor should invest in this stock.
The thing is, even after its spectacular fall, MP Materials carries a substantial valuation (about $6 billion) for a mining company that is not consistently profitable. Indeed, the stock trades for more than 16 times its trailing annual revenue of $416 million, which is higher than fellow rare-earth materials miner Lynas Rare Earth (about 11.5) and copper miner Freeport-McMoRan (about 3.75).

Data by YCharts
That's quite steep for a company whose biggest growth opportunity is likely still a few years away. At most, then, I would recommend MP as a growth stock to investors who can afford to lose money, and even then only a small speculative position.
Steven Porrello has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends MP Materials. The Motley Fool has a disclosure policy.