


Rush Street Interactive (RSI) put fresh numbers on the table after its third quarter, with stronger earnings, higher net income, and reaffirmed full-year revenue and EBITDA guidance catching investors’ attention.
Despite the upbeat Q3 earnings and reiterated guidance, Rush Street Interactive’s recent trading tells a different story, with the share price down 22.6% over the past month and 43.5% over 90 days, even after a very strong 3-year total shareholder return of about 3.3x. This pattern hints at earlier enthusiasm now cooling as investors reassess growth and risk.
Capitalize on the reset in Rush Street Interactive sentiment and compare it with hand-picked online gambling peers and consumer services stocks in the 26 high quality undervalued stocks.Rush Street Interactive now trades at a sharp discount to both analyst targets and intrinsic value estimates after that pullback. Does this represent an overreaction to near-term caution, or a reset that better reflects the risk?
Most Popular Narrative: 55% Undervalued
Against a last close of $15.13, the prevailing narrative assigns Rush Street Interactive a fair value of about $33.85, which frames the recent pullback as a sizeable gap between price and modelled worth.
The digitalization of entertainment is accelerating migration from offline to online gaming. With record-high monthly active users (MAUs) growing over 30% in North America and over 40% in Latin America, Rush Street Interactive is described as being well-positioned to capture this expanding addressable market, supporting sustained future revenue growth.
See why 22 investors see Rush Street Interactive as 55% undervalued.
Result: Fair Value of $33.85 (UNDERVALUED)
Still, Rush Street Interactive’s reliance on Latin American expansion and the potential for higher gaming taxes in key jurisdictions could challenge the bullish valuation narrative.
Find out about the key risks to this Rush Street Interactive narrative.
Another View On Rush Street Interactive’s Valuation
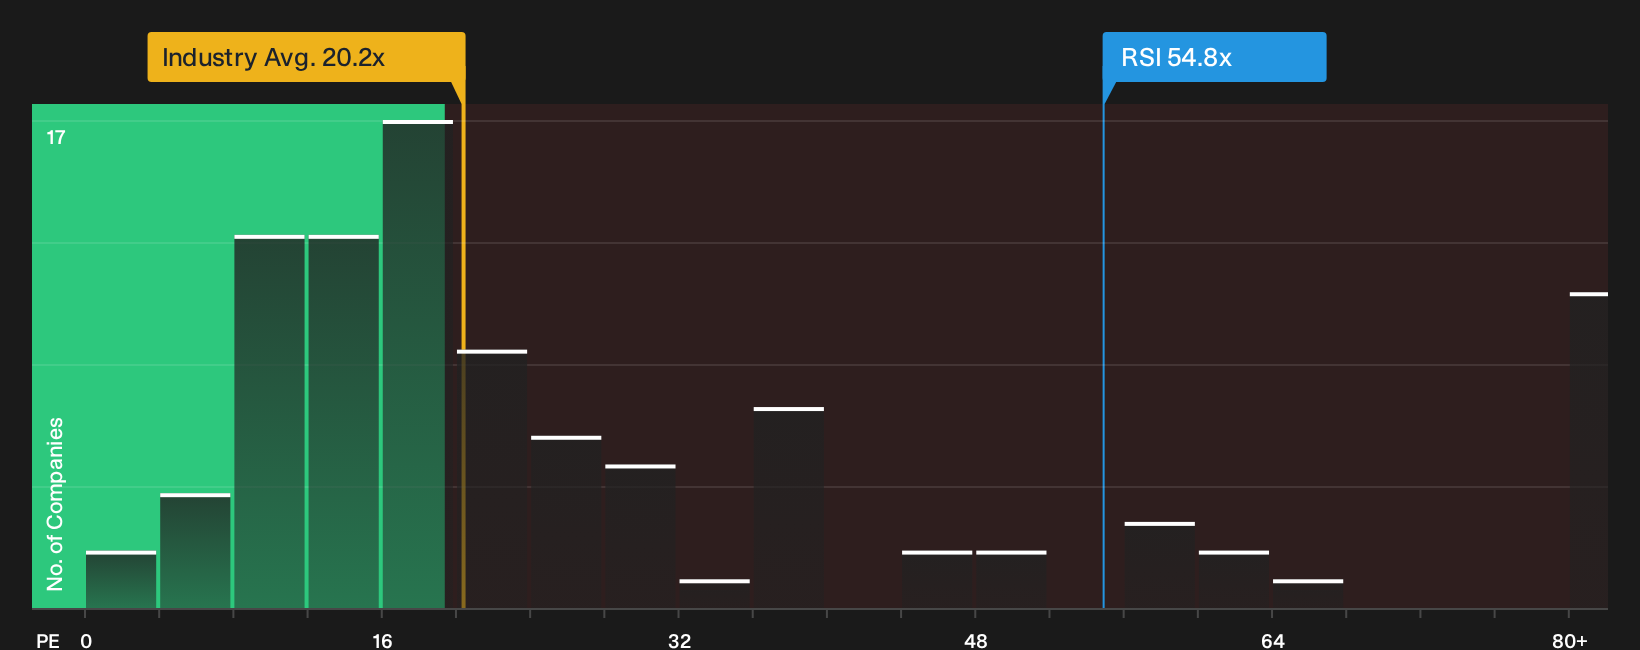
On one hand, Rush Street Interactive screens as undervalued, trading about 57.7% below an estimated fair value and below an assessed future cash flow value of $35.74 per share. On the other, the stock changes hands at a P/E of 54.8x, which is much richer than the US Hospitality industry average of 20.3x and above a fair ratio of 32.5x. That gap can signal either a mispriced opportunity or a lot of expectations already built into the earnings multiple. Which side of the story do you lean toward as an investor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Rush Street Interactive is clearly split, which creates a window for you to check the underlying data and decide where you stand. To see what optimists are focusing on, review the 3 key rewards.
Looking for more Rush Street Interactive investment ideas?
If Rush Street Interactive has you rethinking where to put fresh capital, broaden your watchlist now so you are not relying on a single story.
- Target potential upside in smaller companies that still clear basic quality hurdles by scanning the 9 elite penny stocks with strong financials.
- Zero in on opportunities where quality and price already line up, using the 19 high quality undiscovered gems before other investors catch on.
- Lock in ideas that prioritize resilience and capital protection first by running through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com