


NewMarket (NEU) is back in focus after releasing third quarter and year-to-date results on 28 October 2026, reporting higher sales, net income and earnings per share for both periods.
The latest earnings release lands after a stretch where NewMarket’s 1 month share price return has slipped 4.3%, even though the stock is still up 27.0% year to date and supported by a 5 year total shareholder return of 185.7%.
Scan how NewMarket’s latest earnings compare to other specialty chemicals players by reviewing the 26 high quality undervalued stocks that combine solid cash generation with balance sheets built to handle pressure.
Bulls point to NewMarket’s higher earnings and long term shareholder returns. Bears highlight the recent pullback and rich past run. Which story do the current valuation markers actually support?
Price-to-Earnings of 18.6x: Is it justified?
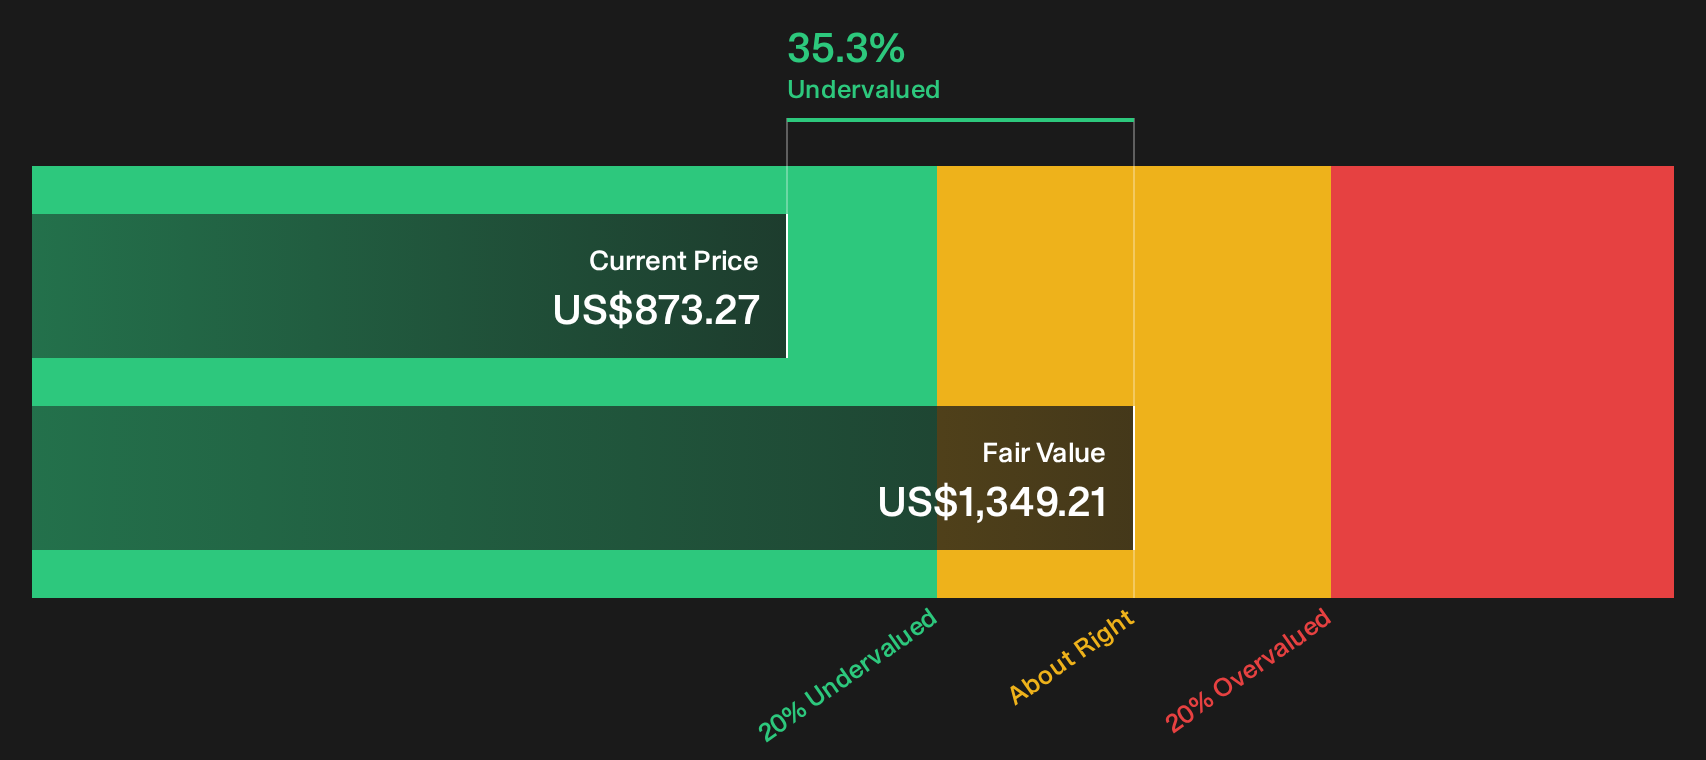
NewMarket currently changes hands at $873.27, and the SWS DCF model estimates a future cash flow value of $1,349.21, which implies the stock is trading 35.3% below that fair value mark. Alongside that, the preferred marker in the market today is a P/E of 18.6x, so the question is whether that earnings multiple makes sense for a specialist in petroleum additives.
The P/E ratio compares what investors pay for each dollar of earnings. For a business like NewMarket that reports high quality earnings and a 23.6% return on equity, this measure gives a clear view of how profit generation lines up with the current share price.
Against peers, the gap is clear. The 18.6x P/E sits well below the 32.2x average of similar companies and also below the broader US Chemicals industry on 22.9x, which indicates the market is applying a lower earnings tag to NewMarket than it does to comparable stocks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 18.6x (UNDERVALUED)
Still, NewMarket faces real pressure if specialty chemicals peers see sharper earnings momentum, or if recent share price weakness deepens into a broader derating.
Find out about the key risks to this NewMarket narrative.
Another View: What NewMarket’s Cash Flows Suggest
The earnings multiple paints NewMarket as relatively cheap next to peers, yet the SWS DCF model goes further and values the future cash flows at $1,349.21 per share, compared with a market price of $873.27. That gap points to a different question: Is the market underestimating staying power, or is the model leaning too hard on past strength?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NewMarket for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around NewMarket feels familiar, consider taking the time now to review the details and pressure test the story yourself by examining the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond NewMarket?
You do not need to stop with NewMarket. Broaden your watchlist now with other focused ideas that match the kind of risk and reward profile you care about.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center when markets feel uncertain.
- Hunt for mispriced quality by reviewing a 19 high quality undiscovered gems that filters for strong fundamentals before wider attention arrives.
- Dial down potential volatility by using a 32 resilient stocks with low risk scores designed to highlight companies with sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com