


- Pathward Financial reported fourth quarter and full year results, with net interest income and net income lower than a year earlier but higher basic and diluted earnings per share from continuing operations.
- Net charge-offs rose to US$52.0 million, with heavier losses in seasonal tax services and commercial finance that highlight credit risk concentration in key portfolios.
- We will now examine how Pathward Financial's higher quarterly net charge offs could influence the broader investment narrative around the bank.
Pathward Financial Investment Narrative Recap
To own Pathward Financial, you need to be comfortable with a bank that leans heavily on fee based businesses like tax services and partner programs while running higher risk commercial finance books. The latest quarter kept earnings from continuing operations per share growing despite softer net interest income, which suggests the model can still convert capital efficiently in the near term.
The key short term swing factor is how credit costs evolve in commercial finance and seasonal tax products following the US$52.0 million in net charge offs. This already elevated loss experience keeps credit quality as the biggest immediate risk, while the main potential support remains execution in Partner Solutions and Professional Tax Services.
The most relevant update here is the fourth quarter and full year result to 30 September 2026. Net income for the quarter held close to last year at US$38.63 million, while basic EPS from continuing operations moved to US$1.86 from US$1.70. That mix signals meaningful support from buybacks and business mix, even as interest income softened.
For the full year, net interest income of US$474.93 million and net income of US$175.67 million frame the earnings base from which any future credit shocks would be absorbed. When you weigh those figures against the higher net charge offs, the investment question becomes whether Pathward Financial can keep growing fee driven businesses and managing capital returns without letting bad loans and provisions dominate the story.
How Pathward Financial's Higher Charge Offs Meet Analyst Expectations
Pathward Financial's narrative projects US$1.0b revenue and US$221.0 million earnings by 2029. This assumes revenue grows at about 10.9% a year and earnings rise by roughly US$45.4 million from the current US$175.6 million base.
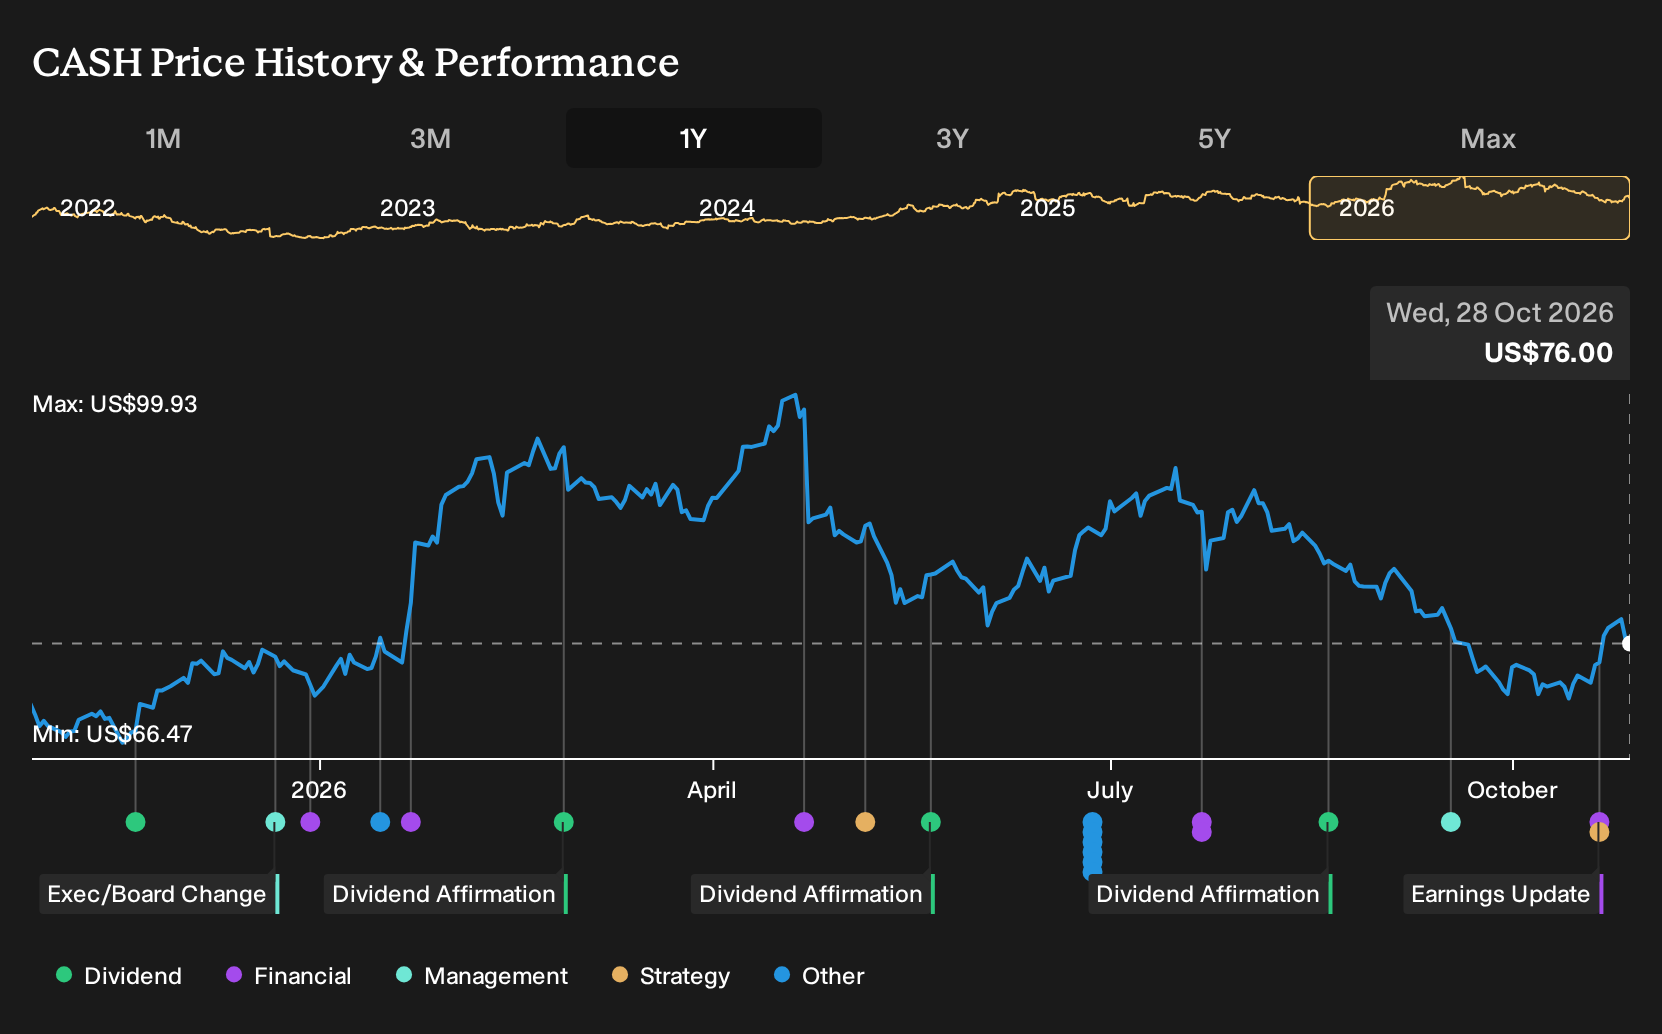
Uncover how Pathward Financial's fair value indicates a 33% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide band, from US$101 up to about US$210.78, which shows how far apart retail opinions on Pathward Financial can sit. Set that against the recent US$52.0 million in quarterly net charge offs and fraud linked credits, and you are looking at sharply different stories about future resilience. Explore those alternative views before deciding which version of the Pathward Financial narrative you find more convincing.
Explore 2 other Pathward Financial fair value estimates, including one that suggests up to 177% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pathward Financial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pathward Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pathward Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pathward Financial?
If Pathward Financial has sharpened your focus on risk, returns, and balance sheet strength, you can use that same lens across the wider market. The Simply Wall St Screener can help you quickly filter for companies that line up with the type of profile you want to research next.
- For investors who care most about quality at a sensible entry point, start with a curated set of 26 high quality undervalued stocks that combine fundamentals with pricing that may warrant a closer look.
- If reliable balance sheets matter most to you, focus your search on a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching leverage.
- Income focused readers can zero in on cash return potential by scanning a hand picked group of 6 dividend fortresses that pair yield with business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com