


Firefly Aerospace (FLY) just cleared a technical milestone that ties its stock story more tightly to real missions. Management completed the preliminary design review for the Elytra spacecraft supporting NASA’s MoonFall lunar south pole project.
Firefly Aerospace’s latest milestone lands after a choppy run for the shares, with the 30 day share price return down 17.67% and the year to date share price return lower by 16.46%. This comes even though the 7 day share price return gained 12.43%, while the 1 year total shareholder return declined 20.76%.
Scan beyond Firefly Aerospace and see how other space and defense players with solid fundamentals line up in our curated list of solid balance sheet and fundamentals (24 results)
Firefly Aerospace now trades at a steep discount to both intrinsic value estimates and analyst targets after that design win and a choppy year. Is the market prudently pricing the risks, or overshooting on caution as the valuation math lines up?
Most Popular Narrative: 49% Undervalued
Firefly Aerospace last closed at $19.85 while the most followed narrative pegs fair value at $38.60, so the story centers on a wide modeled gap between price and what long term contracts might justify.
Multi mission, multi orbit delivery needs that go beyond current launch offerings are highlighted in NASA’s Elytra study and the Defense Innovation Unit’s 2027 space domain awareness mission. These needs can support a pipeline of Elytra contracts and influence medium term revenue and earnings trajectory.
See why 47 investors see Firefly Aerospace as 49% undervalued.
Result: Fair Value of $38.60 (UNDERVALUED)
Still, the Firefly Aerospace story relies on unprofitable operations and recent Alpha reliability setbacks that could prevent contract wins from translating cleanly into future cash flow.
Find out about the key risks to this Firefly Aerospace narrative.
Another View: Firefly Aerospace Looks Expensive On Sales
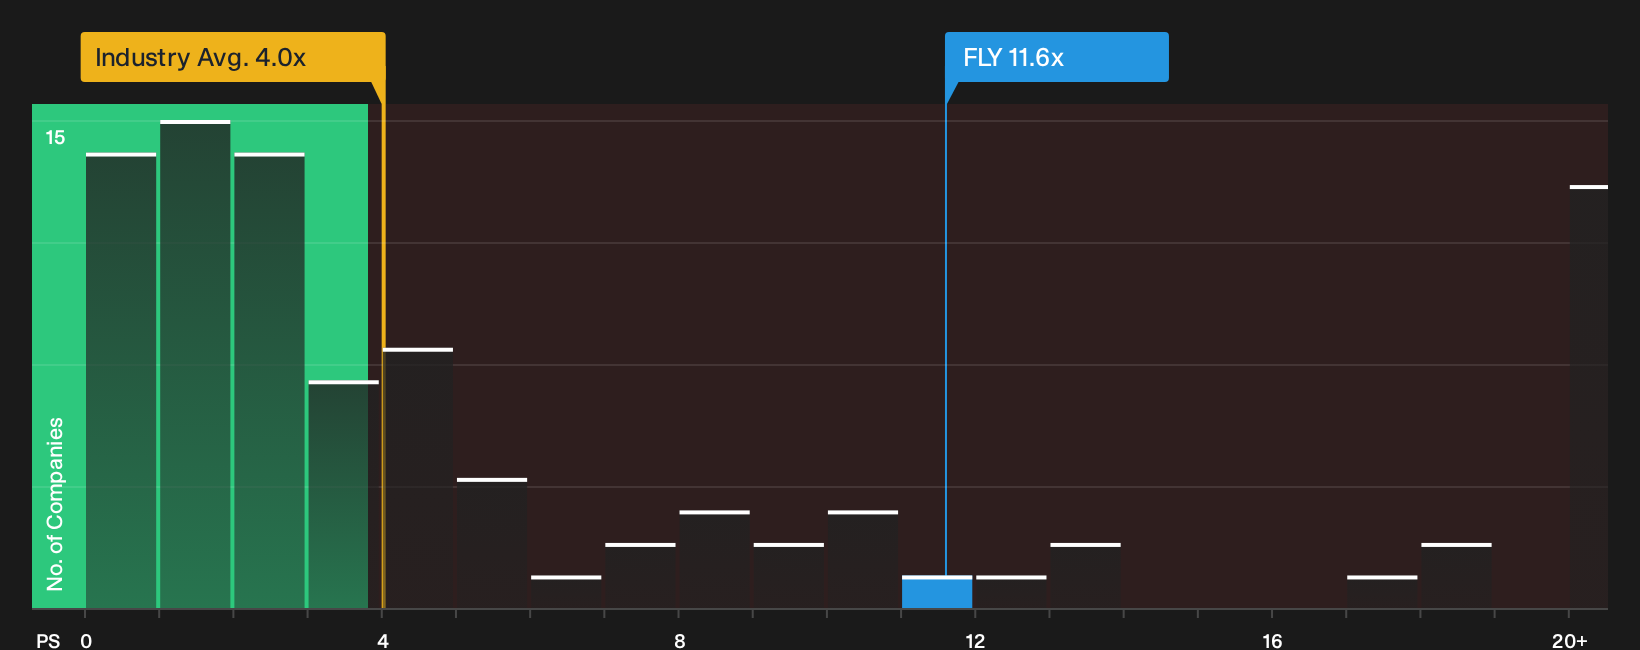
On the flip side of all that fair value upside, Firefly Aerospace trades on a P/S of 11.6x, compared with 4x for the wider US Aerospace & Defense group and a fair ratio of 5.6x. That is a wide premium. Is the market overpaying for future contracts that are still uncertain?
Our valuation breakdown using this sales multiple puts the spotlight on how much optimism is already baked into the current share price, and how far sentiment might have to reset if execution or funding headlines disappoint investors. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The story so far mixes optimism and caution, which is exactly why Firefly Aerospace is attracting fresh attention. Look through the contracts, balance sheet, and valuation work yourself, then weigh the 3 key rewards and 2 important warning signs.
Looking for more Firefly Aerospace style ideas?
Do not stop at Firefly Aerospace. Broaden your watchlist now with focused stock ideas that line up with the kind of risk and quality profile you care about.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount using the 26 high quality undervalued stocks before others catch on.
- Prioritise calmer nights and fewer surprises by scanning the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com