


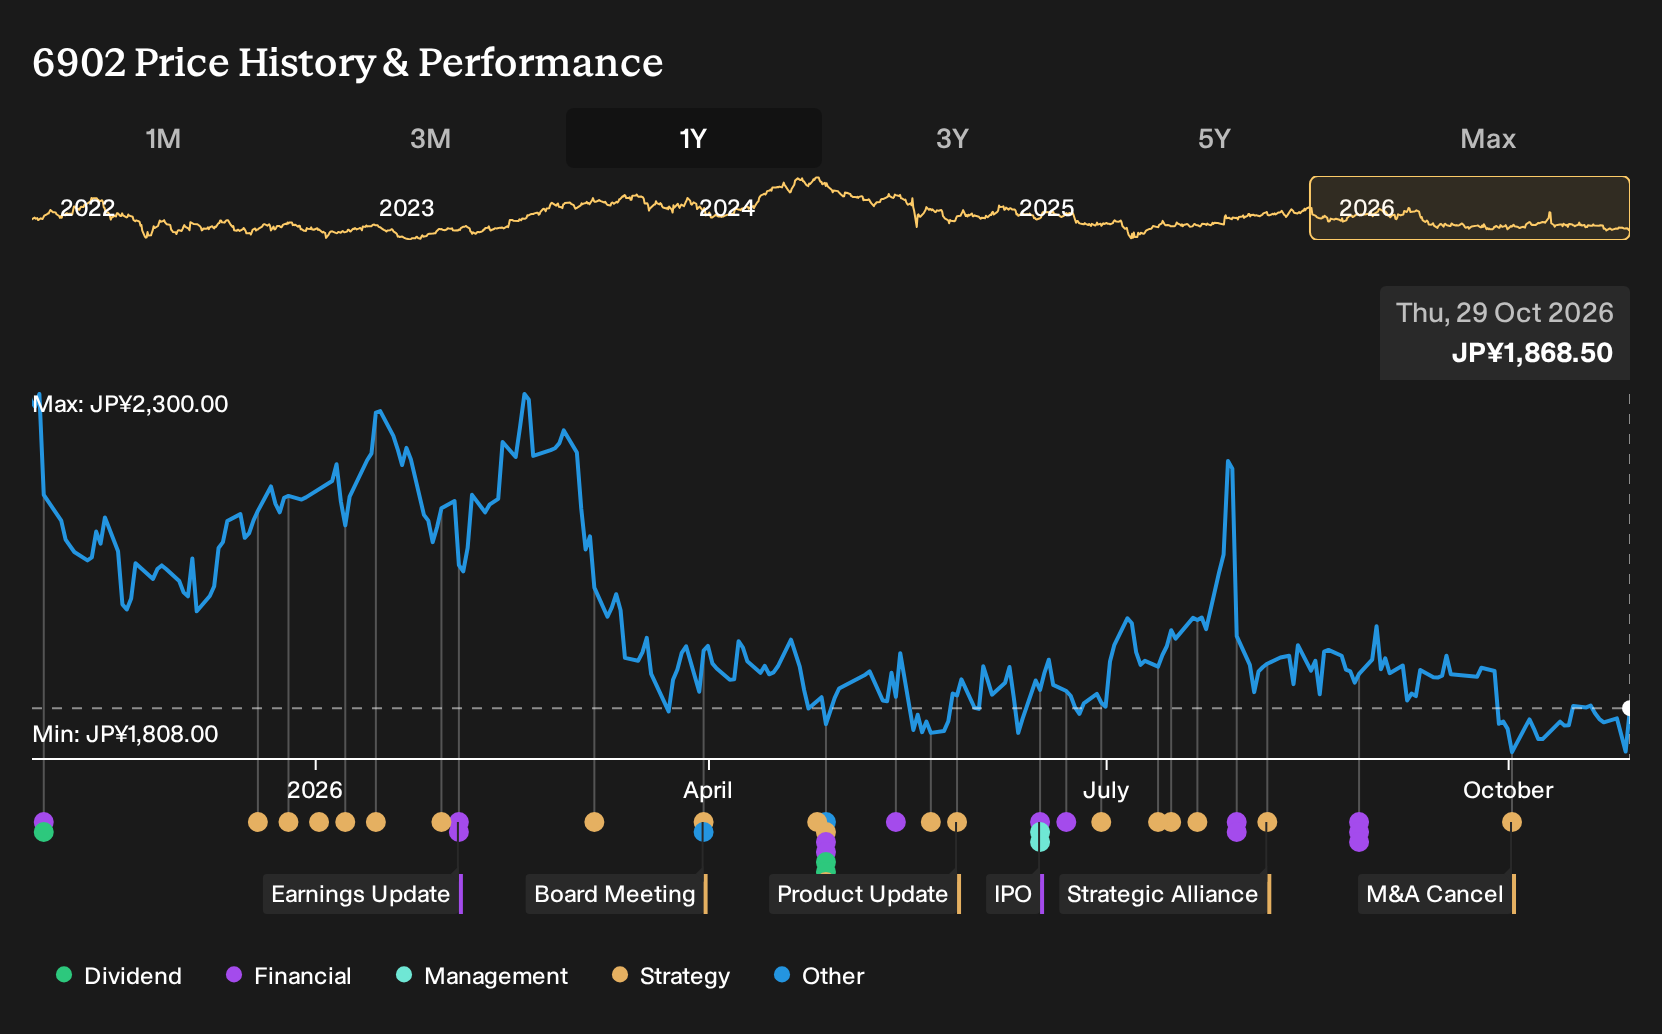
- DENSO Corporation announced a share repurchase program of up to 100,000,000 shares, or 3.99% of outstanding stock, for ¥200,000 million, alongside a second quarter dividend of ¥37 per share for the period ended September 30, 2026.
- The combination of a large buyback authorization funded alongside growth investments through borrowings and a higher dividend reflects deliberate capital structure management and an emphasis on stable, flexible shareholder returns.
- The focus now shifts to how DENSO's investment narrative is influenced by this sizeable buyback plan and higher recurring dividend commitment.
What Is DENSO's Investment Narrative?
DENSO is really an execution story. The thesis rests on whether this auto parts group can keep turning a broad product mix, from thermal systems to powertrains and safety modules, into steady earnings while managing heavy capital needs. Guidance for the year to March 2027, including revenue of ¥7,750,000m and operating profit of ¥500,000m, sets a clear performance bar. The large buyback and higher dividend sit on top of that. They matter only if cash generation and borrowing capacity comfortably support both investment and payouts.
In the short term, the main swing factors are demand from global automakers, pricing power in key systems, and how much capital is tied up supporting that growth. The new repurchase program and the raised ¥37 interim dividend tighten the link between DENSO's operating delivery and shareholder expectations. That can help frame a value case at a P/E of 10.8x, yet it also raises the cost of any execution slip, especially with net margins at 5.6% and returns on equity still in single digits.
Even so, there is a pressure point inside this higher payout story that could catch new shareholders off guard if...
There's only one way to know the right time to buy, sell or hold DENSO. Head to Simply Wall St's company report for the latest analysis of DENSO's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly ¥2,093 to ¥3,653 per share, which already shows how far opinions on DENSO can spread. These views do not yet reflect the new buyback or higher interim dividend, so you are seeing pre-announcement thinking. Use that gap to explore several contrasting viewpoints.
Explore another DENSO fair value estimate, including one that suggests it could be worth just ¥2093.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DENSO research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DENSO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DENSO's overall financial health at a glance.
Looking For More Investment Ideas Beyond DENSO?
If DENSO's capital return plan has you thinking about portfolio balance, it can help to line it up against other companies with different strengths. The Simply Wall St Screener lets you filter for traits that match your own risk and income preferences, so you can build a wider watchlist with intent rather than guesswork.
- If capital preservation is front of mind, start with companies that score well on resilience and financial risk by reviewing our 25 resilient stocks with low risk scores.
- If you want to pair valuation discipline with balance sheet strength, scan for ideas that blend cash flow support and solid fundamentals using our 15 high quality undervalued stocks.
- If income is a bigger priority for you, focus on stocks offering meaningful yields and payout support by checking our 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com