


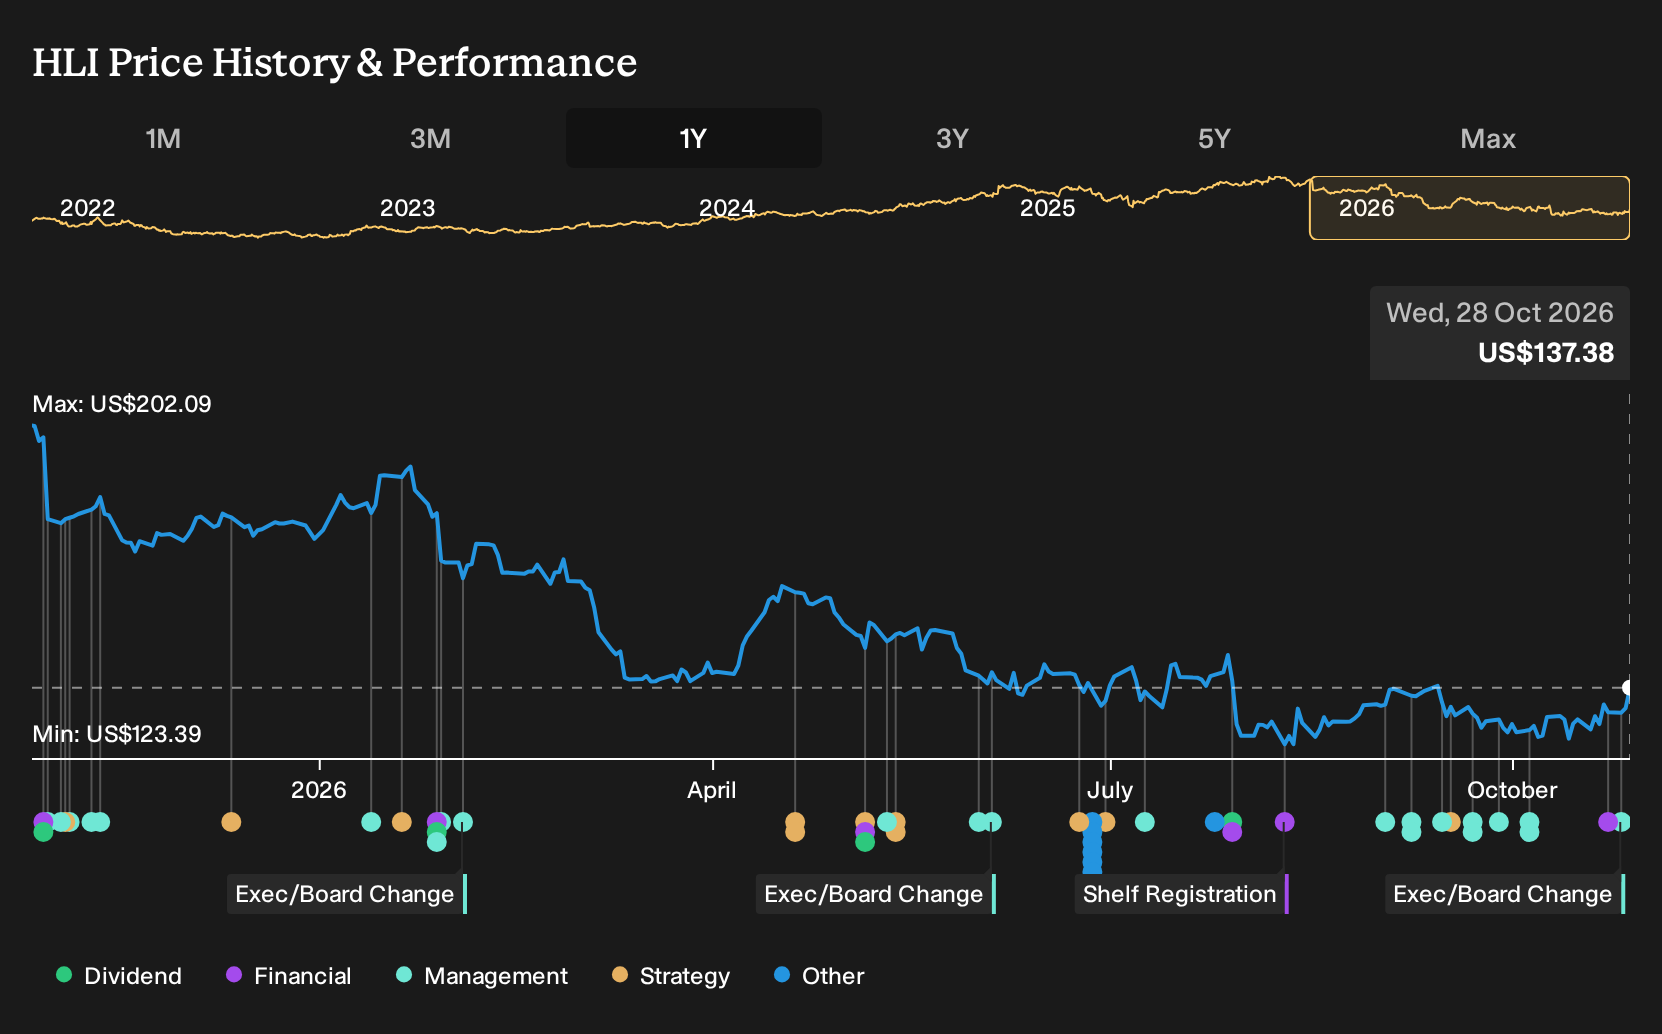
- Houlihan Lokey reported Q2 fiscal 2027 revenue of US$692 million, with adjusted earnings per share of US$1.85 that exceeded analyst estimates, and the board affirmed a regular quarterly dividend of US$0.70 per share payable on December 15, 2026.
- The results highlighted solid Corporate Finance performance despite fewer completed deals and continued investment in advisory talent, including the hire of Managing Director Derek Herbert into the Capital Solutions Group.
- We will now look at how Houlihan Lokey's earnings beat and dividend decision interact with the existing investment narrative and expectations.
Compare Houlihan Lokey's earnings beat and dividend with other potential opportunities by scanning our hand picked list of 26 high quality undervalued stocks that also pair cash generation with balance sheet strength.
Houlihan Lokey Investment Narrative Recap
To own Houlihan Lokey, you need to be comfortable with an advisory model where fee revenue depends on deals closing, not just on a strong pipeline. The latest quarter showed revenue of US$692 million with adjusted EPS of US$1.85 holding steady, which helps the near term story that Corporate Finance and advisory diversification can offset softer pockets like restructuring.
The key short term swing factor is whether current mandates in Corporate Finance and newer areas like Capital Solutions convert into higher fee transactions quickly enough to outpace rising compensation and non compensation costs. The biggest risk remains muted sponsor activity or delayed larger deals, which could quickly pressure margins even with a solid headline quarter.
The fresh US$0.70 quarterly dividend declaration is the announcement that ties most cleanly into this earnings beat. It indicates the board is comfortable maintaining cash returns to shareholders at the existing level while the firm invests in hires, technology and acquisitions like Intrepid Financial Partners to deepen its advisory bench.
For catalysts, that dividend sits alongside operational levers such as expansion in Capital Solutions and secondaries, where senior hires like Derek Herbert are intended to increase higher value transactions over time. Execution risk sits on the other side of the ledger, because elevated compensation ratios and technology spend will need sustained advisory fee generation to avoid squeezing profitability.
Houlihan Lokey's current narrative assumes revenues of US$3.6b and earnings of US$626.5 million by 2029, built on forecast annual top line growth of 12.5% and an earnings increase of roughly US$220.8 million from US$405.7 million today.
Uncover why Houlihan Lokey's fair value indicates a 12% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One alternate view focuses on Houlihan Lokey’s cost pressure rather than the dividend or earnings beat. The most cautious analysts were pencilling in about US$3.3b of revenue and US$563.5 million of earnings by 2029. That is a slower build than the baseline. Use that gap as a prompt to compare several narratives that may now shift.
Explore 2 other Houlihan Lokey fair value estimates, including one that suggests it could be worth just $153.50.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Houlihan Lokey research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Houlihan Lokey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Houlihan Lokey's overall financial health at a glance.
Looking For More Ideas Beyond Houlihan Lokey?
Once you have a view on Houlihan Lokey, it can help to line it up against other potential opportunities so you can decide where the best risk and reward trade off sits for your portfolio.
- For investors who want potential mispricing combined with quality fundamentals, review our curated set of 19 high quality undiscovered gems that may not yet be on most radars.
- If capital protection and resilience matter most to you, compare Houlihan Lokey with a 32 resilient stocks with low risk scores that score well on financial strength and volatility.
- Income focused investors can scan a 6 dividend fortresses that offer higher yields while still aiming to preserve balance sheet quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com