


MediPal Holdings (TSE:7459) has stepped into the spotlight after raising full year profit guidance and unveiling a ¥10,000 million share repurchase plan, moves that arrive amid ongoing pressure from top shareholder Silchester.
Those announcements land after a strong run in MediPal Holdings’ shares, with a 30 day share price return of 14.47% and a 90 day gain of 17.13%, while the 1 year total shareholder return of 37.82% points to momentum that has been building rather than fading.
Scan how MediPal Holdings stacks up on capital efficiency and shareholder returns alongside a hand picked set of peers in the 15 high quality undervalued stocks.
MediPal Holdings now trades above the average analyst target yet still shows a modelled discount to intrinsic value. Is the market correctly pricing in governance friction, or is caution disconnecting from the fundamentals that support that valuation gap?
Preferred P/E of 14.8x: Is it justified?
The SWS DCF model points to a fair value of ¥3,986.95 for MediPal Holdings, which is about 15.3% above the last close of ¥3,377, while the current P/E multiple sits slightly ahead of sector and peer averages.
Price to earnings compares what investors are paying today for each unit of profit the business generates. This can be especially useful for an established distributor like MediPal Holdings with positive net income and a long trading history.
The stock trades on a P/E of 14.8x, higher than both the JP Healthcare industry average of 14.3x and the peer group on 13.5x, yet below an estimated fair P/E of 18.1x. This suggests the market is not pricing earnings at the upper end of what that fair ratio implies.
Explore the SWS fair ratio for MediPal Holdings.
Result: Price-to-Earnings of 14.8x (ABOUT RIGHT)
Still, ongoing governance friction with Silchester and MediPal Holdings, which are trading above the average analyst target, could become flashpoints if execution or capital allocation disappoints.
Find out about the key risks to this MediPal Holdings narrative.
Another View on MediPal Holdings’ Value
A second lens comes from the SWS DCF model, which points to fair value around ¥3,986.95 versus the current ¥3,377 share price. That gap signals the cash flow outlook is richer than the earnings multiple implies. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
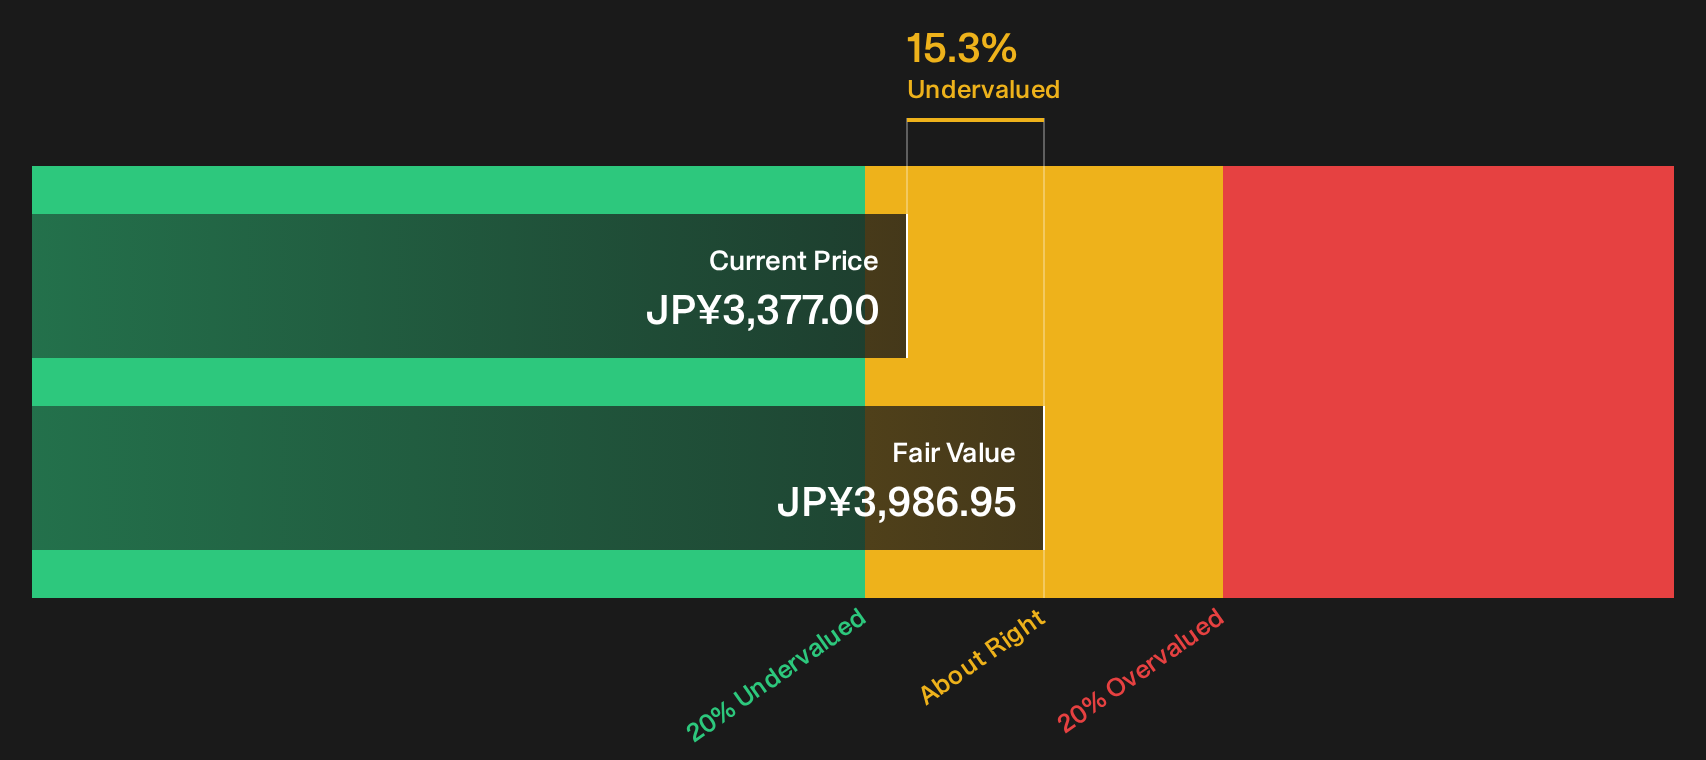
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MediPal Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the tone of this MediPal Holdings story skewing optimistic or cautious for you today? Move fast, stress test the numbers against your own expectations, then pressure test that optimism by checking the 4 key rewards.
Looking for more investment ideas beyond MediPal Holdings?
If MediPal Holdings already feels priced on your terms, do not stop here. Scan fresh opportunities now before the next wave of capital sets the tone.
- Target income resilience by reviewing companies that show up in our 29 dividend fortresses and see which payouts align with your risk tolerance.
- Hunt for quality at a markdown with the 72 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Dial down portfolio stress by scanning the 25 resilient stocks with low risk scores that aim to balance return potential with steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com