


- Halozyme Therapeutics recently featured as a top contributor in Renaissance Investment Management's Q3 2026 Large Cap Growth Strategy, supported by strong royalties from demand for its subcutaneous therapies and scaling product launches alongside solid second quarter operating results.
- An interesting angle is how Halozyme Therapeutics' asset light, royalty driven model is being reinforced by growing uptake of partner at home biologic delivery products and newer ENHANZE launches.
- We will look at how Halozyme Therapeutics' royalty driven investment narrative is shaped by strong subcutaneous therapy demand and product scaling.
Track how Halozyme Therapeutics' royalty model compares to other fast scaling healthcare plays by reviewing the hand picked 36 healthcare AI stocks that are riding similar demand for next generation treatments.
Halozyme Therapeutics Investment Narrative Recap
For Halozyme Therapeutics, the core belief you need is that the royalty model around ENHANZE, Hypercon and related platforms remains attractive to large pharma partners and keeps pulling in new deals over time. The recent recognition as a top contributor in a large cap growth portfolio ties directly to that thesis because it highlights how partner product uptake is already translating into royalties and operating scale.
In the near term, the key swing factor is how quickly newer subcutaneous launches and at home biologic formulations ramp, given royalty revenue depends on partner sales execution. The biggest near risk sits around pricing and reimbursement pressure, as well as rival subcutaneous platforms that could influence future royalty terms or slow new agreements if they gain more traction.
The most relevant recent development around this story is Halozyme Therapeutics posting solid second quarter operating results while being flagged as a major positive contributor for Renaissance Investment Management’s Q3 2026 Large Cap Growth Strategy. That combination shows that the engine driving the asset light model is not just theoretical; it is already visible in current revenue and earnings.
For catalysts, that operational backdrop links directly to the ramp of ENHANZE enabled products like Darzalex and VYVGART, the fast adoption of newer subcutaneous therapies and the build out of Hypercon and Surf Bio programs. Execution on these launches, along with careful management of regulatory and competitive pressures, will likely shape how durable the royalty streams look and how investors frame both upside and risk from here.
What The Current Forecasts Assume For Halozyme Therapeutics
Analysts are effectively pitching Halozyme Therapeutics as a royalty engine that scales into the back half of the decade, with the numbers already mapped out in some detail. The current consensus assumes revenue expands at 10.6% a year over the next three years while profit margins move from 24.9% today to 51.4% by 2029. That margin shift matters as much as the top line because it frames how much of each incremental royalty dollar is expected to drop to the bottom line.
On earnings, forecasts call for profit to move from US$413.6 million today to US$1.2b by 2029, with earnings per share modeled at US$9.95. That jump implies roughly a 3x increase in earnings, helped by expected share count reduction of 3.49% a year over the next three years. For a royalty led business like Halozyme Therapeutics, shrinking the share base while expanding high margin revenue can compound per share earnings power even if deal flow simply tracks current expectations.
Valuation assumptions are just as specific. To line up with the current analyst framework, investors would need to assume Halozyme Therapeutics generates about US$2.3b of revenue and US$1.2b of earnings in 2029 and then trades at a P/E of 12x on those earnings. That is a step down from the current 33.3x multiple and also below the cited US Biotechs industry P/E of 17.9x, which means the scenario leans on earnings expansion more than on multiple expansion.
Halozyme Therapeutics' narrative projects about US$2.3b of revenue and US$1.2b of earnings by 2029. This framework assumes 10.6% yearly revenue growth and roughly a 3x earnings increase from US$413.6 million today.
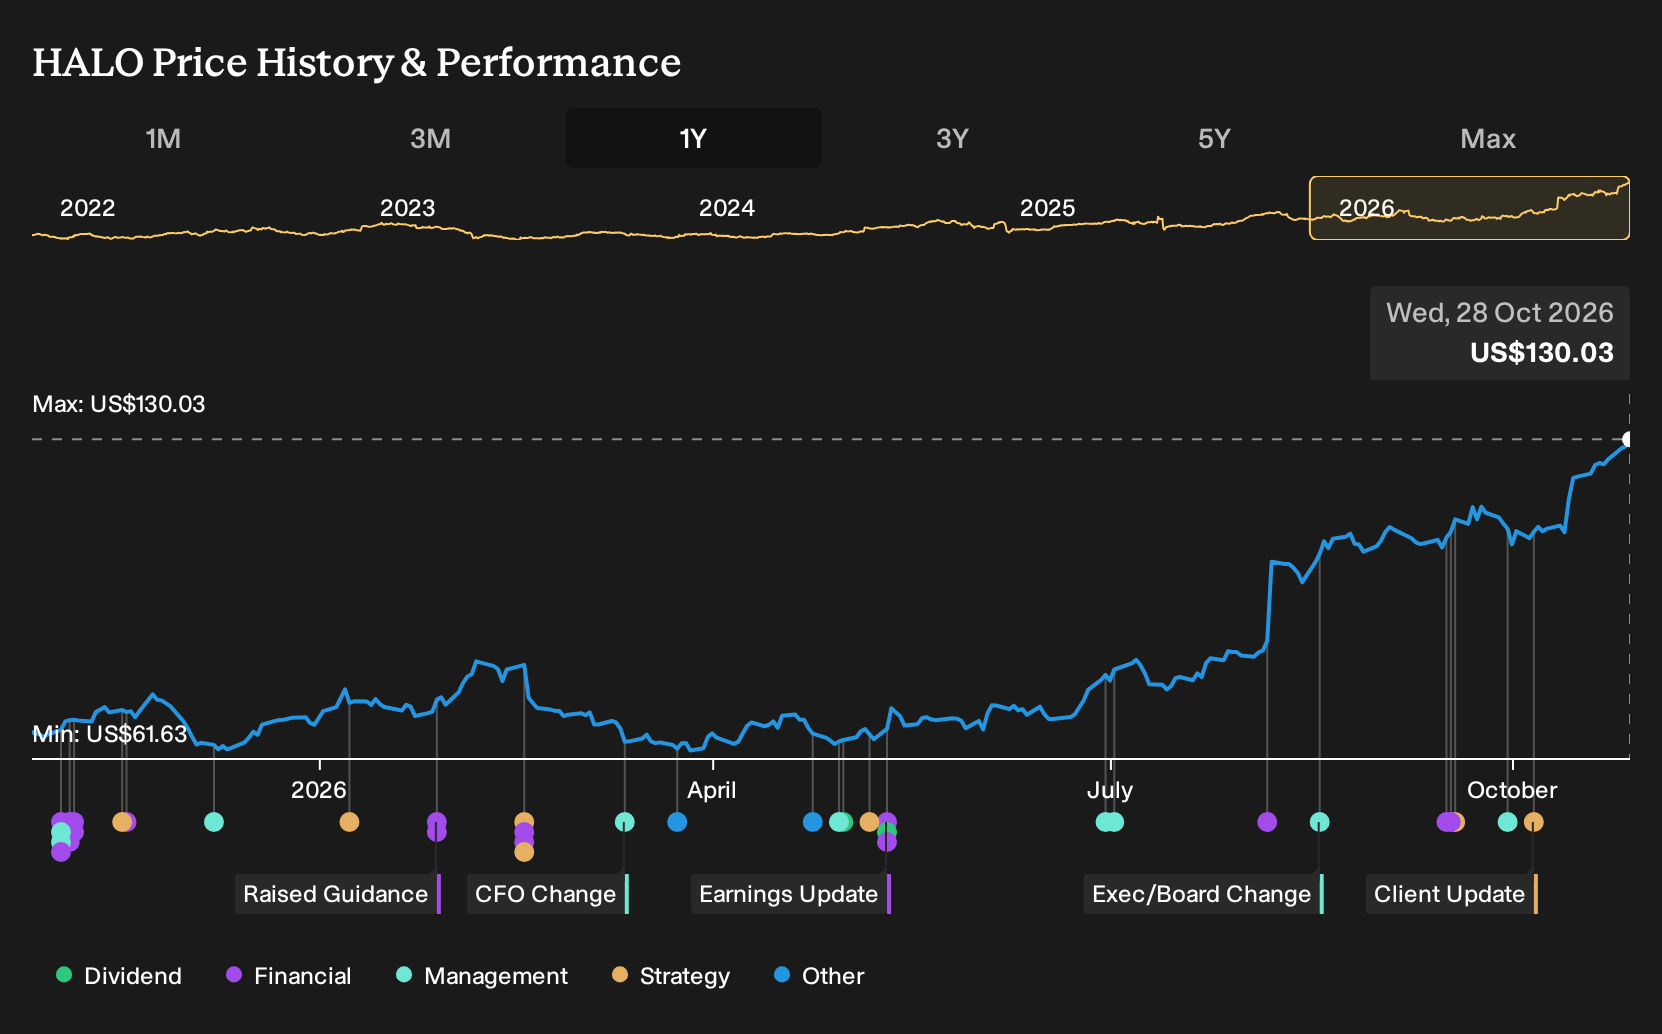
Price targets pulled from the same framework show a split view. The consensus figure sits at US$108.78 a share, with the highest estimate at US$130 and the lowest at US$78. With the stock recently around US$121.51, that average target is about 11.7% lower. This suggests many analysts see strong fundamental progress already more than reflected in the quote.
For readers tracking whether this setup feels reasonable, the key questions are straightforward. Do the revenue and margin paths for Halozyme Therapeutics feel achievable given its existing ENHANZE roster and upcoming Hypercon and Surf Bio ramps? Does a much lower P/E multiple on higher earnings feel plausible by 2029 if royalty streams mature and growth slows from these modeled levels? Your view on those points will likely matter more than the exact price target numbers that come out of the models.
Uncover why Halozyme Therapeutics' fair value indicates a 16% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view puts competition risk front and center for Halozyme Therapeutics. The most bearish analysts assume rivals like ALT-B4 cap future royalty economics and therefore plug in roughly US$2.3b of 2029 revenue but only a 7.7x P/E, despite earnings forecasts of about US$1.3b. That is a much harsher narrative than consensus. Both sets of forecasts were built before the recent recognition in Renaissance’s Q3 2026 report, so you should expect opinions to shift. Use this divergence as a cue to compare several viewpoints before deciding how comfortable you feel with royalty and patent risk.
Explore 4 other Halozyme Therapeutics fair value estimates, including one that suggests up to 16% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Halozyme Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Halozyme Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halozyme Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Halozyme Therapeutics?
Once you have a view on Halozyme Therapeutics, it can help to benchmark that thinking against other opportunities using the Simply Wall St Screener. Different filters highlight very different types of prospects, so casting a wider net lets you see where this royalty model sits relative to businesses with steadier balance sheets, stronger income durability, or deeper value characteristics.
- If capital preservation sits high on your priority list, check out a set of companies screened for resilience through the 32 resilient stocks with low risk scores.
- For investors who want financial strength to be non negotiable, start with the list of solid balance sheet and fundamentals (24 results) and compare how those fundamentals stack up against Halozyme Therapeutics.
- To widen your watchlist with opportunities that receive less attention, scan through a carefully filtered 19 high quality undiscovered gems that pair quality fundamentals with under-the-radar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com