


Cybersecurity is getting more complicated as businesses bring artificial intelligence (AI) into their everyday operations. CrowdStrike (CRWD) helps businesses protect their systems, data, and networks from cyber threats through its Falcon cybersecurity platform. Now, it’s looking to tackle another growing concern: Keeping AI agents secure.
In September, CrowdStrike launched Falcon Guardian, an AI detection and response product designed to help security teams monitor AI agents across corporate environments, including cloud services, browsers, and business applications. As companies move AI tools from experiments into daily workflows, Guardian aims to give them better visibility into what these agents are doing and how they interact with sensitive systems and data. The product also expands CrowdStrike’s existing AI detection and response capabilities, with a significantly higher price point than its earlier offering.
The launch has also caught Wall Street’s attention. Last week, Mizuho raised its price target on CRWD stock to $275, citing encouraging early feedback and Guardian’s potential to unlock additional revenue. So, what’s catching Mizuho’s eye about Falcon Guardian, and how could it fuel CrowdStrike’s next phase of growth? Let’s take a closer look.
About CrowdStrike Stock
Based in Austin, Texas, CrowdStrike has grown into a major name in the cybersecurity industry, with a market capitalization of around $273 billion. The company helps businesses protect their digital operations from cyber threats, covering everything from computers and cloud systems to employee identities and sensitive data.
At the heart of its business is the Falcon platform, which brings together threat intelligence, real-time security data, and insights into how cybercriminals operate. Simply put, it helps companies spot potential attacks, respond to threats faster, and identify security weaknesses before they become bigger problems.
CrowdStrike’s cloud-based technology also makes things easier for businesses. Its lightweight software agent lets organizations deploy security tools across their systems without adding much operational complexity. By bringing multiple security capabilities together on one platform, CrowdStrike aims to help companies manage protection more efficiently while saving time and resources.
As businesses increasingly focus on cybersecurity, CrowdStrike has built a strong market position, supporting the growth story behind CRWD stock. The cybersecurity company’s shares have gained 290% over the past five years and surged 467% over the past three years. Over the past 52 weeks, CRWD stock has climbed 89%.
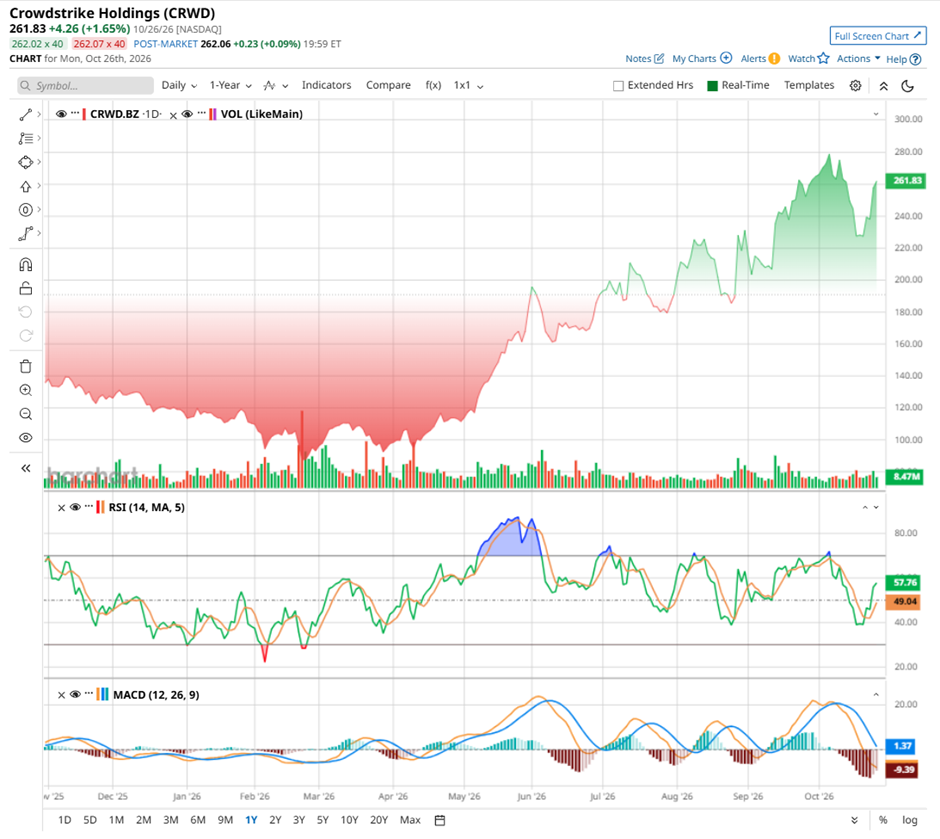
Zooming in, the stock has jumped 44% over the past three months, and climbed 9% over the past five days alone. CrowdStrike stock hit a record high of $286.99 in early October before pulling back roughly 10% to current levels. The stock’s rally gained momentum earlier in the month following news that U.S. prosecutors closed an investigation into certain deals involving a distributor without taking further action. Meanwhile, growing concerns about cyber threats — particularly as businesses embrace AI and geopolitical tensions keep digital security in focus — have helped support investor interest.
The technical indicators offer a mixed picture. The 14-day RSI is now around 54, suggesting momentum is improving after cooling from overbought levels in early October. In simple terms, buyers appear to be regaining some ground.
However, the MACD oscillator is flashing a different signal. The MACD line has slipped below its signal line, while the histogram has turned negative, suggesting bearish momentum could be building. That doesn’t automatically mean another decline is coming, but it does hint that CRWD stock may need a breather after its strong rally.
CrowdStrike’s growth story doesn’t come cheap, and Wall Street isn’t exactly getting a bargain here. CRWD stock trades at around 57 times sales, well above many cybersecurity peers and its own five-year average. That premium leaves little room for disappointment. If growth expectations wobble, investors could quickly remind the stock that even cybersecurity has its limits.
A Snapshot of CrowdStrike’s Q2 Results
CrowdStrike reported second-quarter fiscal 2027 results on Aug. 26, and Wall Street’s expectations turned out to be a little too modest. Revenue came in at $1.47 billion, up 26% year-over-year (YOY) and comfortably ahead of analysts’ estimates. Subscription revenue, the backbone of CrowdStrike’s business, climbed 27% YOY to $1.4 billion. As businesses embrace AI, protecting their systems and data is becoming increasingly important, giving CrowdStrike’s Falcon platform more room to grow.
CrowdStrike’s profitability improved, too, as the company benefited from operating leverage and disciplined cost management. Non-GAAP net income attributable to CrowdStrike grew to $322.9 million, translating into non-GAAP EPS of $0.31, beating Wall Street’s estimate. Non-GAAP subscription gross margin also edged higher to 81%, compared with 80% in the year-ago quarter.
Meanwhile, the company’s recurring revenue engine kept picking up speed. Annual recurring revenue (ARR) climbed 25% YOY to $5.84 billion as of July 31, 2026. Even better, CrowdStrike added a record $332.8 million in net new ARR during Q2. That suggests existing and new customers continue to provide meaningful opportunities for expansion.
Cash generation offered another reason to cheer. Net cash from operating activities jumped to $530.3 million from $332.8 million a year earlier, while free cash flow increased to $377.4 million from $283.6 million. CrowdStrike also ended the quarter with $5.01 billion in cash and cash equivalents.
CEO and co-founder George Kurtz called it the company’s “best quarter” in its history, highlighting record Falcon Flex results, record net new ARR, and accelerating growth. Kurtz also pointed to the “Mythos moment” as a turning point in broader AI acceptance and the growing recognition that AI adoption must go hand in hand with security. With enterprises increasingly relying on AI, he believes CrowdStrike is approaching its largest market opportunity yet.
Looking ahead, CrowdStrike seems to have plenty of momentum to carry it into the coming quarters, backed by a record Q3 pipeline. Revenue for Q3 is anticipated to be between $1.523 billion and $1.529 billion, while non-GAAP EPS is expected to be $0.31.
The company raised its fiscal 2027 revenue forecast to between $5.99 billion and $6.01 billion. It also boosted its net new ARR growth guidance to $1.35 billion to $1.359 billion, representing approximately 34% YOY growth. Meanwhile, non-GAAP EPS is projected to be between $1.25 and $1.26. That’s a stronger growth outlook, with CrowdStrike betting on continued demand for its cybersecurity offerings.
Analysts tracking CrowdStrike expect fiscal 2027 EPS to be $0.08, before rising by another 175% YOY to $0.22 in fiscal 2028. Revenue for fiscal 2027 is expected to rise to $6 billion, then reach $7.4 billion in the next fiscal year.
What Do Analysts Expect for CrowdStrike Stock?
Optimism around CrowdStrike is picking up on Wall Street. Mizuho is upbeat about CrowdStrike’s growth prospects, and Falcon Guardian is a big reason why. Mizuho recently raised its price target on CRWD stock to $275 from $250 while reiterating an “Outperform” rating.
Analyst Gregg Moskowitz said that recent checks revealed encouraging partner feedback on Guardian, describing it as a “substantial expansion” of CrowdStrike’s earlier AI detection and response (AIDR) capabilities. Some partners also indicated that Guardian comes with a much higher price tag than the company's prior offering, potentially opening the door to additional revenue.
Although details remain limited, partners have reportedly “highlighted a robust pipeline” for the new product, strengthening Mizuho’s confidence in CrowdStrike’s AI security opportunity. Moskowitz also pointed to other growth drivers, including Falcon Flex and CrowdStrike’s “emerging AI security portfolio,” which could help boost ARR. While Mizuho acknowledges the stock’s premium valuation, it sees multiple opportunities for further growth.
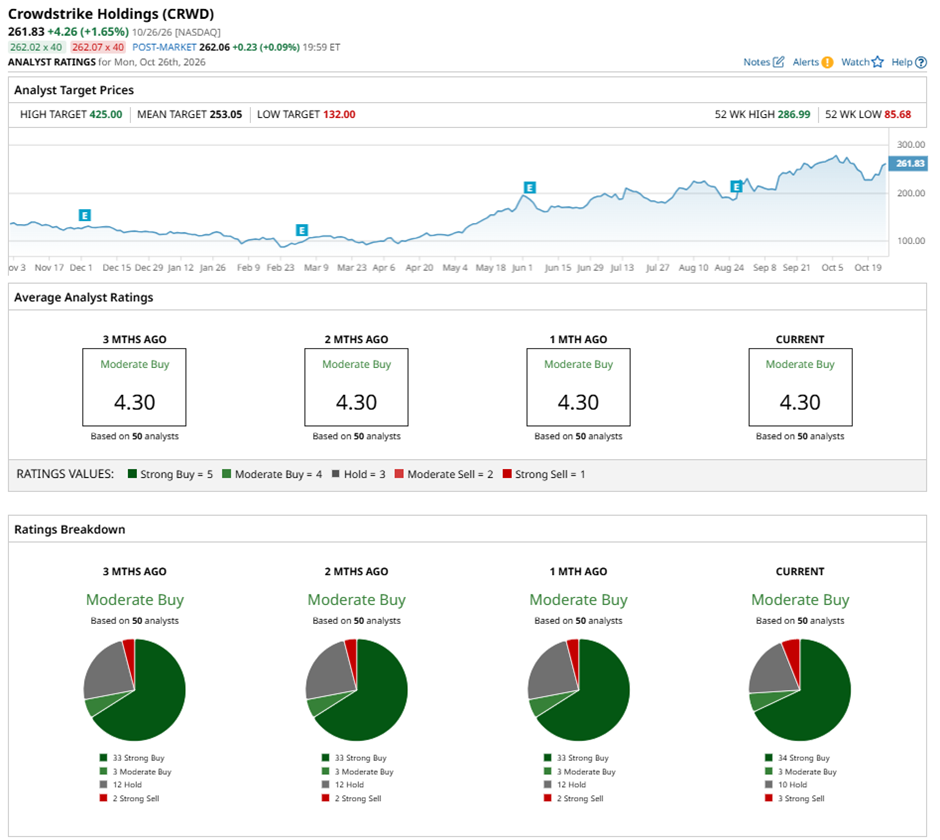
Overall, analysts are confident in CRWD stock, albeit with a dash of caution. The stock has a consensus “Moderate Buy” rating on Wall Street. Of the 50 analysts covering shares, 34 recommend a “Strong Buy” rating, three suggest a “Moderate Buy,” 10 have a “Hold” rating, and three analysts have a “Strong Sell” rating. CrowdStrike stock has surpassed the average price target of $253.68. Meanwhile, the Street-high price target of $425 suggests shares could rally as much as 65% from current levels.
On the date of publication, Sristi Suman Jayaswal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.