


Aisan Industry stock closed at ¥2,054, with recent 30 day and 90 day returns both in decline, just as fresh Q2 2027 earnings landed. The headline is about profitability compression. Quarterly basic earnings per share slipped to ¥61.53 and net income came in at ¥3,531 million, softer than several recent quarters despite higher revenue of ¥87,427 million. Short term traders see a stock that has struggled for months. Long term holders are now weighing a cheaper trailing P/E of 8.8x against signs that margins and dividend coverage are being squeezed.
Like the value on offer in Aisan Industry’s 8.8x trailing P/E but uneasy about the pressure on margins and dividend cover? Check out list of solid balance sheet and fundamentals stocks (23 results) for ideas that pair lower valuation multiples with sturdier balance sheets and payout support.
Q2 2027 Earnings Summary
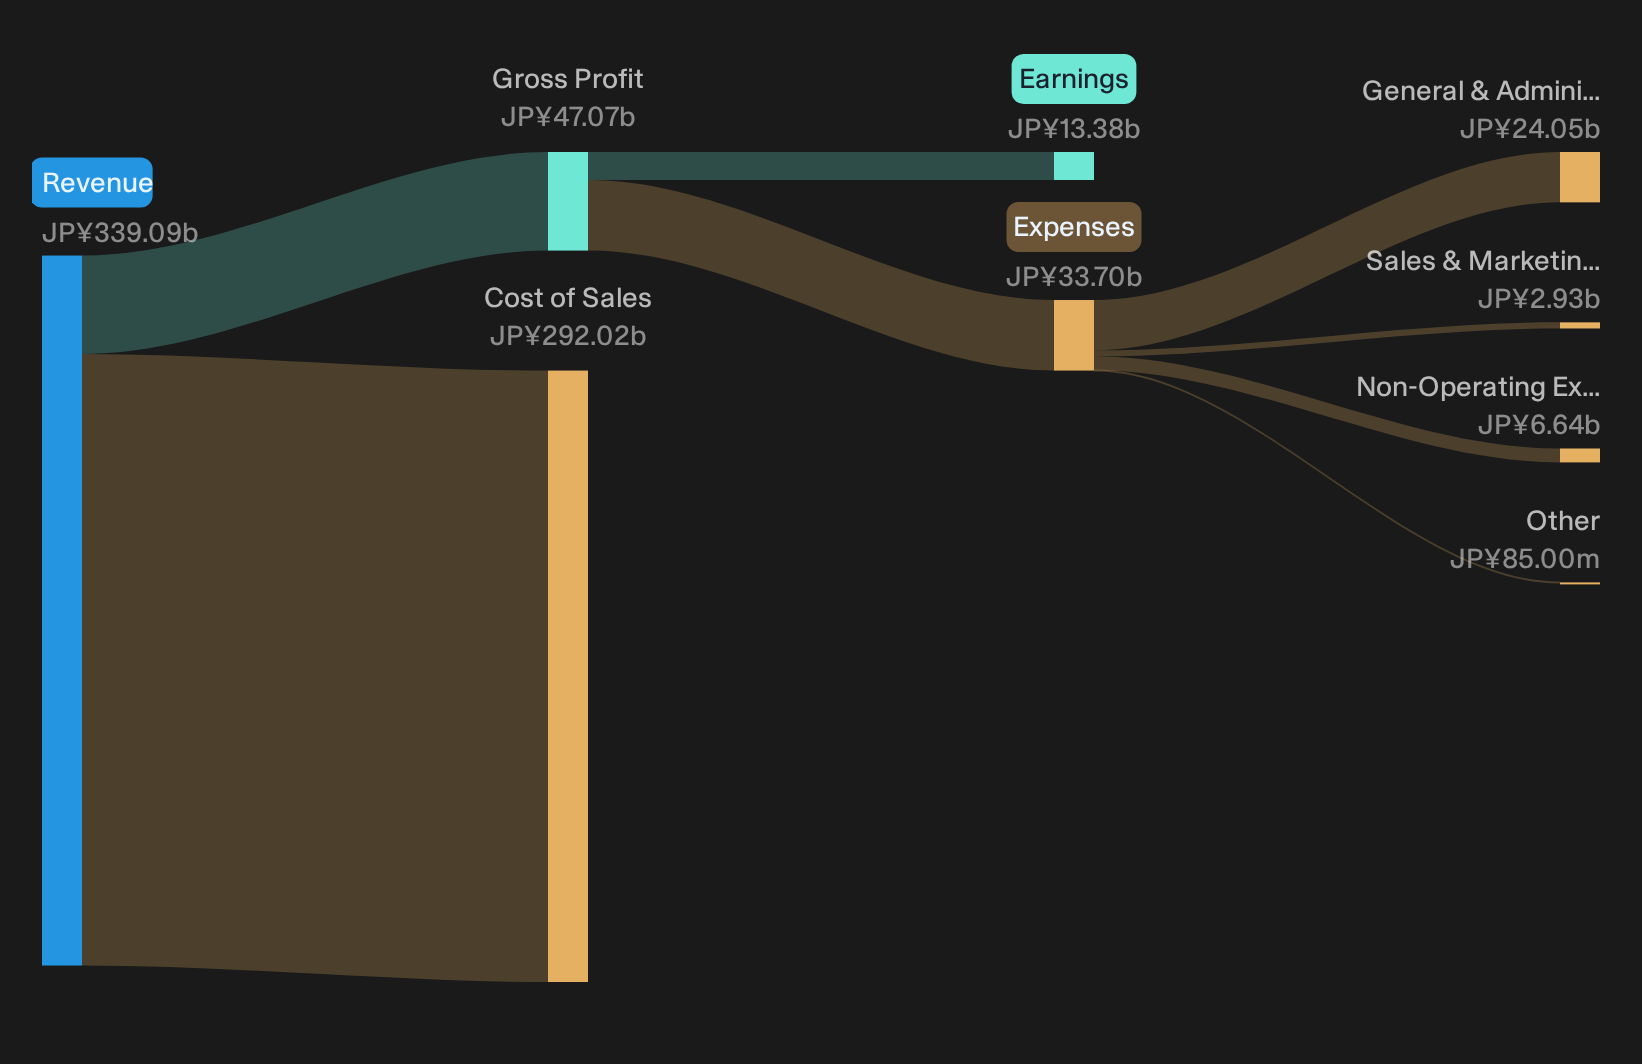
- Revenue (Q2 2027 vs. Q2 2026): ¥87,427 million vs. ¥83,173 million (higher quarterly top line year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥3,531 million vs. ¥4,027 million (lower quarterly profit year on year)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥61.53 vs. ¥70.38 (earnings per share declined year on year)
- Trailing Twelve Month Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥13,376 million vs. ¥12,809 million (modest improvement in earnings over the past year)
Earnings only tell part of the story, and investors who care about valuation usually pay close attention to the cash coming through the door over time. Looking at Aisan Industry's cash flows alone, the stock could be a dramatic 46% undervalued.
Aisan Industry bullish story under modest pressure
For anyone leaning positive on Aisan Industry, the revenue line does some of the heavy lifting. The top line in Q2 2027 is higher than a year earlier, and trailing twelve month earnings are also ahead of the prior period. That supports a view of an ICE focused parts producer that is still generating meaningful profit and cash potential. The soft spot is quarterly EPS, which moved lower year on year and reminds you that volume resilience does not automatically translate into stronger per share economics.
Bearish concerns get fresh support from margins
Bears looking at Aisan Industry will find plenty to point to in this quarter. Profit fell year on year even as revenue improved, which implies some margin compression right where investors want reassurance. EPS tells the same story in simpler form, with per share earnings softer than Q2 2026 despite a higher sales base. Shorter term share price performance has also been weak over 30 and 90 days, which signals that equity holders are already treating these pressures as more than just noise.
After experiencing margin slippage and issuing a dividend that current free cash flow does not fully support, it is reasonable to ask whether Aisan Industry faces deeper structural issues. Review the full risk analysis for Aisan Industry which shows 1 important warning signHunt For Mispriced Earnings Power
Aisan Industry just reminded investors that rising revenue can still sit alongside uncomfortable pressure on profitability. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 1 - 44% below our estimate - serves deposit, lending, leasing and securities clients as business users and households move relationships. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 2 - 39% below our estimate - builds virtual talent franchises that corporate marketers hire for branded events and digital campaigns. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 3 - 35% below our estimate - wins construction and real estate mandates as infrastructure owners refresh logistics hubs and public facilities. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
Those are three of them. See the full list of 14 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com