


DoorDash (DASH) shares pushed higher on Thursday after the delivery giant announced a $17 billion agreement to acquire Instacart, accelerating its expansion beyond restaurant meals. The proposed deal would bring together two major delivery platforms, giving DoorDash greater reach in groceries and another way to compete with Amazon (AMZN) and Walmart (WMT).
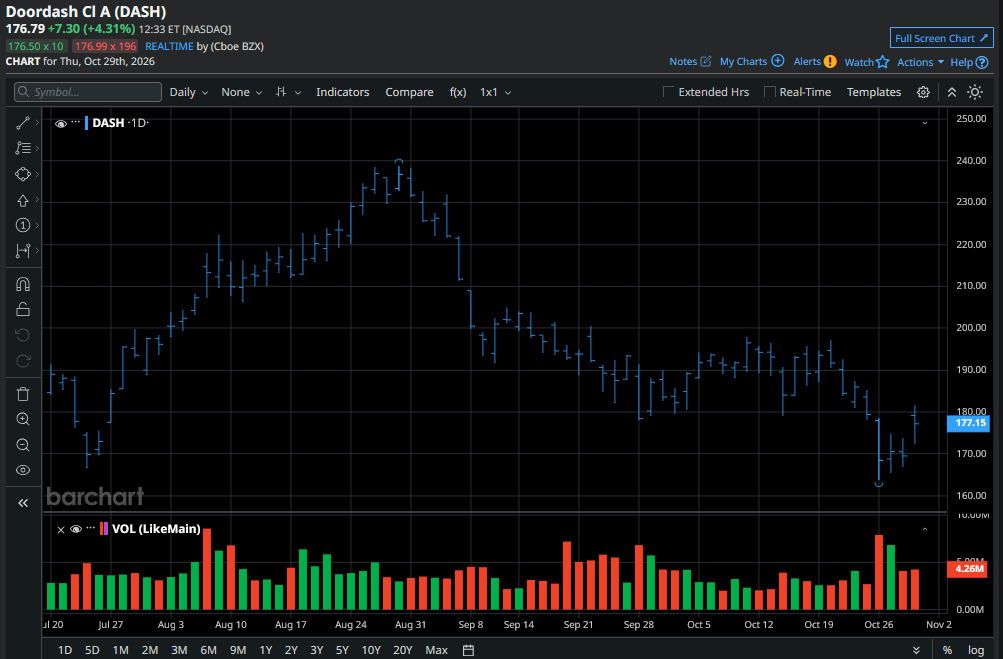
The acquisition news arrives as DoorDash stock is scrambling to regain momentum. The stock is currently down about 25% versus its recent high.
Why Is DoorDash Paying a Premium for Instacart?
DoorDash’s proposal values Instacart shares at $65 each, representing an 11% premium on their previous close.
For investors, the attraction extends beyond adding grocery orders. Combining the companies’ membership programs could encourage households to use the platform for both weekly shopping and restaurant meals, potentially improving retention and spreading the customer acquisition costs across more purchases.
Over time, this could strengthen DoorDash’s position against larger retailers. That said, shareholders face a lengthy wait: closing is expected in late 2027 or the first half of 2028 — subject to approvals — leaving regulatory uncertainty hanging over the deal.
DASH Earnings Also Warrant Buying the Stock
Also on Thursday, DASH reported its fiscal Q3 results, offering another reason to consider loading up on its shares.
Excluding Deliveroo, the Nasdaq-listed food delivery giant saw its revenue come in up 23% year-over-year, reinforcing that acquisitions alone aren’t driving growth. Net income also nearly doubled to $466 million.
Crucially, U.S. grocery and retail marketplace spending grew at more than twice the pace of restaurant spending. That gives DoorDash an expanding business to build on while awaiting Instacart approval, and supports the strategic logic of investing further in groceries.
DoorDash shares are now poised to challenge their 20-day moving average (MA), with a decisive break above $186 expected to accelerate momentum in the near term.
Wall Street’s Consensus View on DoorDash
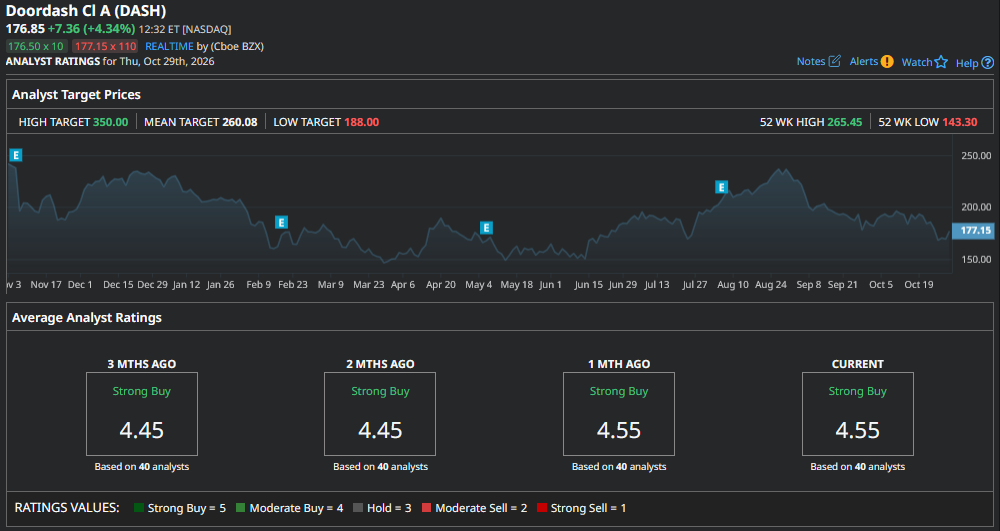
Wall Street analysts also recommend sticking with DASH stock heading into 2027.
According to Barchart, the consensus rating on DoorDash sits at “Moderate Buy” as of writing, with the mean price target of about $260 indicating potential upside of roughly 50% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.