


JFE Systems came into this Q2 2027 earnings print as a valuation puzzle, trading on a P/E below the wider Japanese IT sector while also sitting well under some fair value estimates. The fresh numbers now show basic earnings per share at ¥32.09 on revenue of ¥13,724.11m. This points to a firm still producing profits but working through a margin squeeze after a year where net income turned negative.
The stock closed at ¥1,885 on 29 October and has drifted lower over the past month. That muted reaction contrasts with an earnings profile that, while imperfect, appears more resilient than the recent share price slide suggests.
Like the earnings resilience at JFE Systems but worried about the margin pressure and recent share price drift? Filter for companies that combine profits with sturdier balance sheets in our list of solid balance sheet and fundamentals stocks (23 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥13,724.11m vs. ¥14,447.30m (decline of 5.0%)
- Net Income (Q2 2027 vs Q2 2026): ¥1,007.98m vs. ¥667.35m (increase of 51.0%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥32.09 per share vs. ¥21.25 per share (increase of 51.0%)
- Trailing Net Profit Margin (latest 12 months vs prior 12 months): 7.4% vs. 7.8% (margin compression of 0.4 percentage points)
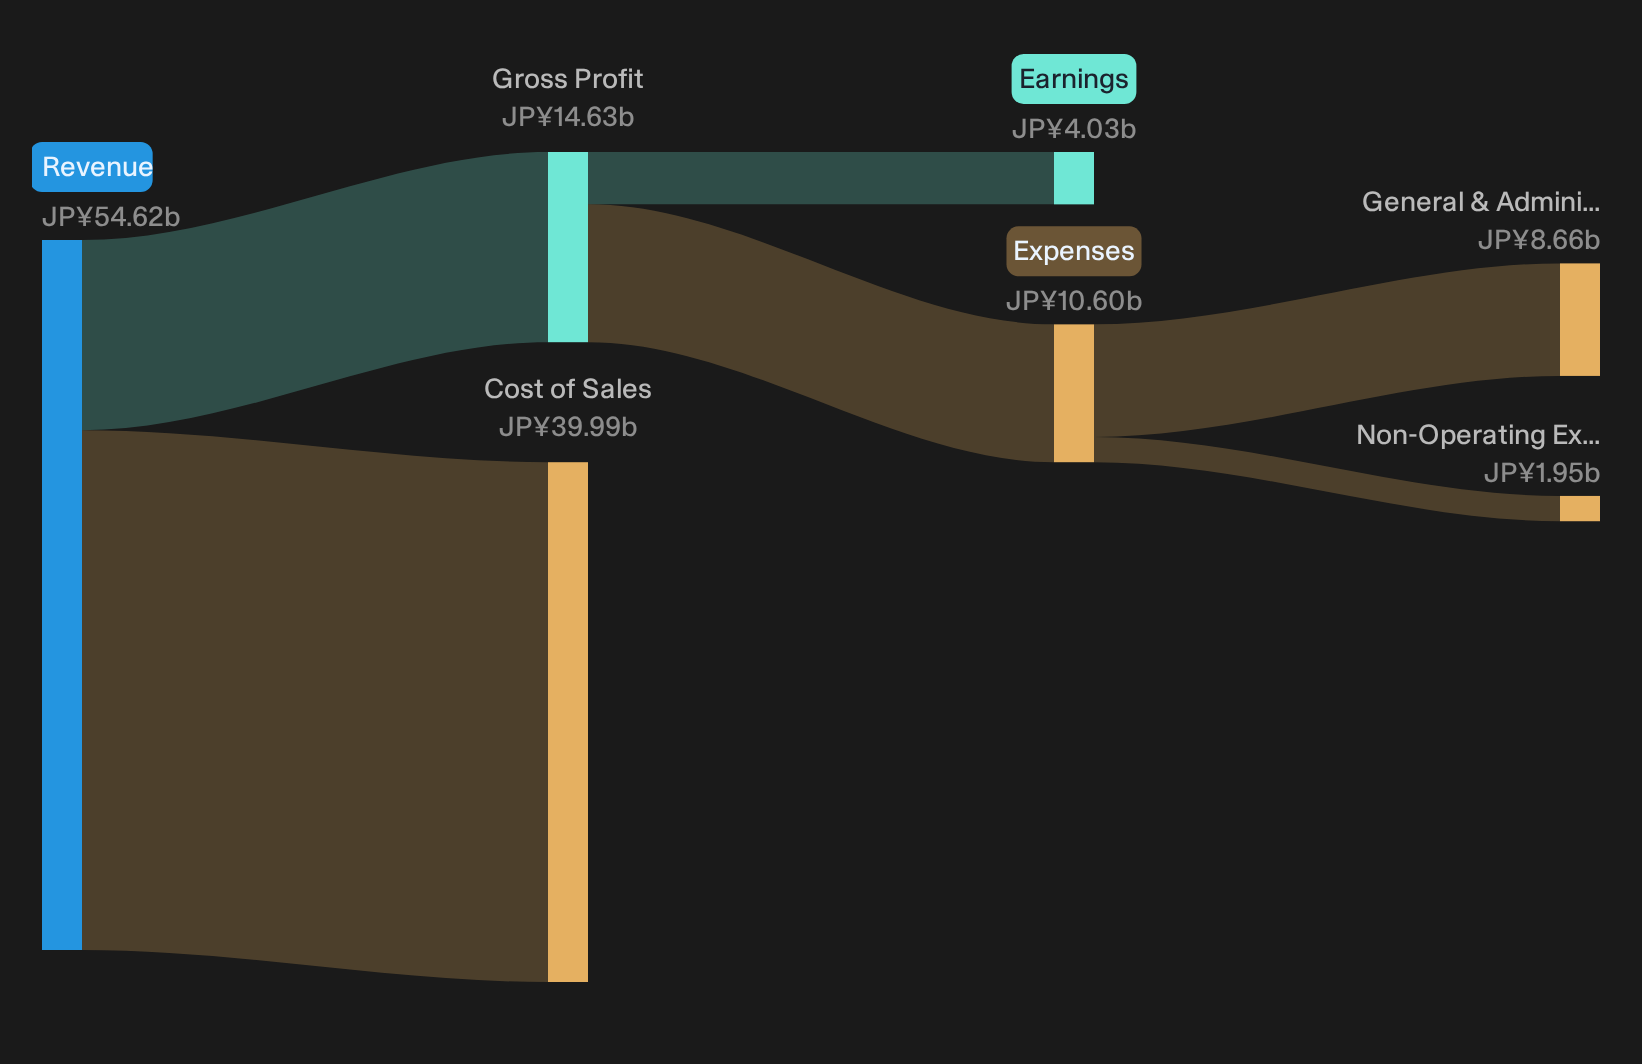
JFE Systems: Earnings Resilience Supports Industrial DX Story
For a business pitched as an industrial digital transformation backbone, JFE Systems shows some support in the numbers. Revenue of ¥13,724.11m is slightly lower than last year, yet net income and basic EPS both rise 51.0%. That mix points to cost work and project execution helping profitability despite softer top line. A trailing net profit margin of 7.4% also still fits a steady IT services profile rather than a distressed one. For investors leaning toward the industrial DX backbone angle, these results keep that story intact, even if not spectacular.
Margin Pressure And Soft Top Line Temper Enthusiasm
The cautious read on JFE Systems also finds backing. Sales have eased 5.0% year on year while the trailing net profit margin edges down from 7.8% to 7.4%. That slippage supports concerns about pricing pressure and wage or delivery costs in project work. The share price, which has drifted lower over 7, 30 and 90 days, lines up with that softer backdrop. Profits are improving this quarter, yet the combination of lower revenue and slightly thinner margins keeps alive the risk that earnings quality could come under strain if demand weakens further.
After a quarter where JFE Systems lifted earnings on a softer top line and faces a history of unstable dividends, it is worth asking whether margin slippage and payout volatility are early signs of deeper structural issues. Review the independent risk analysis for JFE Systems which shows 1 important warning sign to see whether this is just surface noise or part of a broader risk pattern.Hunt Quiet Disconnects In Plain Sight
JFE Systems just showed how earnings resilience and a drifting share price can move out of sync. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 29% below our estimate - supplies specialty electronic materials when conventional components cannot meet tighter space and performance demands.
- Company 2 - 23% below our estimate - sells precision grinding and ceramic products when production lines need higher reliability without redesigning core equipment.
- Company 3 - 35% below our estimate - designs complex air and thermal systems when facilities require stricter environmental control for sensitive operations.
That is three of the list. See every one of the 14 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com