


- Subaru has decided to end petrol vehicle sales in Europe, targeting an all electric lineup from 2028 and running down remaining combustion stock beforehand after assessing the cost of meeting stricter regional emissions rules against its relatively small European presence.
- The move highlights how Subaru is effectively treating Europe as an electrification test bed, concentrating engineering resources on EV compliance where regulation is tightest while keeping capital intensity aligned with its more limited local volumes.
- This report examines how Subaru's investment narrative intersects with this full European EV pivot and the regulatory driven retooling it requires.
Scan how other automakers are repositioning around electrification by comparing Subaru's European pivot with a curated list of 43 power grid technology and infrastructure stocks in the same broader transition story.
What Is Subaru's Investment Narrative?
To own Subaru, you need to believe the group can turn a niche all wheel drive and safety focused brand into an EV relevant automaker without blowing up the economics that support it today. Operations are heavily skewed to autos, with ¥4,668,061m of automotive revenue within a ¥4,821,719m total, so execution on product, pricing and capacity matters far more than peripheral activities. The pivot to an all electric lineup in Europe from 2028 fits that story as a contained experiment in a smaller region, testing compliance and technology where regulation is tight while keeping capital intensity in line with Subaru's limited local volumes.
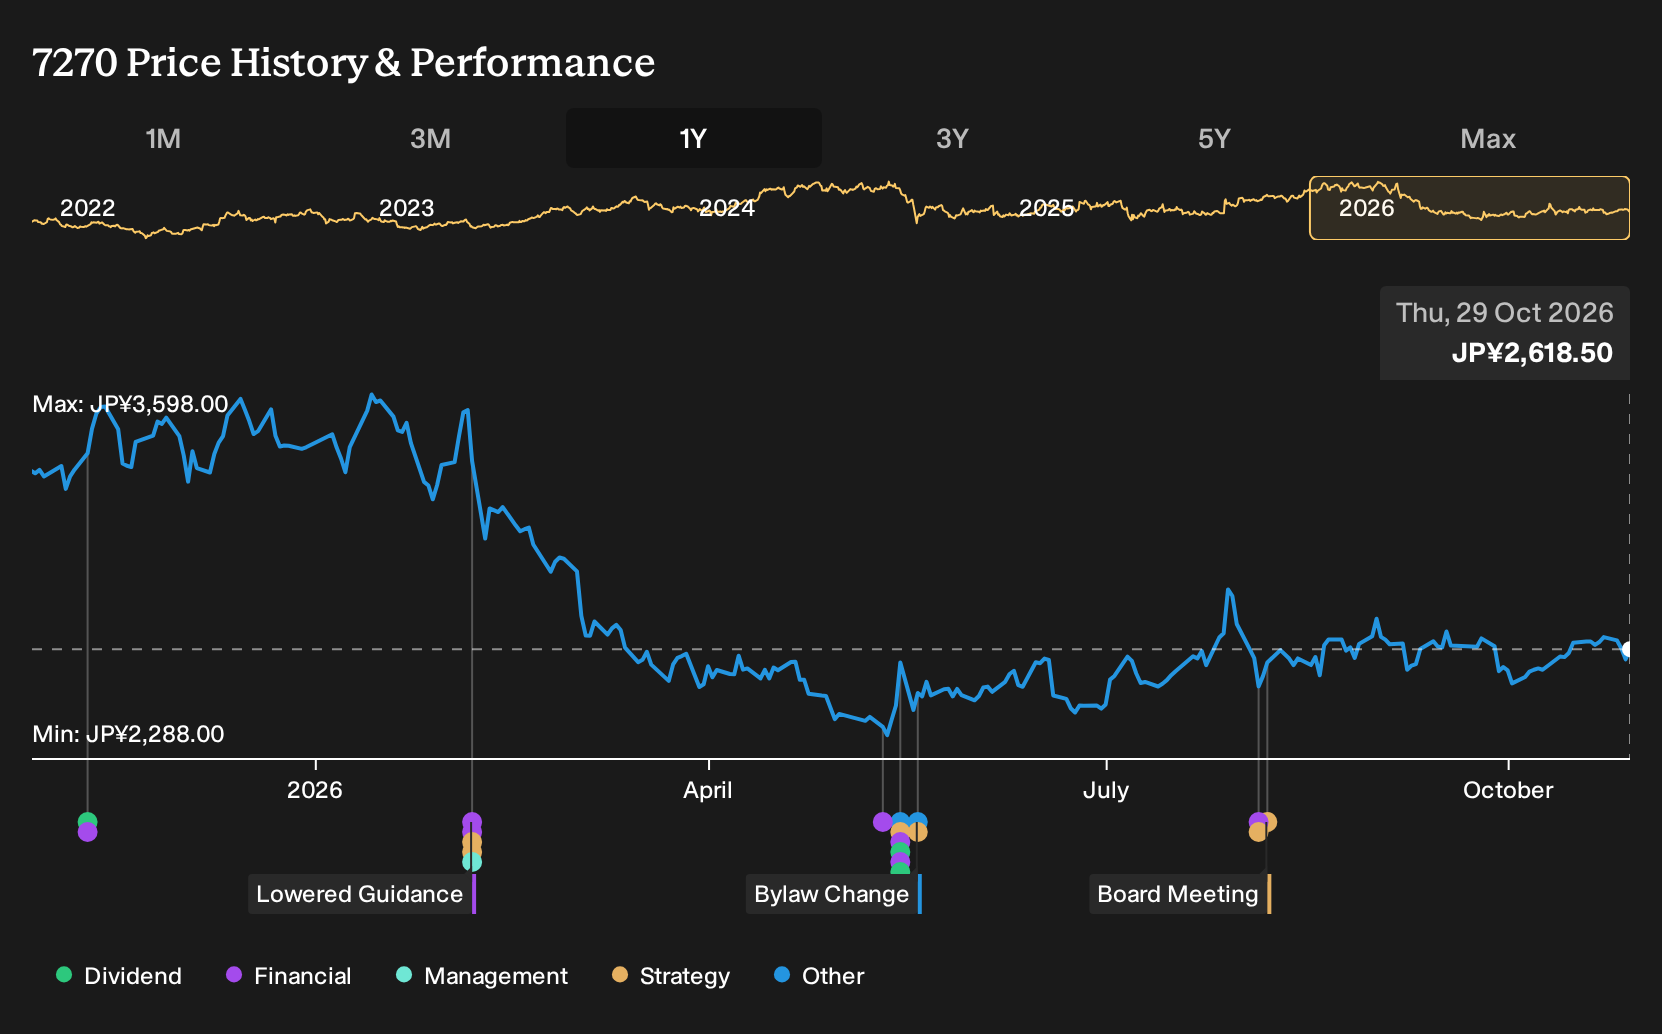
In the short term, the European exit from petrol looks more like a reallocation decision than a core earnings swing factor. The bigger moving pieces are still margin repair, given net profit margins of 1.8% compared with 6.4% a year earlier, and whether management can translate forecast earnings growth of about 20% a year into better return on equity, which currently sits at 3.1%. Valuation also asks for faith, with the stock on a 21.7x P/E versus 16.7x for peers and 13.1x for the wider Asian auto group, while at the same time a 4.43% dividend is not well covered by earnings or free cash flow.
Yet there is one uncomfortable implication of that Europe EV pivot that rarely shows up in the headline numbers...
There's only one way to know the right time to buy, sell or hold Subaru. Head to Simply Wall St's company report for the latest analysis of Subaru's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between ¥2,331 and ¥2,673, so retail opinions on Subaru are already spread even before factoring in the Europe petrol exit. As that EV shift plays out, you are likely to see sharper disagreement on earnings resilience. Use these contrasts to pressure test your own view.
Explore another Subaru fair value estimate, including one that suggests as much as 11% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Subaru research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Subaru. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Subaru's overall financial health at a glance.
Looking For More Investment Ideas Beyond Subaru?
If you want to pressure test your Subaru view against other opportunities, a quick pass through a few focused screens can help you see what else the market is offering on income, value, and balance sheet strength.
- For investors who want income with some quality filters in place, start with a curated set of 30 dividend fortresses that aim to combine yield with resilience.
- If you prefer to concentrate on pricing power and valuation support, compare Subaru with a group of 15 high quality undervalued stocks that currently look more attractively priced on fundamentals.
- For those who care most about financial robustness, run your eye over a list of solid balance sheet and fundamentals (23 results) to see which businesses might better match your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com