


PCA came into this Q2 2027 earnings print with a mixed story. Trailing earnings growth of 30.2% and an 11.5% net profit margin had already pushed the stock to a P/E of 15x, slightly richer than close peers. Yet the share price has drifted over the last week and month, leaving expectations muted.
The fresh quarter delivers a different tension. Basic earnings per share of ¥13.08 and net income of ¥263 million now sit in the shadow of a very large earlier one off gain of ¥887 million that had flattered results. The market reaction is now wrestling with that gap between headline profits and ongoing power.
Like the earnings power at PCA but worried that a one off windfall is clouding the real picture? See the list of solid balance sheet and fundamentals stocks (23 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥4,575 million vs. ¥4,251 million (up about 7.6%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥263 million vs. ¥411 million (down about 36.0%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥13.08 vs. ¥20.50 (fell about 36.2%)
- Trailing 12 Month Net Income (Excl. Extra Items, to Q2 2027 vs. to Q2 2026): ¥2,066 million vs. ¥1,587 million (up about 30.2%)
A big one-off gain lifted PCA’s recent earnings. Ask Charlie what the one-off gain means for PCA.
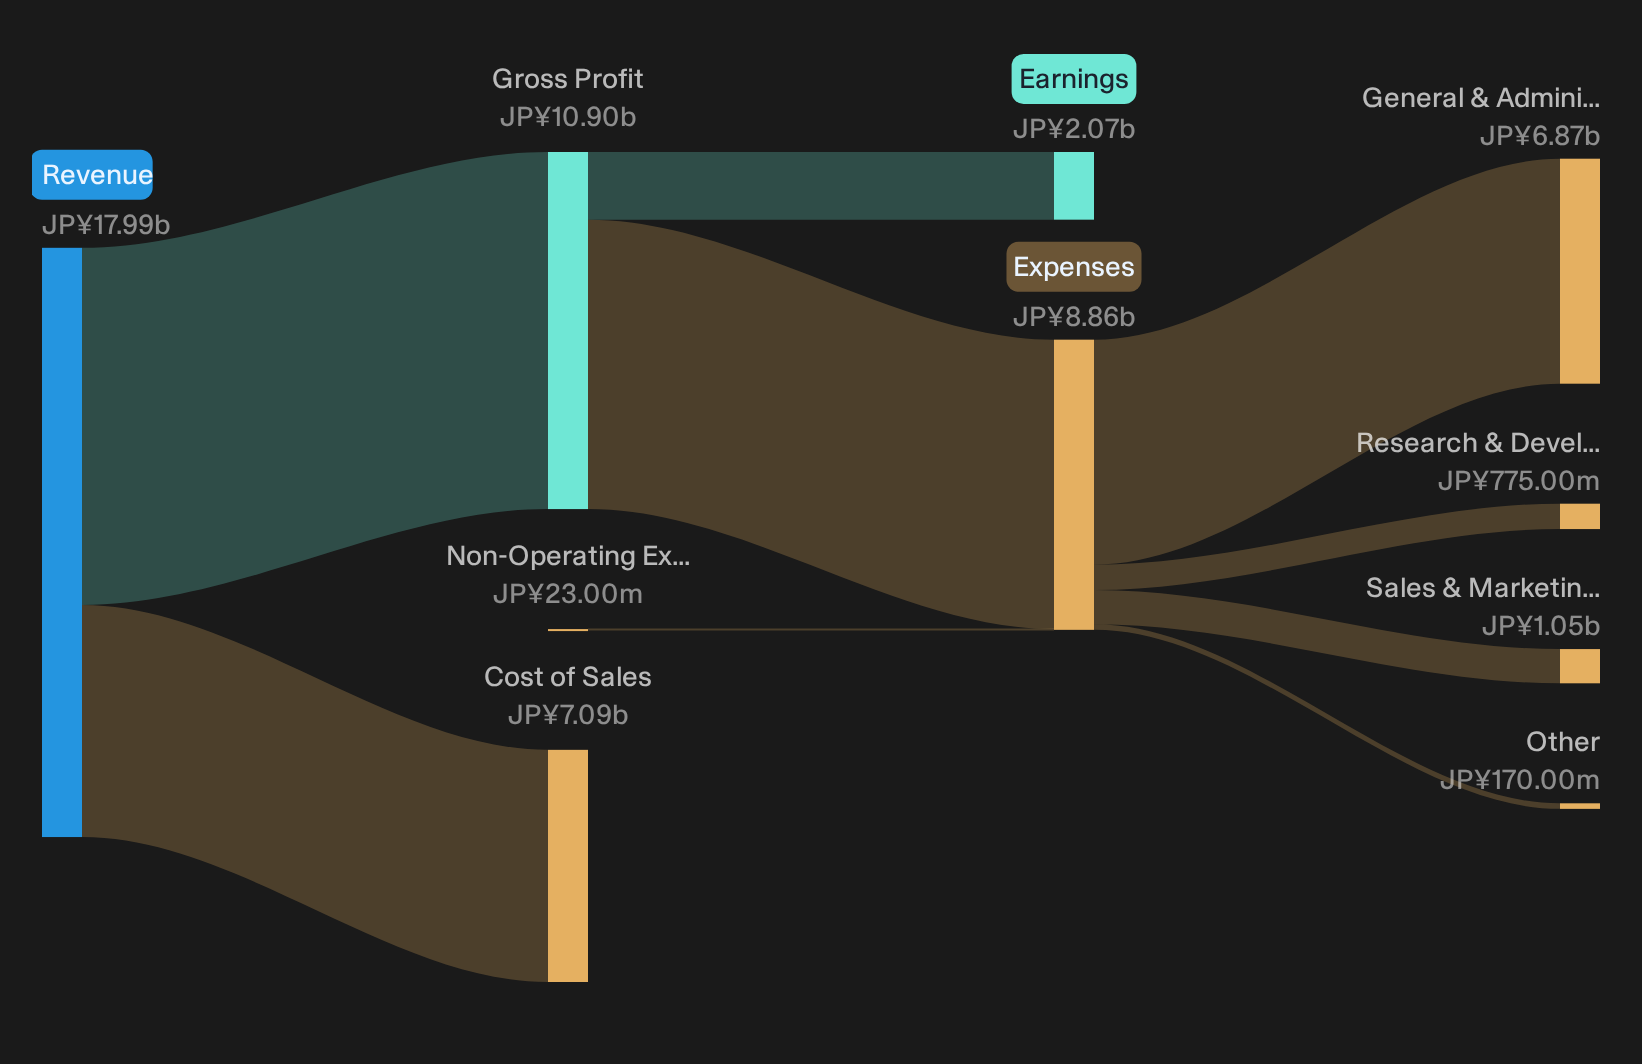
PCA earnings, revenue growth and bullish signals
PCA still gives bulls something to work with. Top line rose from ¥4,251 million to ¥4,575 million, which backs the story of essential back office software finding steady demand. Trailing 12 month net income excluding extras is ¥2,066 million against ¥1,587 million, so underlying profit over the year points upward even though this quarter laps a very large prior one off gain.
Profit pressure, one off gains and bearish angles
The bearish side of the PCA story focuses on earnings quality. Net income excluding extras in Q2 slid from ¥411 million to ¥263 million and basic EPS moved from ¥20.50 to ¥13.08. That strains the image of a simple, smooth earner. Recent share performance, slightly down over 7 and 30 days, suggests investors are still sorting how much of past strength came from repeatable operations rather than that earlier windfall.
After a sharp drop in Q2 earnings and reliance on one off gains, it is fair to ask whether PCA has deeper structural issues hiding in the footnotes. Review our independent risk analysis for PCA which shows 3 important warning signsHunt For Mispriced Earnings Power
PCA reminds you that reported profit and share moves do not always tell the full story. The real opportunity is finding companies that could be undervalued before the market corrects them.
- Company 1 - 43% below our estimate - runs a regional banking platform that folds leasing, cards and energy projects into one customer relationship.
- Company 2 - 47% below our estimate - sells hiring and workflow tools that replace scattered HR software once headcount and data outgrow spreadsheets.
- Company 3 - 30% below our estimate - supplies high precision photomasks that chip designers turn to when new process nodes strain existing tooling.
That is three of the list. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com