


Hokuriku Electrical Construction came into this earnings season priced like a steady utility contractor, not a high growth story, with the stock roughly flat over 3 months and down about 5% over 30 days at ¥1,482. Then Q2 2027 landed with a jolt. Basic earnings per share jumped to ¥62.33 and net income reached ¥1,715m on revenue of ¥18,959m. The market reaction looks cautious on the surface, yet the latest quarter points to a profit engine that appears to be working harder than the recent share price suggests.
Like the earnings strength at Hokuriku Electrical ConstructionLtd but uneasy about a stock that has gone sideways into this report? Compare it with a curated list of contractors and infrastructure plays in our list of solid balance sheet and fundamentals stocks (23 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥18,959m vs. ¥14,636m (up roughly 30%)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,715m vs. ¥627m (up about 2.7x)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥62.33 vs. ¥22.56 (up around 2.8x)
- Trailing 12-Month Net Profit Margin (Q2 2027 vs. prior year): 7.7% vs. 5.6% (higher profitability on recent earnings)
Tired of scrolling through dense tables and raw earnings figures for Hokuriku Electrical ConstructionLtd? See the full financial picture, including a clear view of profitability trends in an easy visual format, in our company report for Hokuriku Electrical ConstructionLtd.
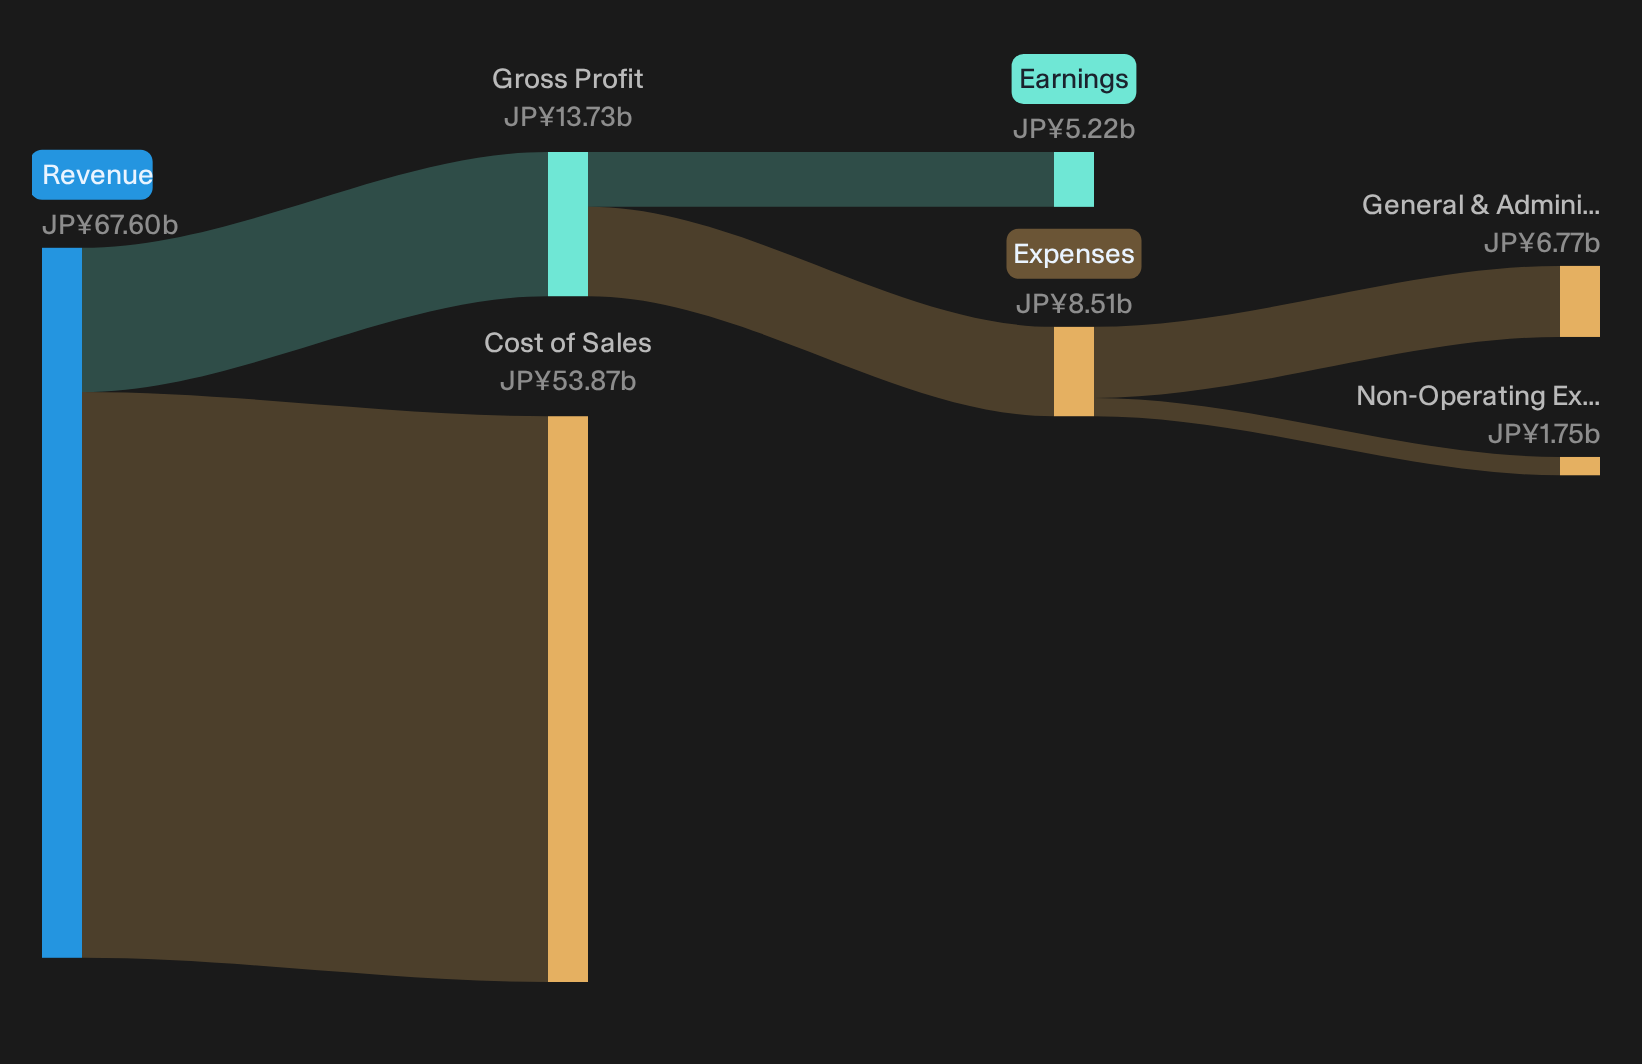
Hokuriku Electrical Construction and the bullish read on Q2
For anyone leaning positive on Hokuriku Electrical Construction, the latest quarter gives that view some real footing. Revenue reached ¥18,959m with net income at ¥1,715m and basic EPS of ¥62.33, while the trailing 12‑month net margin sits at 7.7% versus 5.6% a year earlier. That combination points to a business that is not just adding work but converting a higher share of each yen of sales into profit. This aligns with the idea of a diversified contractor getting good traction across essential infrastructure projects.
Where the Hokuriku Electrical bear story still bites
There is still ammunition for a more cautious stance on Hokuriku Electrical Construction. The share price is roughly flat over 3 months and down about 5% over 30 days despite the earnings jump. This suggests investors are treating this as a potentially cyclical contractor rather than rerating it quickly. Even with a stronger 7.7% trailing net margin, construction remains exposed to project timing, input costs, and bidding pressure, so the concern that profitability can swing with the order mix has not disappeared.
After a dividend that current free cash flow does not fully cover, are you sure this is the only structural weak spot? Review the risk analysis for Hokuriku Electrical ConstructionLtd which shows 1 important warning signHunt For Quiet Disconnects
Hokuriku Electrical ConstructionLtd just showed how earnings strength and a hesitant share price can move in different directions. The real opportunity could sit in stocks that look mispriced before the market pays attention.
- Company 1 - 35% below our estimate - plans and manages complex infrastructure builds for public agencies that outsource long term upkeep and seismic resilience.
- Company 2 - 30% below our estimate - supplies advanced photomasks that chip designers use as they move into tighter geometries and new production nodes.
- Company 3 - 49% below our estimate - sells molding systems that packaging producers use when they upgrade from commodity containers to customized PET bottle designs.
Three companies from the same screener. Open every one of the 15 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com