


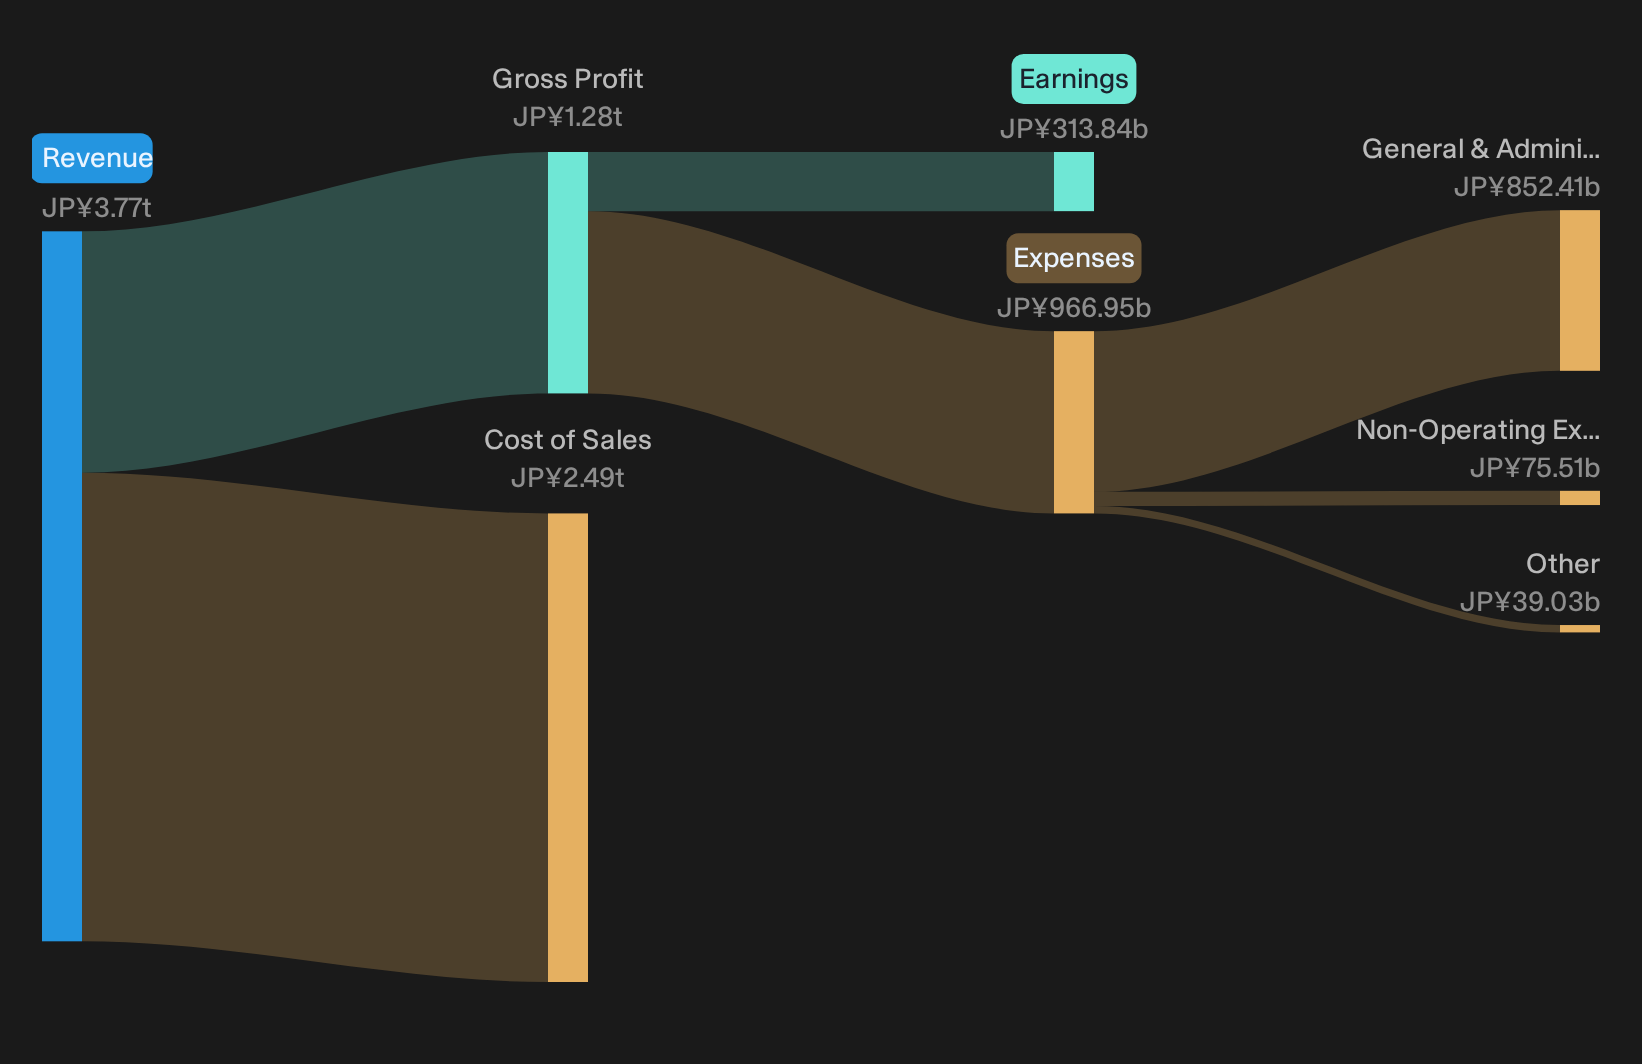
NEC came into this earnings print with a rich 21x P/E and a share price that slipped about 11% over the past week, even as analysts on average still saw upside. Q2 2027 results landed with hard proof that the profit story is real, not just a narrative, with basic earnings per share at ¥50.31 and trailing net income of ¥313.84b anchoring that elevated multiple.
The twist for investors is the gap between price action and profit delivery. The stock looks cautious. The quarterly numbers read confident.
Love NEC’s confirmed earnings power but uneasy about paying a rich 21x P/E while the share price wobbles? Compare this setup with companies that have a stronger mix of valuation support and balance sheet quality in our list of solid balance sheet and fundamentals stocks (23 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥934,083m vs. ¥854,121m (up 9.4%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥66,741m vs. ¥53,520m (up 24.7%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥50.31 vs. ¥40.15 (up 25.3%)
- Trailing 12-Month Net Income Margin (Q2 2027 vs Q2 2026): 8.3% vs. 6.7% (margin improvement of 1.6 percentage points)
NEC just raised guidance after a standout submarine systems quarter. Ask Charlie what NEC’s Petal cable win means for profits.
NEC BluStellar and AI Ambitions Under the Microscope
For the optimistic view, the key question is whether NEC is actually turning BluStellar and AI plans into higher quality earnings.
"Ongoing digital transformation initiatives across public and private sectors continue to feed into NEC’s BluStellar business, where management now cites JPY 705 billion of revenue and a 14.5% non-GAAP operating margin, with a target of JPY 1.3 trillion of BluStellar revenue at a 25% margin by FY March 2031 that could lift group revenue and operating margins."
H1 revenue rising 11.7% and non GAAP operating profit improving by ¥60.8b align with that scaling story. BluStellar revenue growth of 29.5% and Domestic IT Services profit improvement of ¥20.2b show the margin mix tilting toward that ambition rather than away from it.
Hardware Drag, Telecom Risk And NEC Execution Test
The bear story focuses on whether legacy hardware and telecom issues will blunt NEC’s AI and defense progress.
"NEC is counting on rising contributions from AI related and BluStellar style activities. However, the allowance for macro and component risks alongside forecast Telecom Services revenue pressure shows that hardware centric and cyclical parts of the portfolio still matter, and a sharper slowdown in these areas could offset software and AI growth in a way that restrains consolidated revenue, operating profit and future earnings per share."
Management still builds in ¥100b of revenue and ¥30b of non GAAP operating profit downside for components and macro factors. At the same time, H1 showed limited supply disruption and strong Social Infrastructure profit, so the risk remains modeled rather than visible in current income growth.
One Narrative disagrees with today's price. → See where this Narrative says NEC should trade.
Hunt For The Quiet Disconnects
NEC shows how earnings strength and share hesitation can pull in different directions in public markets. The real opportunity sits in stocks that could be mispriced before the crowd catches up.
- Company 1 - 47% below our estimate - builds hiring and workflow tools employers adopt once outdated HR systems strain under headcount and compliance demands.
- Company 2 - 23% below our estimate - supplies precision grinding gear manufacturers adopt when tighter tolerances force upgrades to legacy production lines.
- Company 3 - 39% below our estimate - manages virtual creators brands use when traditional influencer campaigns stall and audiences shift toward avatar entertainment.
Those are three of them. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com