


Yokogawa Bridge Holdings stock has been grinding lower in recent weeks, down about 5% over both the past month and the past quarter, even as fresh Q2 2027 results land on the tape. The new quarter shows revenue of ¥45,974 million and basic earnings per share of ¥47.55, figures that sit inside a bigger story of tightening profitability and valuation pressure. Short term traders are reacting to price swings. Long term investors are weighing a thinner 4.9% net margin against a P/E of 13.6x and asking how much cushion is really left.
Love the steady earnings at Yokogawa Bridge Holdings but concerned about that thinner net margin and valuation cushion? Check out the list of solid balance sheet and fundamentals stocks (23 results) for companies that pair earnings power with sturdier financial footing.
Q2 2027 Earnings Summary
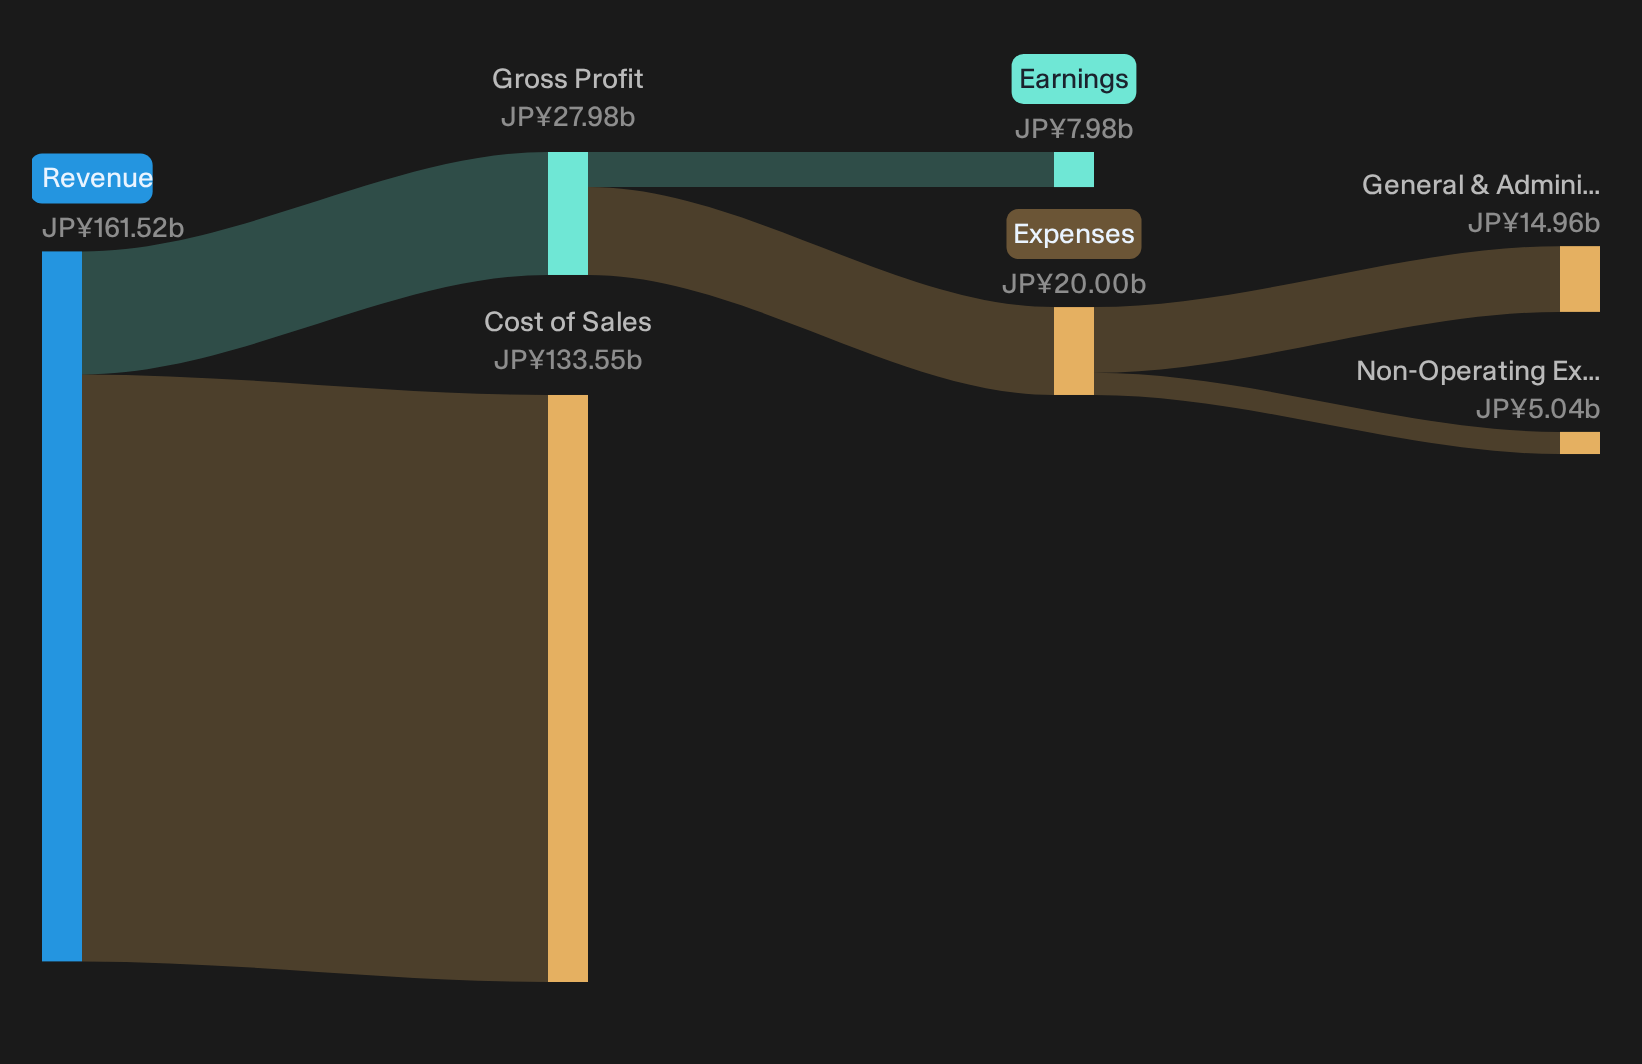
- Revenue (Q2 2027 vs Q2 2026): ¥45,974 million vs. ¥36,078 million (higher year on year)
- Net Income (Q2 2027 vs Q2 2026): ¥1,870 million vs. ¥2,259 million (lower year on year)
- Basic EPS (Q2 2027 vs Q2 2026): ¥47.55 per share vs. ¥56.51 per share (lower year on year)
- Net Profit Margin (TTM, Q2 2027 vs TTM, Q2 2026): 4.9% vs. 7.9% (compression in profitability)
Ask Charlie what makes Yokogawa Bridge’s rich valuation worth it.
Yokogawa Bridge bullish story under earnings pressure
For investors who like Yokogawa Bridge as a steady infrastructure backbone with some tech-linked exposure, the top line gives partial support. Q2 2027 revenue of ¥45,974 million sits above the prior year period, which hints that demand for bridges, system buildings and advanced structures is holding up. That fits a narrative of diversified project flow across public works and industrial facilities. Even so, thinner profitability means this is more about volume resilience than a clean quality upgrade in the earnings mix.
Profit squeeze reinforces near term caution
The bearish angle gets more backing from the latest profitability trends. Net income slipped from ¥2,259 million in Q2 2026 to ¥1,870 million and basic EPS moved from ¥56.51 to ¥47.55. The trailing net margin narrowed from 7.9% to 4.9%, which points to cost pressure or tougher pricing on contracts. With the share price drifting lower over 7, 30 and 90 days, the market reaction looks consistent with investors treating Yokogawa Bridge as facing real pressure on earnings quality.
Reveal where the surface looks calm but the multi year path for Yokogawa Bridge Holdings could split, and see what the street is actually modeling for the next few fiscal years through the analyst estimates for Yokogawa Bridge Holdings.Hunt Quiet Dislocations Before Consensus
Yokogawa Bridge Holdings shows how a softer margin and drifting share price can draw focus to short term movements. The real opportunity is spotting stocks that could be undervalued before pricing adjusts.
- Company 1 - 32% below our estimate - let merchants adopt emerging digital payment choices as consumer behavior evolves.
- Company 2 - 40% below our estimate - sell low code workflow tools once email and spreadsheets cannot track daily work.
- Company 3 - 30% below our estimate - supply advanced photomasks chip designers use when shifting from legacy nodes to complex geometries.
Three companies from the same screener. Open all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com