


Yurtec just posted its Q2 2027 scorecard and the headline is simple. Profitability did the heavy lifting while the share price barely flinched. The stock closed at ¥2,564 on 29 October, only modestly above recent levels, even though basic earnings per share reached ¥53.56 on revenue of ¥68,329m.
The market is trading this like a routine quarter. The numbers say something else. Net income of ¥3,680m points to a construction contractor quietly grinding out thicker profitability, which may matter far more for long term value than today’s muted price reaction.
Like the way Yurtec is quietly producing earnings at today’s price but want a yardstick for other contractors turning solid profits without a big market reaction? Compare this quarter with our 26 resilient stocks with low risk scores to see how it stacks up on resilience and fundamental strength.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥68,329m vs. ¥62,798m (up about 9%)
- Net Income (Q2 2027 vs. Q2 2026): ¥3,680m vs. ¥2,392m (up about 54%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥53.56 vs. ¥34.83 (up about 54%)
- Trailing 12 Month Net Income (Q2 2027 TTM vs. Q2 2026 TTM): ¥12,886m vs. ¥12,304m (up about 5%)
Ask Charlie what Yurtec’s richer P/E really prices in.
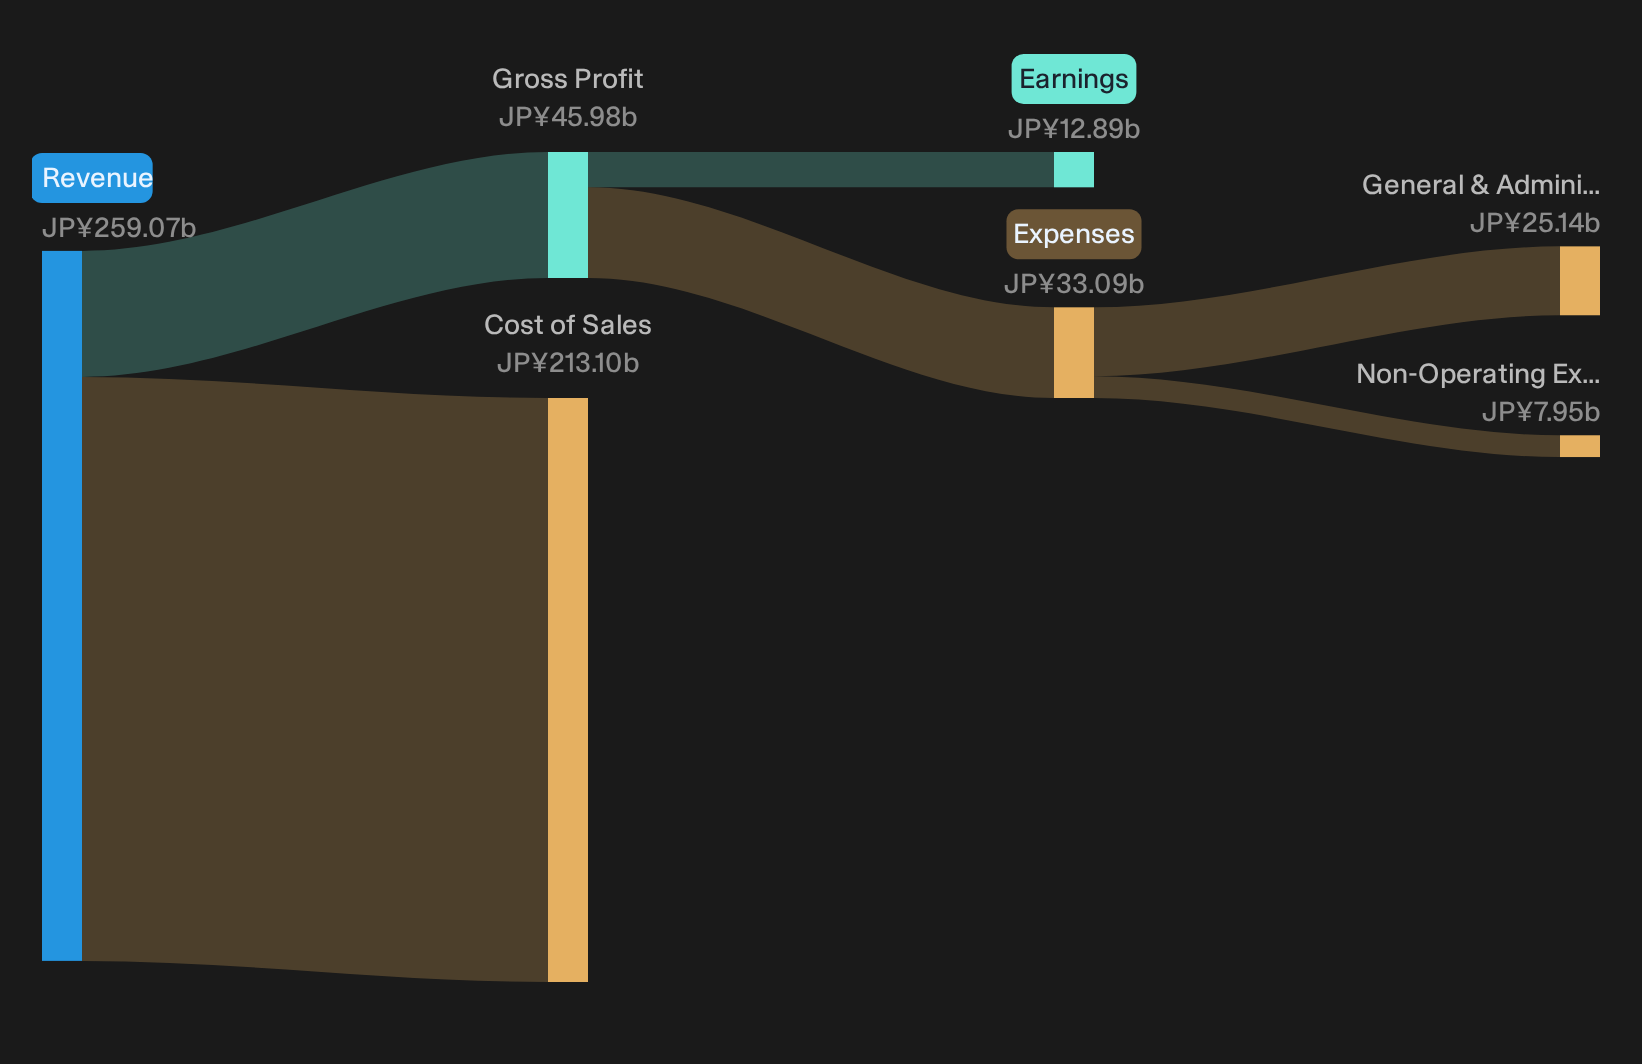
Yurtec earnings power backs steady-infrastructure story
For a business framed as a “steady infrastructure backbone”, Yurtec’s latest quarter lines up cleanly with that story. Revenue of ¥68,329m and net income of ¥3,680m both sit above the prior year period, and basic EPS moved in the same direction. Trailing 12 month profit of ¥12,886m also edges ahead of the earlier tally. That pattern fits a contractor built on ongoing facility work rather than one-off windfalls. The new share buyback authorization adds another signal that management sees the balance sheet as strong enough to return cash.
Where the Yurtec bear case still bites
Even with these solid figures, the bear case does not disappear. Revenue is ahead of last year, yet the move in trailing 12 month net income looks far more modest than the quarterly jump. That can raise questions about how repeatable the latest margin profile is in a project based business. The share price reaction has been muted, which suggests investors still treat Yurtec as a low excitement contractor rather than a re rated earnings story. The buyback supports capital efficiency, but it does not remove project or capex cycle risk.
Are analysts treating Yurtec as a low excitement contractor, or starting to price in a rerated earnings story? Check the consensus price target analysis for Yurtec.Hunt Quiet Earnings Dislocations
Yurtec just showed how solid earnings can sit beside a muted share price. The real opportunity is finding stocks that could be undervalued before the market notices the gap.
- Company 1 - 20% below our estimate - supplies capacitors and power modules that electronics makers adopt when designs need tighter energy density and reliability.
- Company 2 - 23% below our estimate - equips precision manufacturers with grinding tools and ceramics they switch to when tolerances tighten and defects start ruining batches.
- Company 3 - 43% below our estimate - runs a regional banking platform that business clients use when they want lending tied directly to leasing, cards and local services.
Those are three of them. See every one of the 15 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com