


Why Glencore Stock Is Back In Focus After IMARC 2026
Glencore (LSE:GLEN) stepped into the spotlight at the IMARC 2026 conference in Sydney, as management outlined its copper output trends and role in emerging battery recycling supply chains.
Glencore’s recent spotlight on copper and black mass recycling comes after a strong share price return year to date of 32.46%. A 1 year total shareholder return of 50.63% and a 5 year total shareholder return of 93.95% suggest momentum has been building over time.
Scan beyond Glencore and compare its copper and battery recycling story with a curated group of resource producers in the 17 top copper producer stocks to see how the wider opportunity set stacks up.
Copper output is ticking higher and Glencore’s black mass ambition is in the spotlight, yet the share price has already climbed sharply this year. Is that quality fully reflected in today’s valuation?
Most Popular Narrative: 19% Undervalued
Glencore’s most followed valuation storyline anchors fair value at £6.72 per share, compared with a last close of £5.42. This puts the recent copper and recycling focus in the context of a wider earnings and margin debate.
A significant uplift in copper production volumes is expected in the second half of 2025 and beyond, as operational bottlenecks and mine sequencing normalize across key sites. There is a stated pathway to 1 million tonnes of annual copper by 2028 and new low capex, high return brown/greenfield projects in Argentina (MARA, El Pachón) are progressing, supporting sustained, long term revenue and EBITDA growth in alignment with continued global electrification and EV adoption.
See why 126 investors see Glencore as 19% undervalued.
Result: Fair Value of £6.72 (UNDERVALUED)
Still, Glencore’s coal exposure and ongoing regulatory and legal overhangs could quickly challenge the current copper-led optimism if conditions move against the group.
Find out about the key risks to this Glencore narrative.
Another View: Glencore Through The P/E Lens
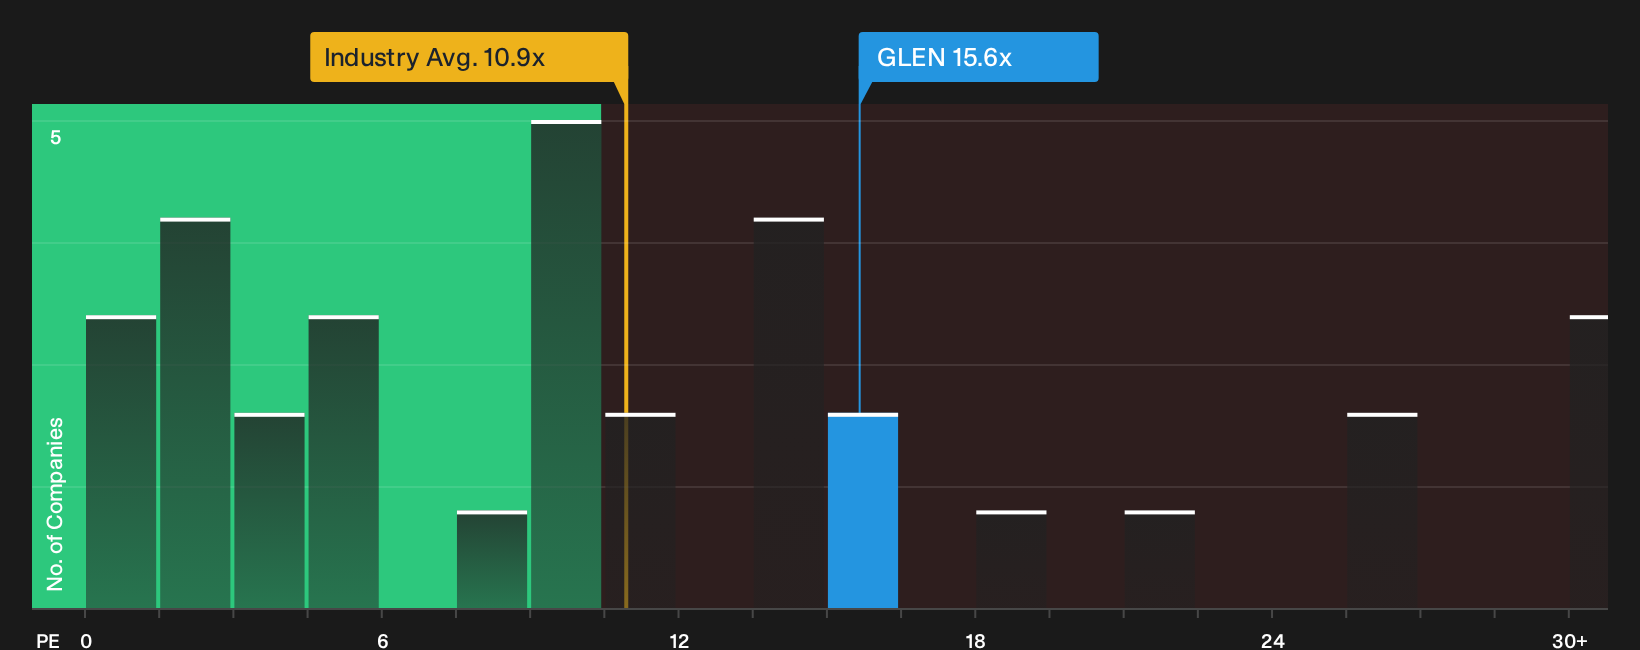
Glencore might look undervalued on the £6.72 fair value narrative. Yet the current P/E of 15.6x tells a tougher story. It trades above the UK metals and mining group at 10.9x, although below peers on 17.2x and under a fair ratio of 18.2x. Is that a safety margin or a warning flag for you?
To see how this earnings multiple could shift as sentiment and results move, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Glencore story points to opportunity, and some parts clearly flag risk, so move quickly and test the data yourself before forming a view. To see both sides laid out in one place, start with 4 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Glencore?
If Glencore has grabbed your attention, do not stop here. Broader opportunities across sectors can help refine your portfolio and highlight alternatives you might otherwise miss.
- Explore additional potential by reviewing a 5 high quality undiscovered gems that couples strong fundamentals with lower market attention.
- Consider portfolio resilience by scanning a list of solid balance sheet and fundamentals (10 results) focused on cash rich businesses with healthier leverage profiles.
- Manage risk by comparing a 5 resilient stocks with low risk scores that screens for steadier earnings, lower volatility, and more predictable balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com