


SM Energy has delivered a striking share price run in 2026, which naturally raises a question for anyone looking at the stock today. With the move already on the board, the key issue is how well the current price lines up with what the business earns.
- The stock is up 106.8% year to date, which puts a lot of weight on the question of whether the current earnings profile can support that kind of rerating.
- Recent coverage highlighting SM Energy's multi basin shale footprint and past revenue growth record may support expectations for what future profit and cash generation could look like.
- The analysts covering SM Energy have run their own numbers. See what analysts think SM Energy's shares could be worth.
The issue now is whether SM Energy's recent share price level is justified by its earnings when measured against the Fair Ratio benchmark.
If you are weighing SM Energy after such a strong year to date, it can also help to scan a wider field of stocks that pass the same basic quality filters using 26 high quality undervalued stocks
Is SM Energy Still Cheap on Earnings?
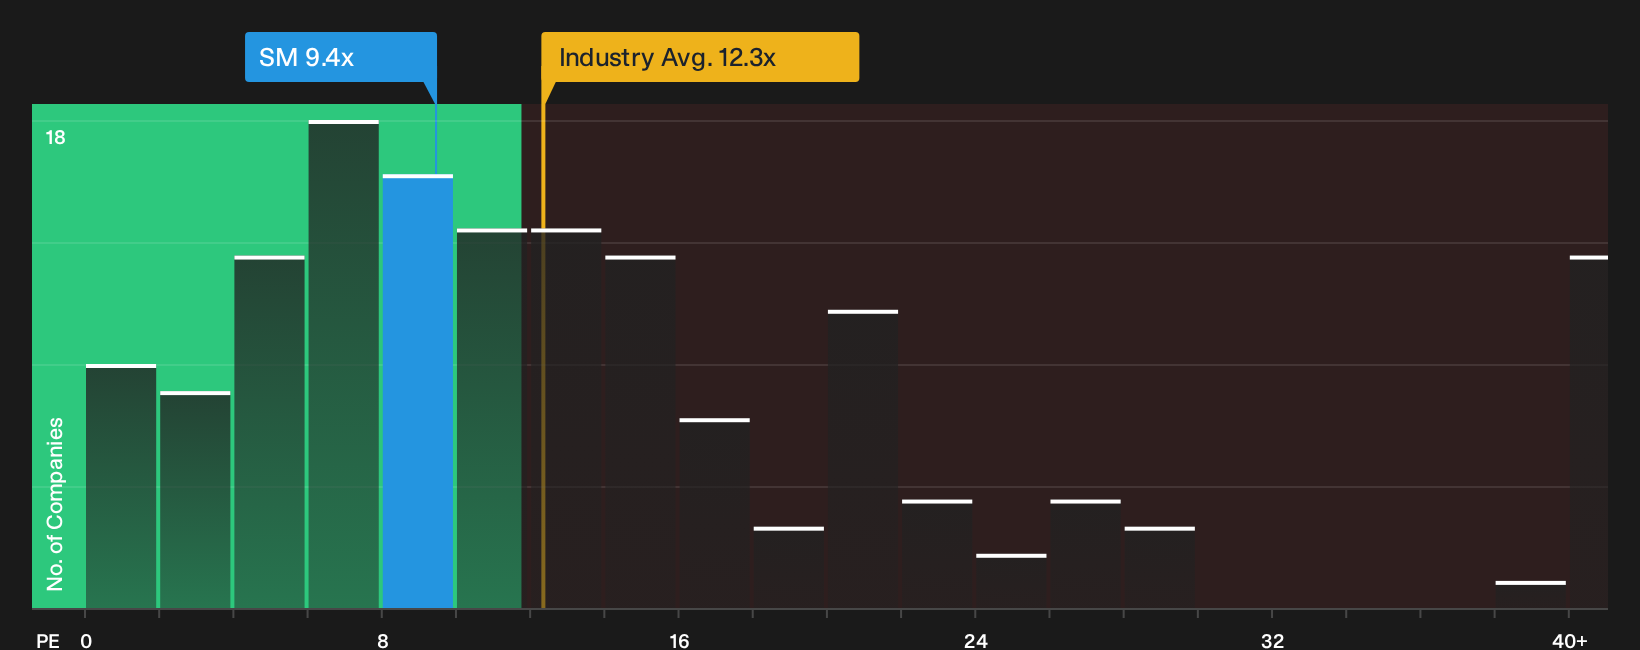
The P/E ratio works reasonably well for SM Energy because earnings remain a primary focus for how this kind of producer is valued. On current numbers, the stock trades on roughly 9.4x earnings, which is lower than the Oil and Gas sector average of about 12.3x and well below the broader peer group on roughly 34.6x. That simple comparison points to investors paying less for each dollar of SM Energy’s profit than for many similar businesses.
On a Fair Ratio basis, which looks at the multiple you might expect given SM Energy’s growth profile, margins, size and risk, the present 9.4x level screens on the cheap side. Recent coverage pointing to multi basin shale exposure and past revenue momentum helps explain why some investors may see that gap as a potential opportunity rather than a warning signal. Because the stock has already logged strong recent performance, the key judgment is whether those earnings and assets justify a P/E discount of this size over the longer run. Explore the numbers behind SM Energy's P/E valuation.
The SM Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for SM Energy, by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Each scenario links a fair value estimate to a clear story about SM Energy's possible catalysts and key risks, so you can track over time which version seems to be unfolding in the real world through the Community page.
Community views on SM Energy are split between investors who see a discounted cash machine in the making and others who think a rich multiple already bakes in the good news.
Bull case: 14% undervalued
"Operational changes such as 4 mile laterals, simul frac, gas powered frac fleets, remote frac and company controlled sand supply in the Uinta Basin have more than doubled completion pace and removed over US$1 million per well from drilling and completion costs..."
Discover why this Narrative puts SM Energy at 14% undervalued.
Bear case: 13% overvalued
"Even after strong free cash flow generation and an 80 or 20 capital return framework that includes dividends and buybacks, the stock’s roughly 49.1x P/E relative to a cited 13.0x industry average, coupled with insider share sales and trimmed analyst targets, suggests that if operational delivery simply tracks guidance rather than outperforms it, valuation compression could weigh on future total return for shareholders..."
Explore why this Narrative puts SM Energy at 13% overvalued.
SM Energy’s price is only one clue in the bigger decision
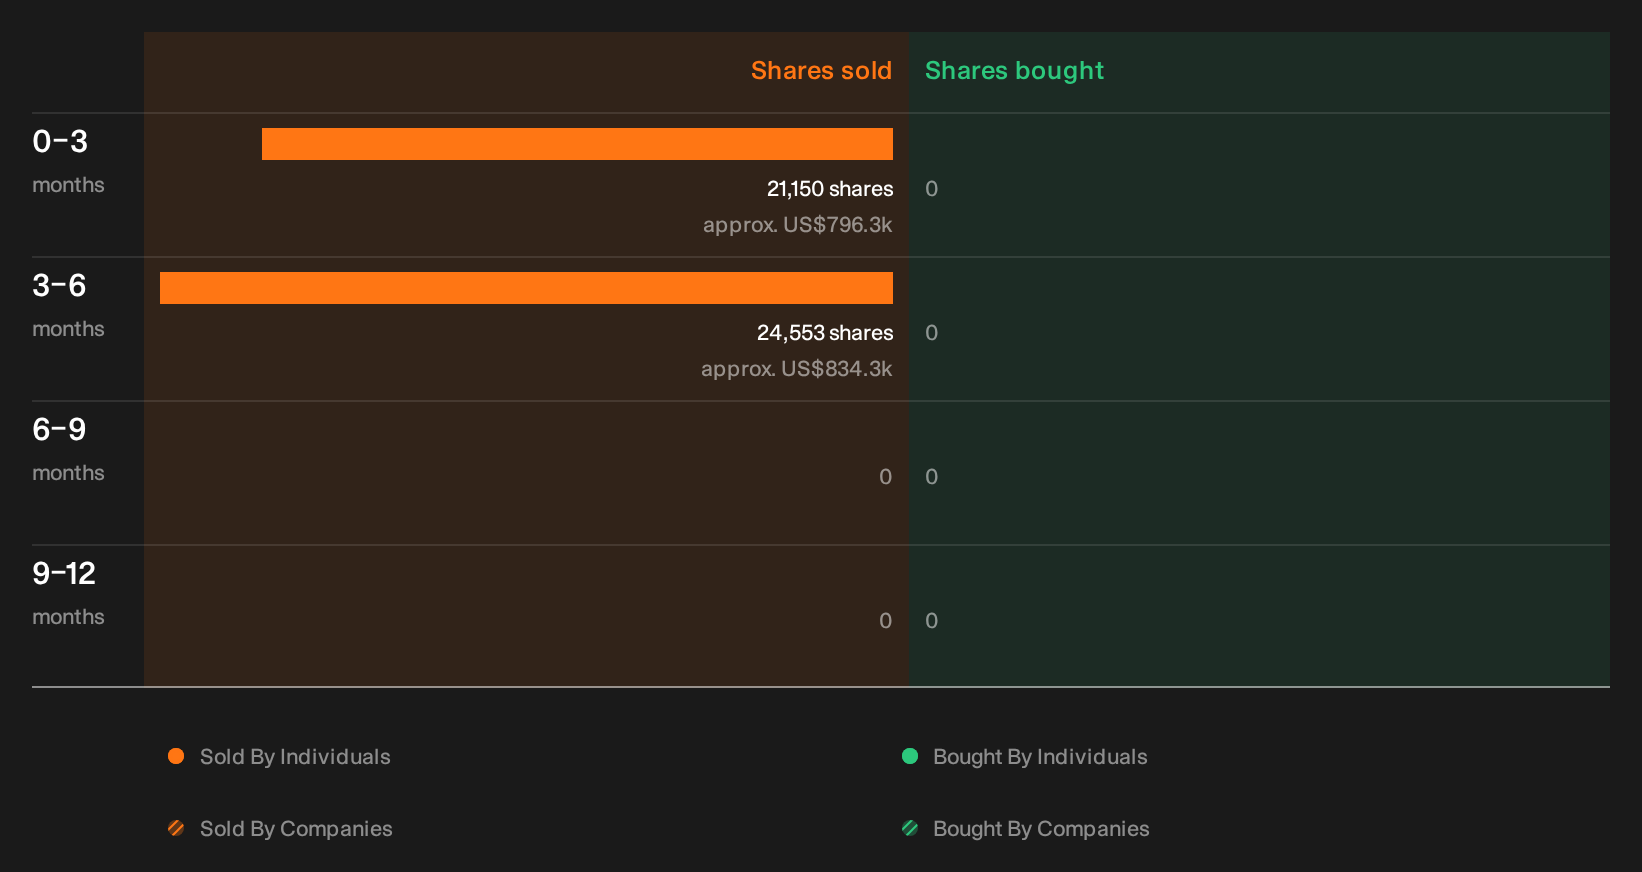
Before making any call on SM Energy, it is worth checking what recent trades by directors and key executives might be signalling about their own conviction, who has been selling, how much, and why. See the recent insider selling flagged for SM Energy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com