


Future entered Q3 2026 earnings with a reputation as a high quality compounder in Japanese IT, priced on a mid-teens P/E and trading slightly below one fair value estimate. The stock closed today at ¥2,428, barely changed over the past week, yet the quarter just reported quietly reshapes the story.
The key headline is profit squeeze. Revenue for Q3 was ¥20,119m, broadly in line with recent quarters, while basic EPS landed at ¥29.99, below both Q2 and last year’s Q4 peak. The market’s muted one day move masks a simple question for holders: How much profit pressure is acceptable for this growth profile?
Impressed by Future’s reputation as a high quality compounder but uneasy about the recent profit squeeze in Q3? Benchmark it against peers with stronger earnings resilience using our list of solid balance sheet and fundamentals stocks (23 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): ¥20,119m vs. ¥19,637m (up about 2.5%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): ¥2,661m vs. ¥3,346m (down about 20.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥29.99 vs. ¥37.73 (down about 20.5%)
- Trailing 12 month Net Profit Margin (Q3 2026 vs. prior year): 14.7% vs. 14.0% (modest margin improvement over the year)
Future’s profits are growing faster than the wider market. Ask Charlie what keeps Future’s faster earnings growth going.
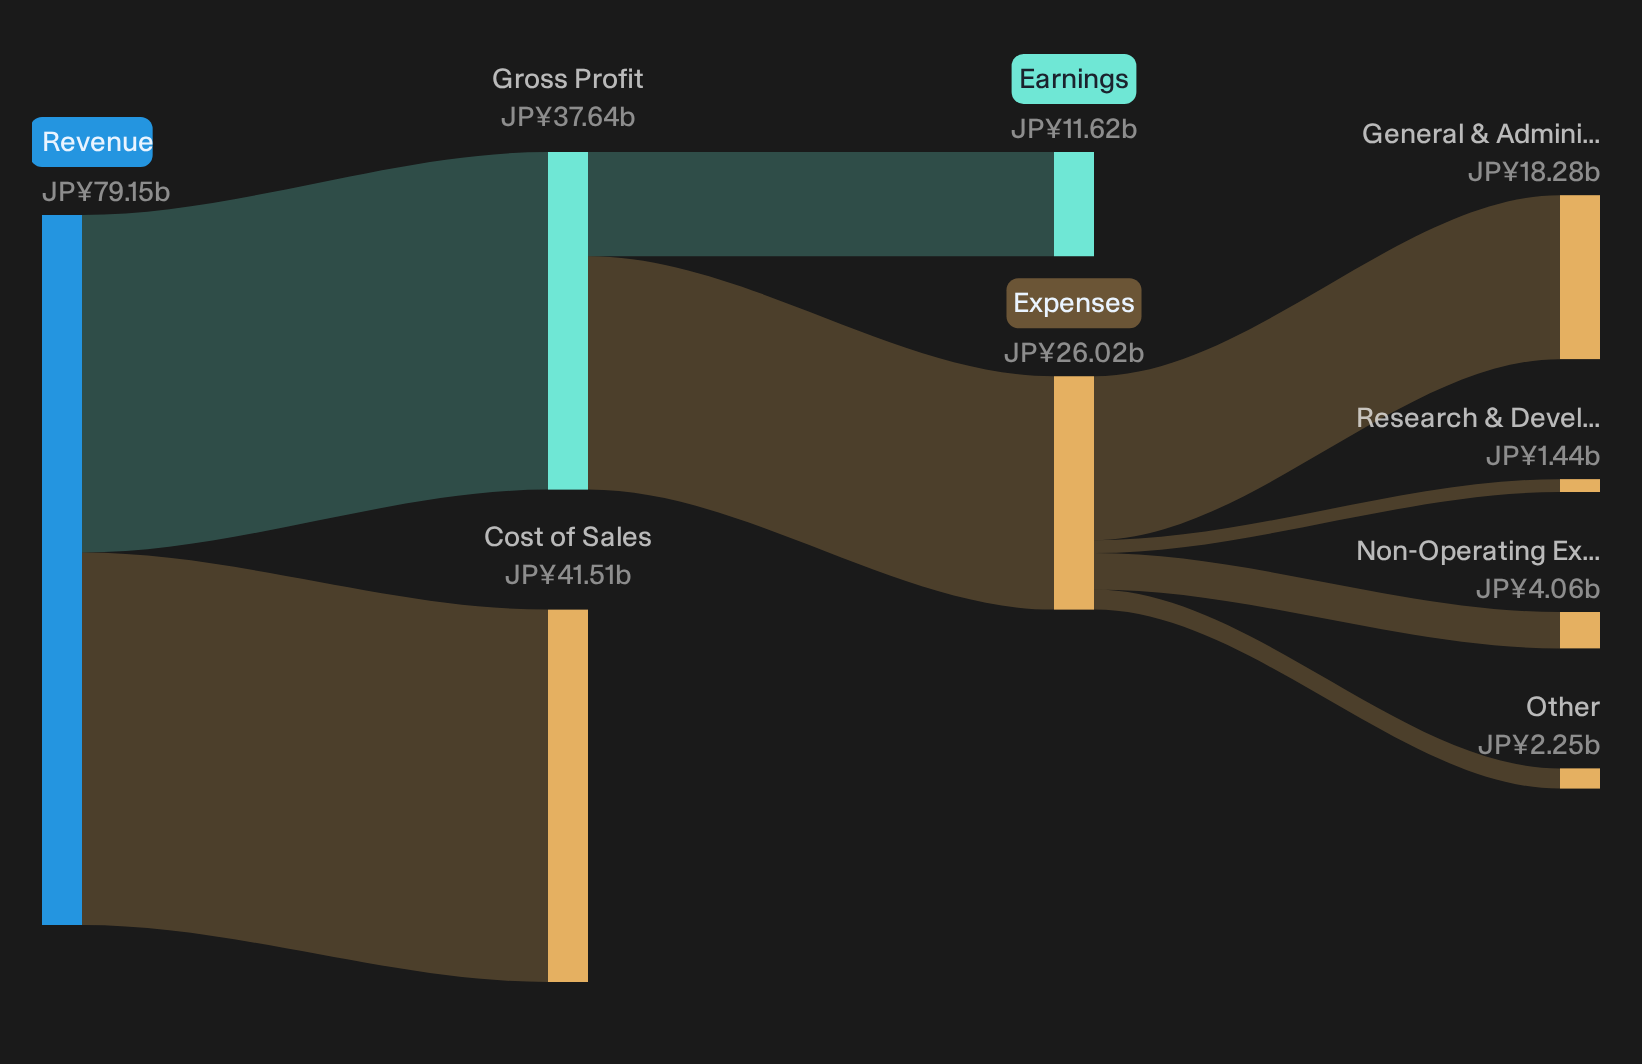
Future bullish story meets softer earnings reality
Future still looks like a solid IT consulting and digital services platform, but the latest quarter asks for more patience from optimists. Revenue of ¥20,119m is only modestly above the prior year, which keeps the digital transformation story alive but not turbocharged. A trailing 12 month net margin of 14.7% versus 14.0% a year earlier hints that the broader franchise can still earn well when projects line up cleanly, even if this single quarter feels like a step back on profit.
Profit squeeze sharpens the cautious Future thesis
Concern sits squarely on earnings quality. Net income excluding extra items fell to ¥2,661m from ¥3,346m and basic EPS dropped to ¥29.99 from ¥37.73, a slide of about 20.5%. For a consulting and digital services company that is often framed as a reliable compounder, that kind of profit compression matters. Revenue barely moved while earnings slipped, which feeds worries about pricing power, utilisation or cost pressure, even though the trailing margin line suggests the broader balance sheet is not flashing acute stress right now.
With profits under pressure while the trailing 12 month margin still looks solid, the real question is whether Future’s cash, debt and working capital can comfortably support this earnings profile. Check the full solvency breakdown in our financial health analysis of Future stock.Hunt Quietly Mispriced Cash Generators
Future just reminded investors that a steady share price can coincide with real earnings pressure. The real opportunity is identifying potentially mispriced cash generators before markets fully recognize their resilience.
- Company 1 - 35% below our estimate - designs and maintains climate and utility systems for hospitals, factories and data centers when uptime becomes non negotiable.
- Company 2 - 20% below our estimate - supplies capacitors and power modules that electronics makers adopt when they demand greater performance from limited board space.
- Company 3 - 47% below our estimate - builds hiring and workflow platforms employers adopt once scattered HR tools fail to scale with compliance needs.
That is three of the list. See every one of the 15 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com