


- Mitsubishi Corporation and Hudbay Minerals have approved the final investment decision for the Copper World project in the U.S., with Mitsubishi holding a 30% joint venture stake and contributing to a funding plan that includes equity, a precious metals stream and project-level debt.
- The Copper World commitment gives Mitsubishi another long life copper exposure linked to a U.S. based asset, adding a sizeable, capital intensive project to its portfolio that will test execution, cost control and long term commodity price resilience.
- This analysis reviews how Mitsubishi's investment narrative intersects with the Copper World joint venture funding plan and capital commitments.
Mitsubishi Investment Narrative Recap
Mitsubishi asks you to believe that a sprawling trading house can keep compounding through selective resource exposure, energy transition projects and steadier food and consumer businesses, even with earnings swings from commodities. The Copper World decision fits that story but does not change the near term focus on cash generation, capital discipline and portfolio reshaping across LNG, metals and consumer supply chains.
The biggest short term swing factor remains commodity price direction, especially for coal, iron ore and copper linked units, given their impact on operating cash flow and net income. Execution risk on large, capital intensive projects such as Copper World also matters, since cost overruns or delays could strain returns and investor confidence.
The Copper World funding plan, which combines Mitsubishi’s ¥600b equivalent initial stake, future pro rata equity of up to US$423m and modest project level debt, aligns with the group’s push to recycle capital into long life resource assets while keeping leverage in check. It gives the conglomerate a defined copper growth pipeline but also front loads capital commitments into a cyclical area.
For you as a shareholder, the interest is how this interacts with existing catalysts such as earnings growth, portfolio optimization and share buybacks. Copper World adds execution and cost control risk on top of already cyclical resource exposure, yet it also creates an operational milestone around first production in 2029 that could influence how investors weigh Mitsubishi against other diversified trading and resources stocks.
How Copper World Sits Inside The Mitsubishi Numbers
Mitsubishi's narrative projects ¥22,926.6b revenue and ¥1,164.2b earnings by 2029. That path relies on 4.9% yearly revenue growth and an earnings increase of about ¥268.3b from ¥895.9b today.
The Copper World joint venture plugs into that framework as one more source of long dated copper exposure that has to coexist with analyst expectations already on the table. Forecasts point to earnings of roughly ¥1.2t by 2029, with profit margins edging up from 4.5% to 5.1%. That leaves limited room for missteps on a project that will require large upfront spending, careful cost control and smooth ramp up to avoid putting extra pressure on the group wide earnings path.
Consensus assumptions tie those 2029 earnings to a P/E of 18.6x, compared with 20.7x today and 10.8x for the GB Trade Distributors peer group. For you as a shareholder, that gap puts a spotlight on whether capital hungry projects such as Copper World help justify a richer multiple or instead add to concerns about conglomerate complexity and exposure to cyclical commodities. Execution on this mine will feed into how much confidence investors place in the idea that Mitsubishi can sustain higher profitability than the sector average.
Revenue expectations of ¥22,926.6b and earnings of ¥1,164.2b also build in the planned 2.72% annual reduction in shares outstanding over the next three years. Copper World funding, with its mix of equity, streaming and project level debt, needs to sit comfortably alongside those buybacks and the wider capital recycling program. If project cash needs start to compete with shareholder returns, the balance between long term copper exposure and near term capital returns becomes a more live question for anyone holding the stock.
Uncover why Mitsubishi's fair value indicates a 7% potential upside to its current price that could narrow quickly.
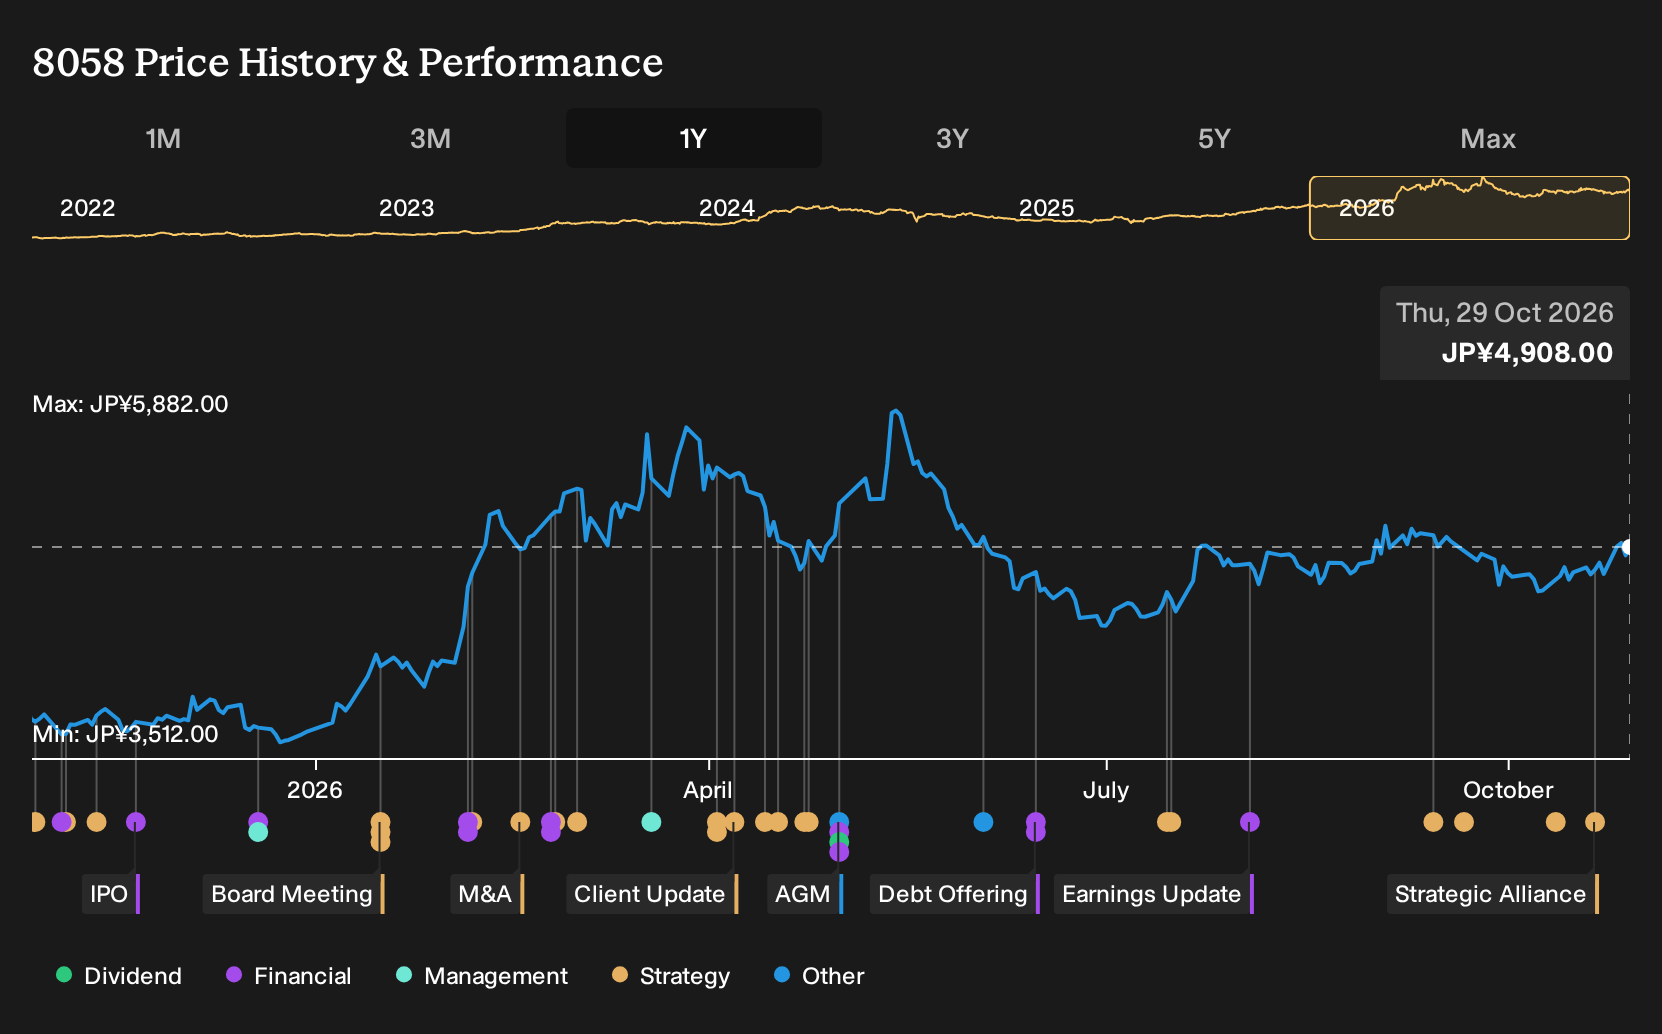
Exploring Other Perspectives
Some of the most optimistic Mitsubishi analysts were already baking in revenue of ¥25,159.3b and earnings of ¥1,338.0b by 2029, assuming stronger execution on LNG, data centers and critical minerals. You now have Copper World in the mix, so those upbeat views may be revisited. Consider how your own expectations compare.
Explore 4 other Mitsubishi fair value estimates, including one that suggests as much as 43% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mitsubishi research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mitsubishi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mitsubishi?
Once you have an initial view on Mitsubishi, it can help to compare that story with other opportunities that share similar qualities, whether you care more about value, balance sheet strength or risk control.
- Prefer rock solid finances and cleaner balance sheets to back up the equity story? Shortlist companies with a list of solid balance sheet and fundamentals (23 results).
- If you want potential value on your side as well as quality fundamentals, scan the 15 high quality undervalued stocks that currently match those filters.
- For readers who put capital preservation first and want smoother ride potential, review the 26 resilient stocks with low risk scores to see which businesses align with that profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com