


- PetroChina reported third quarter 2026 sales of CNY 793,573 million and net income of CNY 51,840 million, with earnings per share from continuing operations at CNY 0.28, and nine month figures also higher than the prior year.
- The most striking detail is that management described third quarter operating results as the best same period level in PetroChina’s history, supported by higher realized crude prices and stronger contributions from refining, chemicals, and new materials.
- The focus now turns to how PetroChina’s investment narrative could shift, given this record third quarter profitability driven by refining strength.
What Is PetroChina's Investment Narrative?
To own PetroChina, you have to buy into a fairly simple idea. This is a large, capital intensive producer and processor of hydrocarbons that lives and dies by execution, cost discipline, and what it can earn on each barrel it pulls, transports, refines, and sells. The latest quarter, with profit attributable to owners up 21.6% and management calling it the best same period in the group’s history, reinforces that the refining, chemicals, and new materials engine can carry a lot of weight when pricing and utilization line up.
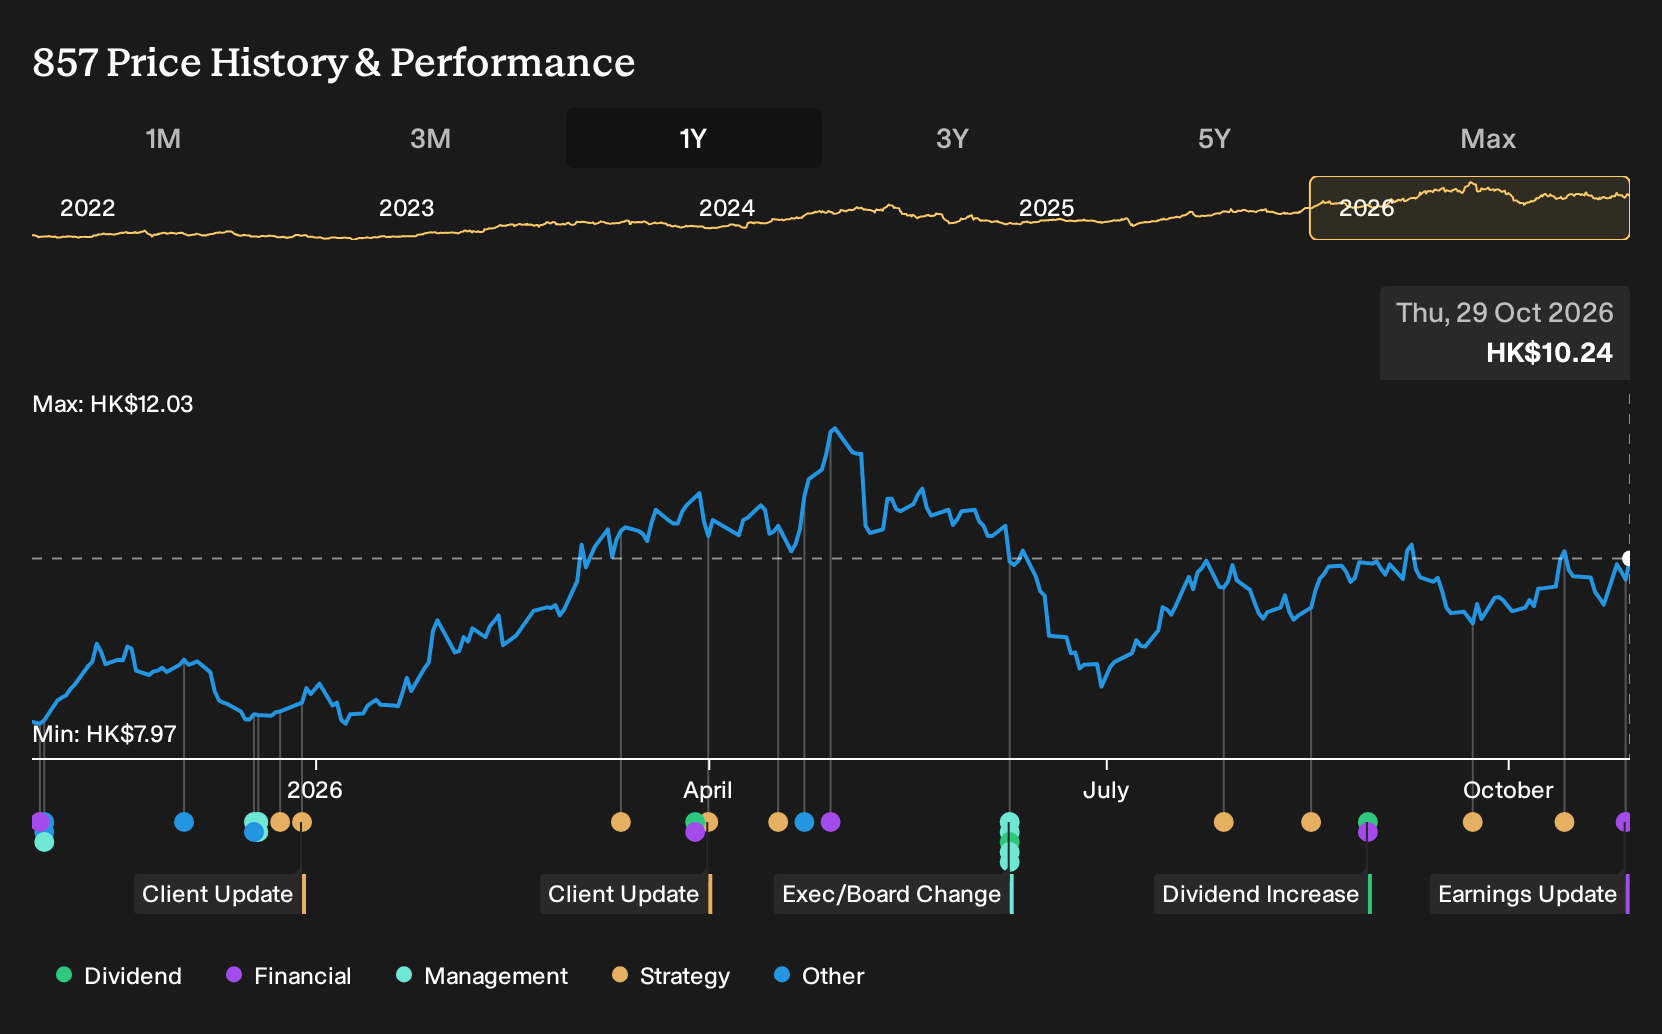
In the short term, the key swing factors remain refining margins, realized oil and gas prices, and how tightly PetroChina manages spending and project timing after cutting nine month capital outlays versus last year. The recent report feeds directly into that story by showing strong earnings while capital spending eased, even as external forecasts still point to declining revenue and profit over the next three years and the dividend track record looks uneven. That mix of strong current execution and cautious forward expectations is what makes PetroChina interesting, but it also sets up a tension around whether this quarter is a high water mark or a new baseline.
Even so, there is a less comfortable angle to PetroChina that only really jumps out once you look at ...
There's only one way to know the right time to buy, sell or hold PetroChina. Head to Simply Wall St's company report for the latest analysis of PetroChina's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value models on PetroChina, yet they already span a wide band from CNY 11.83 to CNY 27.41 per share. Those retail forecasts were set before the latest record quarter and the Iran war backdrop, so treat them as a starting point and compare several community views before forming your own stance.
Explore another PetroChina fair value estimate, including one that suggests as much as 168% upside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PetroChina research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for PetroChina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PetroChina's overall financial health at a glance.
Looking For More Ideas Beyond PetroChina?
If PetroChina has sharpened your focus on where capital intensive businesses can create value, it makes sense to widen the lens and see how other listed companies stack up on fundamentals, balance sheet strength, and income potential using the Simply Wall St Screener.
- For readers who want a shot at mispriced quality, consider scanning a curated pool of companies through our 607 high quality undiscovered gems that pair strong fundamentals with less crowded investor attention.
- If capital preservation matters as much as upside, you can filter for steadier profiles by reviewing a 229 resilient stocks with low risk scores that screens for resilient businesses with lower risk characteristics.
- Income focused investors who value consistency can zero in on payout strength by reviewing a 228 dividend fortresses designed around higher yielding stocks with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com