


- National Bank of Canada recently scheduled a December 4, 2026 strategic update to coincide with its fourth quarter and fiscal 2026 results and released revised supplementary financial information, including restatements dating back to the first quarter of 2024 and more detailed business segment reporting.
- The combination of restated data and richer segment disclosure gives investors a clearer view of how each part of National Bank of Canada contributes to earnings. This can sharpen assessment of execution on costs, capital use and loan growth across the franchise.
- We will look at how National Bank of Canada's investment narrative may shift as management prepares this detailed strategic and financial update.
Scan how National Bank of Canada is reshaping its segments, then line it up against hand-picked banks and lenders on our list of solid balance sheet and fundamentals (6 results) to see who else is tightening execution.
National Bank of Canada Investment Narrative Recap
To own National Bank of Canada, you need to be comfortable with a traditional banking engine that leans heavily on commercial lending, wealth management and disciplined credit costs. The immediate story still hinges on execution of the Canadian Western Bank integration, margin stability around the 2.18% all bank NIM and keeping credit quality supported despite a relatively low 58% allowance for bad loans.
The December 4, 2026 strategic update and refreshed segment data should help you judge that execution more cleanly, but it does not change the core near term swing factors. Capital relief on advanced internal ratings is still delayed to late fiscal 2027 and remains a key risk to capital flexibility and earnings leverage.
The most relevant new disclosure is the enhanced business segment reporting tied to the supplementary financial restatements. For a shareholder, this matters because it lets you see more clearly how Personal and Commercial, Wealth Management, Capital Markets and U.S. Specialty Finance and International are each pulling their weight on profit growth, returns and volatility.
That extra transparency gives you better tools to track the main catalysts already in play. You can line up captured Canadian Western Bank synergies, expanding commercial banking outside Quebec, AI driven efficiency gains and planned share repurchases of up to 10 million shares against segment results, and then decide whether National Bank of Canada is actually delivering on those operational promises.
National Bank of Canada's current analyst story points to revenues of CA$18.0b and earnings of CA$6.0b by 2029, based on forecasts of 7.2% yearly revenue growth and an earnings increase of about CA$1.3b from CA$4.7b today.
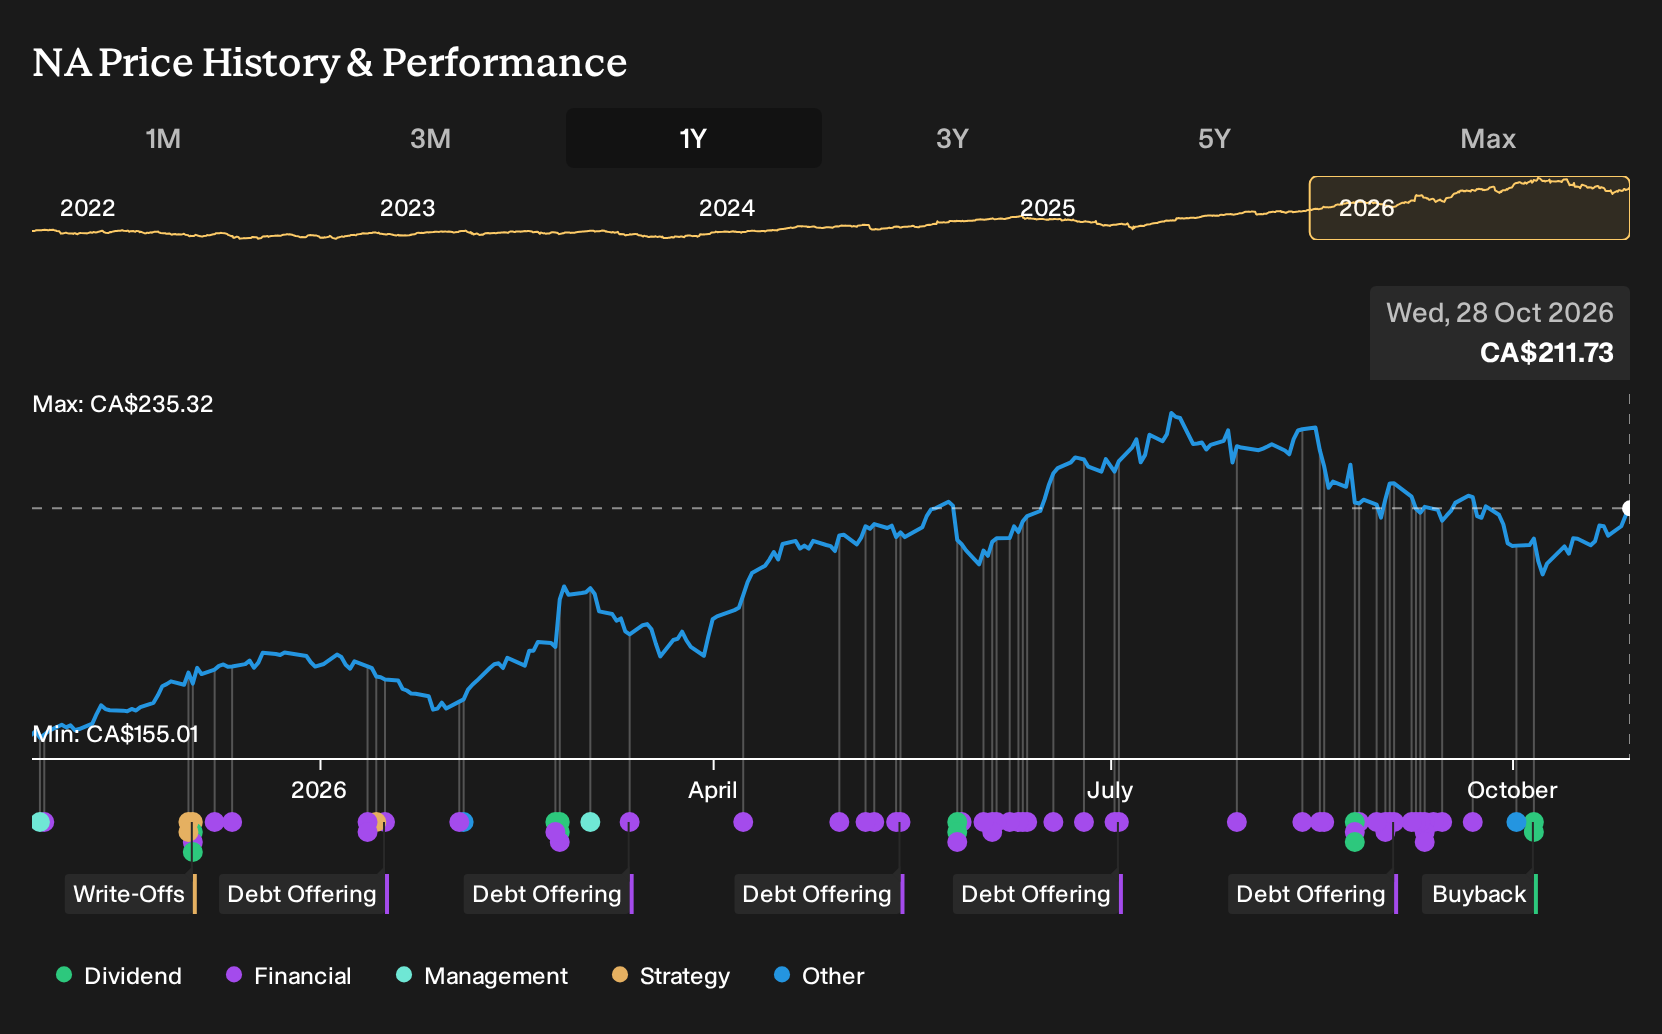
Uncover how National Bank of Canada's fair value indicates a 6% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly CA$223.75 to CA$287.48, so private investors are applying very different lenses to National Bank of Canada. Layer on delayed capital relief and margin pressure against integration synergies, AI driven efficiency and planned buybacks, and you get a wide field of outcomes worth exploring.
Explore 2 other National Bank of Canada fair value estimates, including one that suggests as much as 36% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your National Bank of Canada research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for National Bank of Canada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Bank of Canada's overall financial health at a glance.
Looking for more investment ideas beyond National Bank of Canada?
Once you have a handle on National Bank of Canada, it can help to widen the lens and compare it with other opportunities that fit different portfolio goals using the Simply Wall St Screener.
- For investors chasing potential mispricings with quality in mind, scan a curated set of 4 high quality undervalued stocks that pair solid fundamentals with what may be appealing entry points.
- If capital preservation and steadier profiles sit higher on your checklist, sort through a focused pool of 8 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- When you want to back lesser known stories with strong numbers behind them, sift through 8 high quality undiscovered gems that might not be widely followed yet but still clear solid fundamental hurdles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com