


Skydance has been in the spotlight after a roughly US$1b investment from Elon Musk, yet the share price, recently at US$7.77, has fallen sharply in recent years. That mix of high profile capital and a long slide in the stock leaves a simple question for investors who care about fundamentals: how much sales really justify paying for Skydance today.
- Over the past 5 years the share price has fallen 69.5%, which puts the current market value under pressure to be explained by the revenue the business generates.
- Musk's roughly US$1b funding, aimed at reinforcing Skydance's balance sheet as it manages existing debt and cost cuts, may support different expectations for how much future sales are worth today.
- The analysts covering Skydance have run their own numbers. See what analysts think Skydance's shares could be worth.
The stock's next move may depend on whether the current price can be justified by Skydance's sales base and how investors choose to value each dollar of that revenue.
If you want more context around what Musk's Skydance bet might mean in valuation terms, it can help to line it up against 26 high quality undervalued stocks.
Does Skydance Look Undervalued on Sales?
P/S fits Skydance because investors are effectively paying for its content and distribution reach long before profits show up cleanly in earnings.
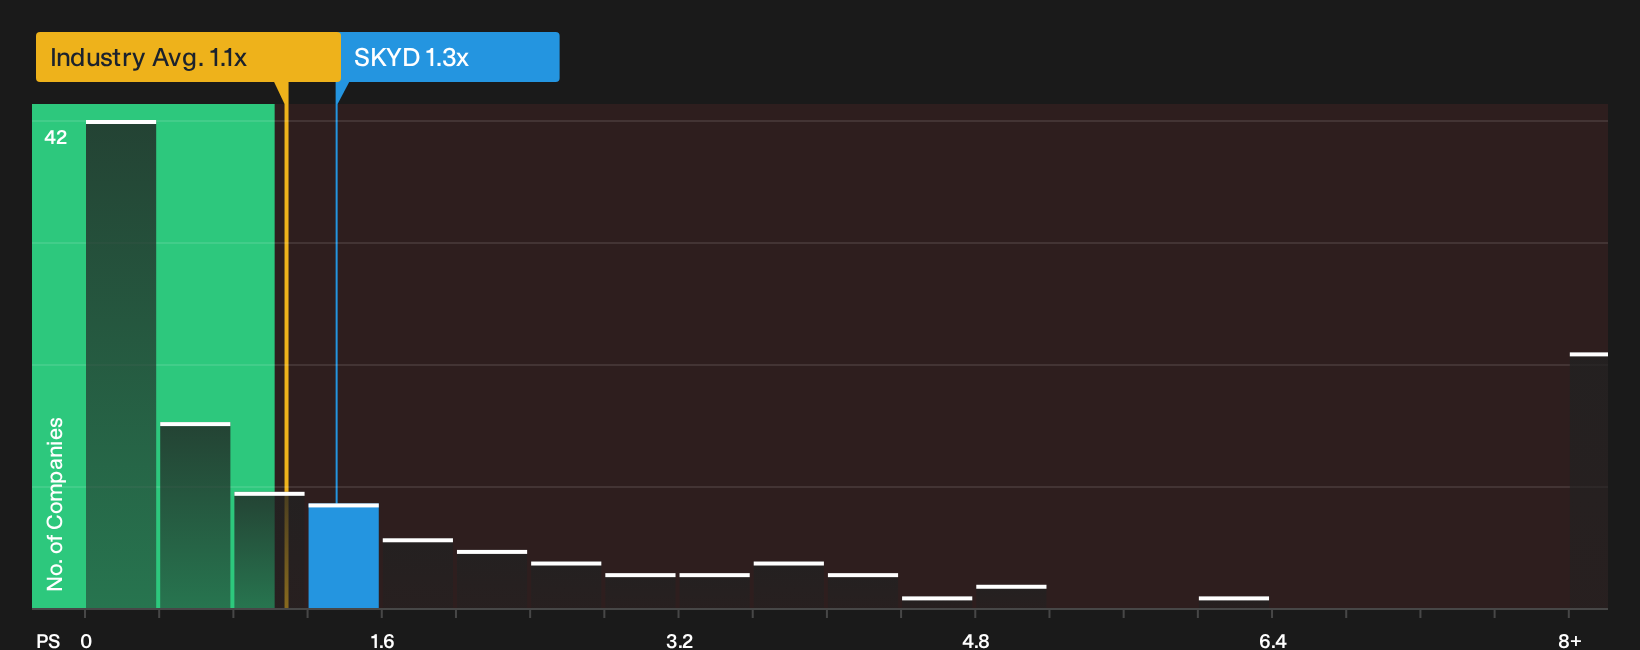
On this yardstick, Skydance trades on a P/S of about 1.3x. The broader media group averages roughly 1.1x, while closer peers cluster higher near 2.0x. That puts the stock at a modest premium to the sector but at a discount to similar businesses that the market currently prices more richly per dollar of revenue.
The Fair Ratio model, which adjusts for Skydance's growth profile, margins, size and risk, implies investors might typically pay more per unit of sales than the current 1.3x. Because Elon Musk's roughly US$1b injection targets the balance sheet rather than near term sales, the P/S gap to that tailored benchmark suggests the recent funding has not fully translated into a higher revenue multiple yet. Explore the numbers behind Skydance's P/S valuation.
The Skydance Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation puzzle around Skydance and explain what kind of future path for growth, margins and earnings would need to hold for the shares to be worth materially more or less than they are today, using the Community page to frame each scenario. Each narrative then links a fair value estimate to a clear story about Skydance's possible catalysts and risks so you can see over time which version of events appears to be unfolding.
Community views on Skydance split sharply between those who see upside in the enlarged content group and those focused on leverage risk.
Bull case: 14% undervalued
"The planned expansion of theatrical output to at least 15 films per year from 2026, combined with over US$1.5b of incremental programming investment across film and streaming, is intended to build a larger, recurring slate..."
Discover why this Narrative puts Skydance at 14% undervalued.
Bear case: 85% overvalued
"The aggressive plan to grow theatrical output to at least 15 films per year starting in 2026, combined with more than $1.5 billion of incremental programming spend, risks oversaturating a slowing box office and fragmenting audiences..."
Explore why this Narrative puts Skydance at 85% overvalued.
For Skydance, who is steering the ship matters as much as the sticker price
Valuation tells you what investors are paying for Skydance today, but the real story often sits with the people setting priorities, striking deals and writing their own pay cheques. See who runs Skydance and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com