


Rapid moves in inflation and interest rate expectations are putting every cash-based business model under the spotlight, especially those tied to short-term customer balances. With PCE inflation running above the Fed’s target and markets bracing for tighter policy, the way companies handle idle cash can quietly reshape earnings risk. This article unpacks three US Short-Term Rate-Sensitive Financials from our screener that appear positively exposed to this backdrop and explains what that could mean for your portfolio decisions.
The three stocks highlighted next are only a starter set, and the full screen surfaces 19 more US Short-Term Rate-Sensitive Financials with equally compelling cash-flow stories that are not covered below. To size up that broader field and identify which balance sheets and fee models you rate highest, head straight to the US Short-Term Rate-Sensitive Financials screener.
Colony Bankcorp (CBAN)
Overview: Colony Bankcorp is a Georgia based retail and commercial bank that gathers deposits and makes loans, closely tied to short term interest rates.
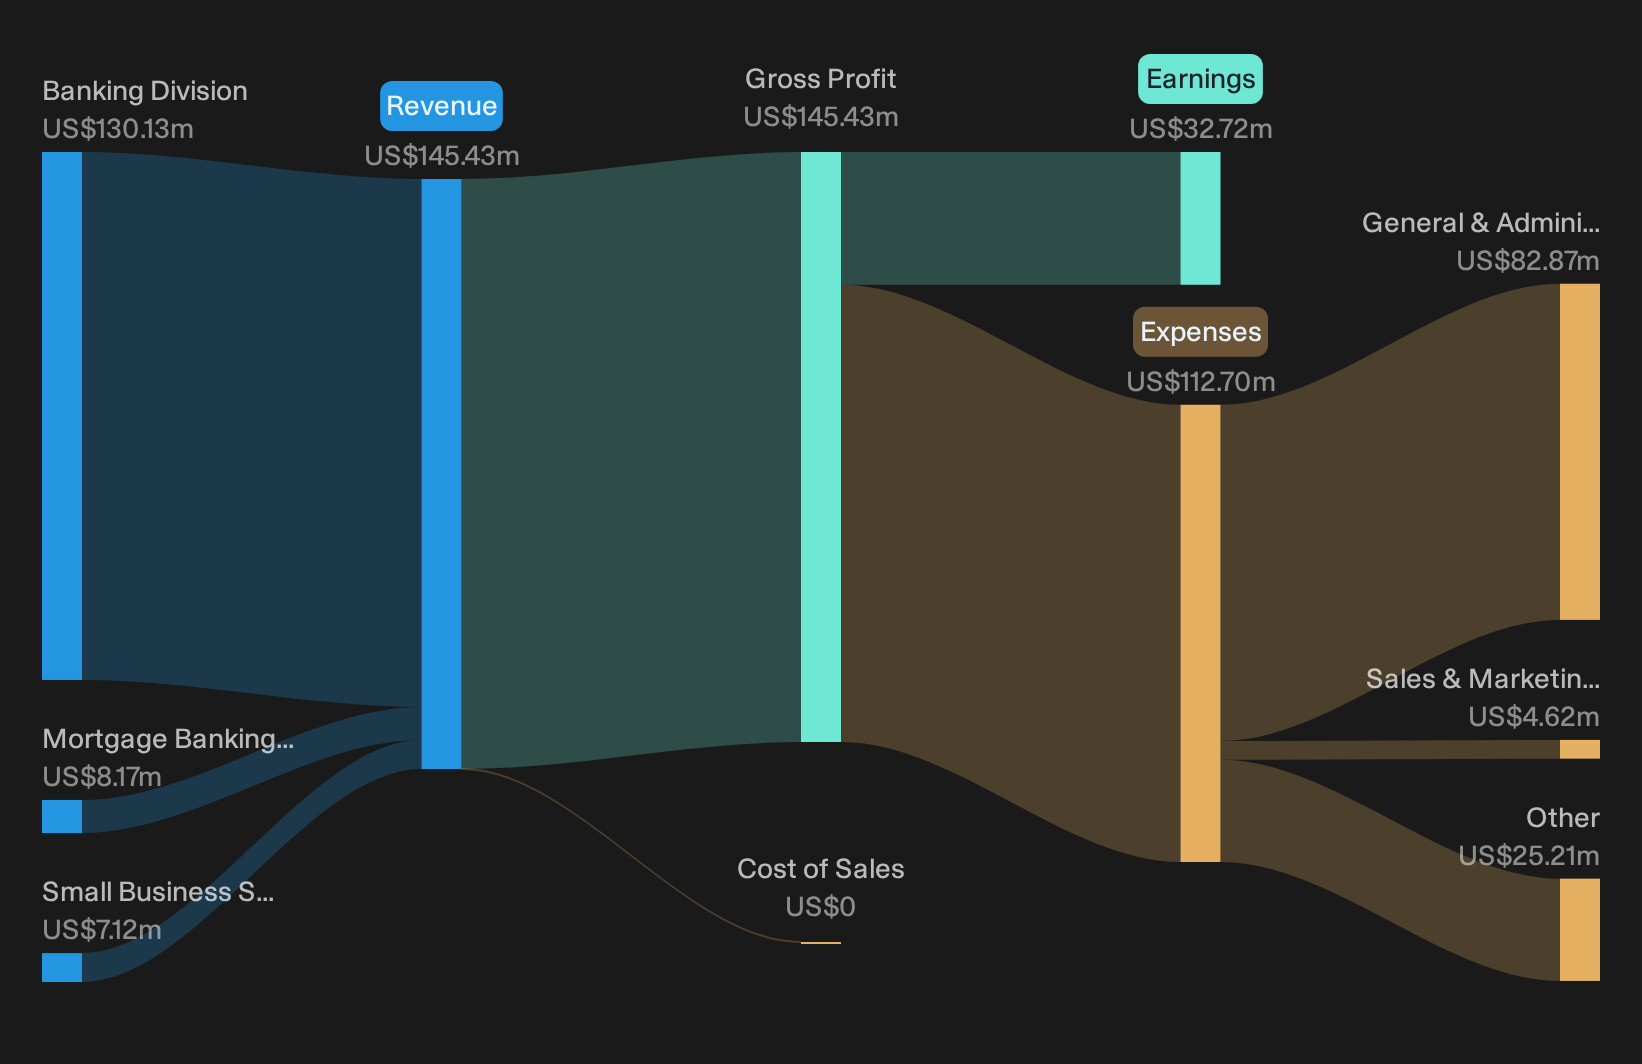
Operations: Colony Bankcorp generates about US$130 million from its Banking Division, with smaller contributions from Mortgage Banking and Small Business Specialty Lending, all in the United States.
Market Cap: US$433 million
Colony Bankcorp matters for this short term rate theme because its core deposit and lending engine lives and dies by what happens to cash yields, yet management is quietly reshaping the mix of how those dollars are earned.
"The build out of fee-based businesses such as Colony Financial Advisors and Colony Insurance, including almost 15% quarter over quarter growth in assets under management to US$637 million and record pretax income in the insurance unit, positions Colony Bankcorp to generate more noninterest income and reduce reliance on spread revenue over time."
The real swing factor for margins now sits in how one pressure on funding costs collides with this shift toward steadier fee income.
That collision of funding costs and fee momentum is exactly what the full narrative for Colony Bankcorp unpacks, including where earnings risk might already be decoupling from rate moves.
Nicolet Bankshares (NIC)
Overview: Nicolet Bankshares is a regional bank that gathers deposits and offers loans and cash management services to customers across Wisconsin, Michigan and Minnesota.
Operations: Nicolet Bankshares generates about US$581 million in revenue from consumer and commercial banking services, entirely within the United States.
Market Cap: US$3.6b
Nicolet Bankshares provides direct exposure to short term rates through a broad base of checking, savings and money market balances that feed into cash management and lending. Recent earnings beats and margin gains reflect the current economics on those deposits. The interaction between funding costs and loan yields may have a significant impact on future profitability.
That funding versus yield tug of war is exactly what the 3 key rewards and 1 important major warning sign unpacks, helping you see where Nicolet Bankshares earnings sensitivity could quietly shift next.

Columbia Financial (CLBK)
Overview: Columbia Financial is a New Jersey based community bank offering deposits, loans, and cash management services to households and businesses.
Operations: Columbia Financial generates about US$267 million from financial services in the United States, primarily serving local consumers and commercial clients.
Market Cap: US$2.9b
Columbia Financial links neatly to this short term rate theme because most earnings come from net interest income on deposits, cash management and shorter dated loans, all directly tied to how customer cash is priced. Recent growth in net interest income and net income, alongside higher inflation and rate expectations, puts a bright spotlight on what happens if one unseen pressure on those funding spreads shifts again.
If that unseen pressure on funding spreads has your attention, take a look at the 3 key rewards and 1 important warning sign to see where Columbia Financial’s rate exposure could quietly be rewired next.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, quiet momentum and under the radar for now sectors can get repriced fast. Do not wait for headlines to catch up, consider acting based on your own research and risk tolerance.
- Identify resilient payers while yields are still flying under the radar with the 6 dividend fortresses before income-focused money potentially concentrates in the same tickers.
- Track early movers in next-gen computing by using the curated 25 quantum computing stocks before quantum hardware developments are fully reflected in market expectations.
- Follow the AI build out while infrastructure demand is still developing by scanning the hand picked 54 AI infrastructure stocks before capital allocation patterns change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com