


Zimmer Biomet Holdings has inched higher in recent weeks, yet the longer track record for the stock is still weak, which puts fresh focus on what investors are really paying for its earnings today. With the share price near US$96.39, the question for you is whether that tag lines up with what the business is currently earning.
- The stock is down about 30.2% over 5 years, which puts more weight on whether the present valuation rests on a sturdier earnings base than the past share performance suggests.
- Recent moves into intelligent orthopedic surgery and expanded robotic-assisted knee systems can shape how the market thinks about Zimmer Biomet's future profit potential and the durability of its earnings stream.
- Your read on Zimmer Biomet Holdings is one view; the desks covering it have another. See what analysts think Zimmer Biomet Holdings's shares could be worth.
For investors, the debate is whether Zimmer Biomet's current price is properly anchored to its earnings power or whether expectations have stretched beyond what the income statement supports.
If you are weighing Zimmer Biomet Holdings against other ways to play orthopedic robotics and related technologies, it can help to line it up beside 93 robotics and automation stocks.
Is Zimmer Biomet Holdings a Bargain on Earnings?
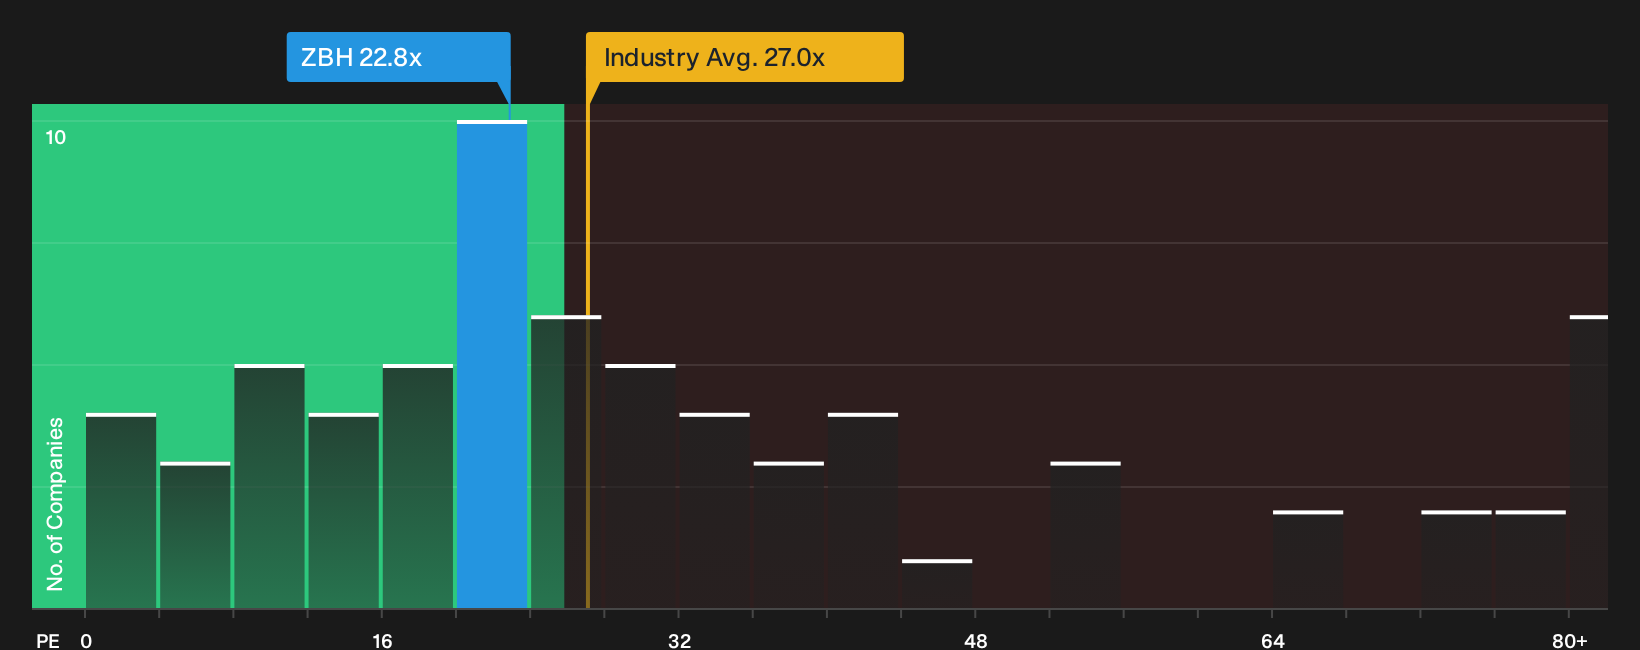
The P/E ratio is a useful lens for Zimmer Biomet Holdings because earnings still influence how investors view its orthopedic and robotics story. On that measure, the stock trades around 22.8x earnings, which is below both the Medical Equipment sector average of about 27.0x and a peer group closer to 38.2x. For a reader, that gap means the market is currently assigning a lower price per dollar of Zimmer Biomet earnings than it does for many comparable medical technology stocks.
Because the fair multiple derived from the company’s own profile sits above the current 22.8x level, this framework suggests Zimmer Biomet is undervalued on a P/E basis relative to what its mix of growth prospects, margins and risk would usually justify. Recent attention on ROSA Knee upgrades and the broader intelligent orthopedic surgery focus has increased interest in its robotics earnings profile, yet the valuation still trades at a discount to those sector and peer benchmarks. Explore the numbers behind Zimmer Biomet Holdings's P/E valuation.
The Zimmer Biomet Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Zimmer Biomet Holdings' valuation puzzle leaves off and spell out what assumptions on growth, margins and earnings would need to hold for the stock to be worth significantly more or less than today’s price on the Community page. Each narrative ties a specific fair value to a clear storyline about Zimmer Biomet Holdings' potential catalysts and key risks, so you can track which version of events is gradually taking shape over time.
One of the top community narratives on Zimmer Biomet Holdings: 10% undervalued
"The main factor that has to go right is successful execution of the commercial and cost-efficiency programs, including Project Optima, the global capability center in India..."
Discover why this Narrative puts Zimmer Biomet Holdings at 10% undervalued.
Zimmer Biomet Holdings: why the story is not finished at today's share price
Zimmer Biomet's current valuation only tells you what the market pays for earnings today. The missing piece is how professional analysts map this business a few years from now. Explore where analysts expect Zimmer Biomet Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com