


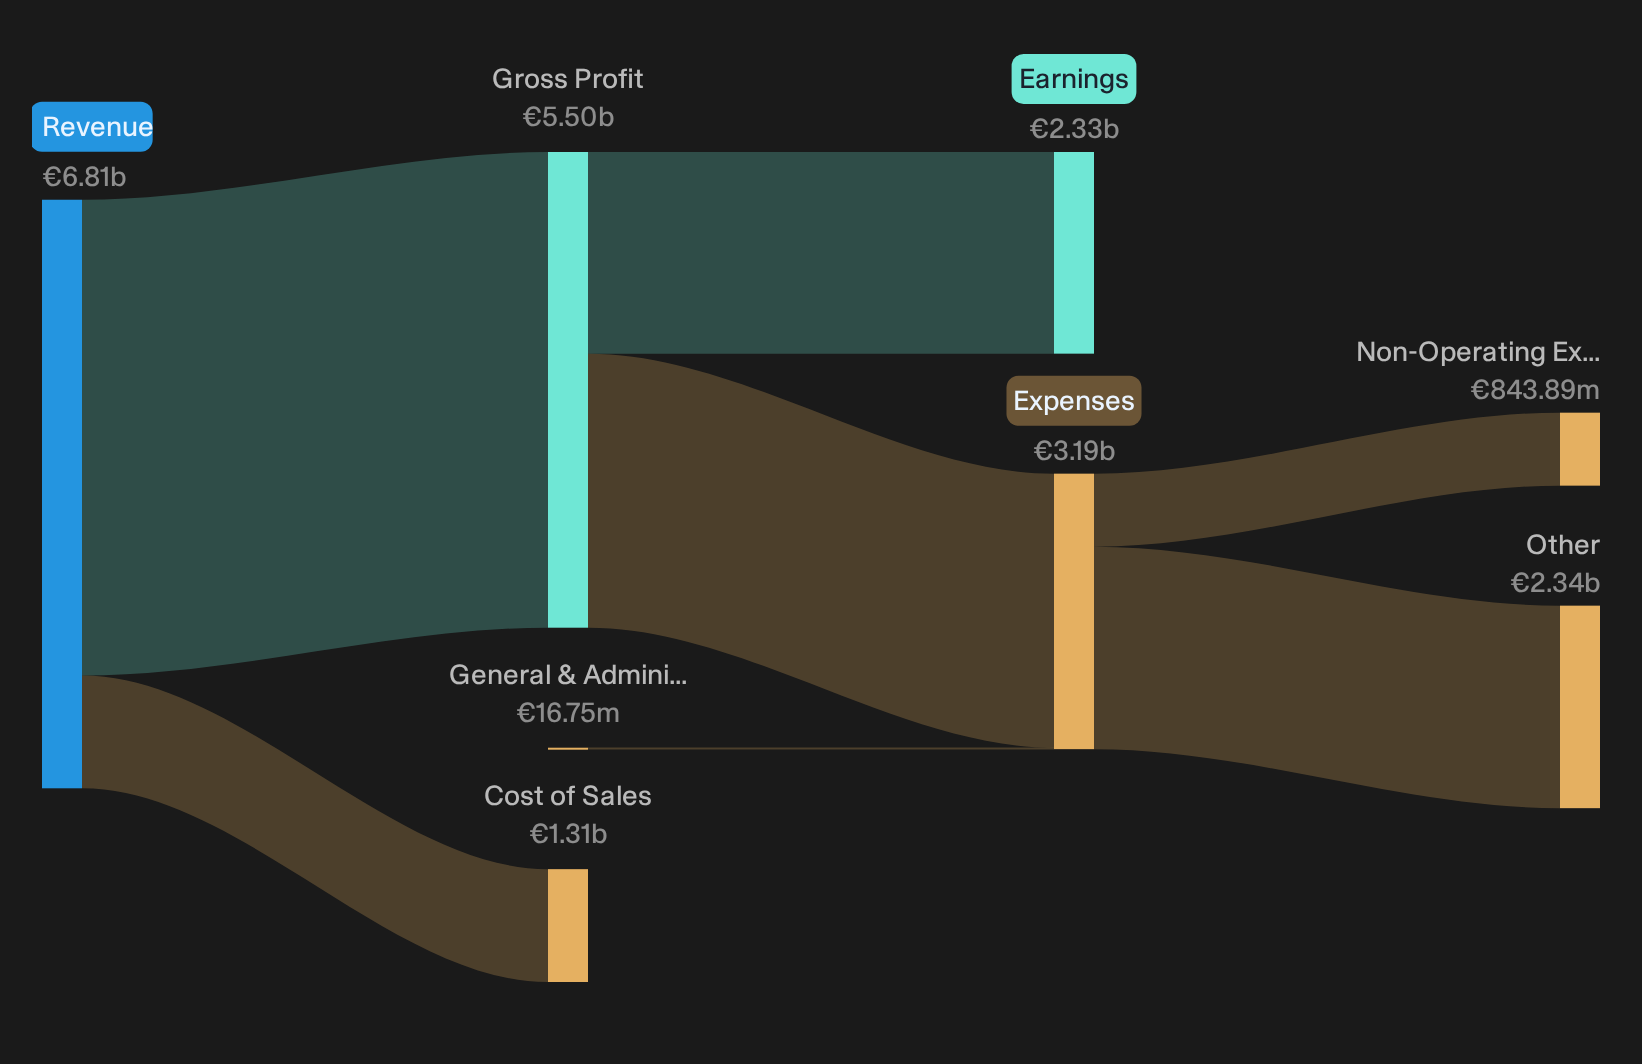
Aena S.M.E came into this Q3 2026 report with its stock quietly grinding higher, up low single digits over the past month and quarter as investors leaned on the long term airport monopoly story. The fresh numbers landed with a jolt. The shares closed at €27.24 after the release even as quarterly revenue printed at €1,974.4m and basic earnings per share reached €0.51. The real swing factor was profitability, with net income excluding extra items at €772.8m, which sharpened the debate on how much of Aena’s current earnings power is already priced in.
Like the Aena S.M.E story but wondering if this profitability burst is already fully reflected in the share price and want a comparison set with sturdier balance sheets and fundamentals? Compare it with our list of solid balance sheet and fundamentals stocks (207 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €1,974.4m vs €1,770.8m (up 11.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): €772.8m vs €685.7m (up 12.7%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.51 vs €0.45 (up 13.6%)
- Trailing 12 Month Net Profit Margin (latest vs prior year): 34.3% vs 33.5% (modest improvement)
Prefer clean charts over another wall of numbers and footnotes? Get a full visual read on Aena S.M.E, including how analysts frame its valuation in the company report for Aena S.M.E..
Aena’s Upside Case Meets Early Execution Milestones
The bullish view depends on Aena S.M.E turning regulated spend and new concessions into richer cash flows rather than just more traffic volume.
"The main factor that has to go right is that Aena S.M.E converts the large DORA III capex plan and the expanding Brazilian and UK portfolios into higher quality cash flows, despite persistent cost inflation and tighter service requirements."
Q3 profitability, with net income excluding extra items at €772.8m and a slightly higher trailing net margin, indicates that heavier cost items have not yet eroded earnings power. The formal Galeão takeover in October, in addition to the existing 17 Brazilian airports and the Augusta UK platform, means the international scale leg of that thesis has moved from plan to execution.
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for.
Evaluating Aena’s Cost Squeeze Fears Against Q3 Print
Bearish investors argue that Aena S.M.E is running into a cost ceiling that traffic and commercial gains might not clear.
"Although Aena S.M.E is benefiting from higher commercial and real estate revenue per passenger, the sharp rise in underlying operating expenses such as staff, maintenance, security, PRM services and VIP lounges, which in H1 2026 pushed group OpEx up 13.5% year on year, risks eroding operating leverage and compressing net margins if these costs outpace future revenue growth."
Q3 presents a mixed picture. Reported revenue and net income excluding extra items grew at roughly similar double digit rates, and trailing net margin edged higher to 34.3%. That does not show margin damage yet. The concern is more about timing, as OpEx pressure that was visible in H1 has not reversed. In addition, Galeão introduces another regulated and local cost layer that has not fully flowed through these figures.
Hunt For Mispriced Earnings Power
Aena S.M.E just showed how a single quarter can reshape views on earnings quality. The real opportunity sits in finding stocks that could be undervalued before the market closes the gap.
- Company 1 - 28% below our estimate - targets higher AI driven memory and mixed signal workloads as new clean-room capacity comes online.
- Company 2 - 26% below our estimate - expands high value prosthetics and neuro orthotics while overhauling clinics and manufacturing to tighten patient care economics.
- Company 3 - 25% below our estimate - supplies sensors and software into longer defence programmes as customers shift toward underwater protection and autonomous platforms.
Those are three of them. See all 191 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com