


Plains All American Pipeline (PAA) has moved into focus after upbeat analyst sentiment, a favorable peer comparison on return on equity and leverage, and recent upward shifts in earnings estimates.
Recent trading has been upbeat for Plains All American Pipeline, with a 1 month share price return of 11.16% and a year to date share price gain of 46.07%. The 1 year total shareholder return of 69.28% and 5 year total shareholder return of 262.17% indicate momentum that investors are treating as a sign of improving growth prospects and a lower perceived risk profile around the current US$26.60 price.
Scan other energy infrastructure plays that show similar momentum and balance sheet support in our curated list of 26 high quality undervalued stocks, alongside Plains All American Pipeline's recent move.
Bulls view Plains All American Pipeline as a quality pipeline operator currently trading below its estimated worth, while bears argue the recent run already reflects the positive developments. Which side does the current valuation support?
Price-to-Earnings of 22.9x: Is it justified for Plains All American Pipeline?
Plains All American Pipeline screens as expensive on a simple P/E check, trading at 22.9x earnings, while our model also flags the units as trading well below an internal fair value estimate based on future cash flows. The last close at $26.60 therefore sits at an interesting intersection of a rich earnings multiple and discounted cash flow output.
The P/E ratio compares what investors are paying for each dollar of current earnings. For a midstream operator like Plains All American Pipeline, this often reflects how durable the market believes its cash flows are and how stable future profit streams might be across energy cycles.
Management has delivered very strong recent earnings growth, with profit reported as having grown by 258.5% over the past year and by 8.6% per year across the last 5 years, which helps explain why investors are willing to pay a higher price per unit of earnings. Our SWS DCF model, which projects future cash flows and discounts them back using a required rate of return, currently suggests a future cash flow value of $73.76 per unit compared with the current $26.60 trading level. This is a very wide gap for investors to weigh against the headline P/E premium.
On the relative side, Plains All American Pipeline is described as expensive versus both its sector and a modelled fair ratio. Its 22.9x P/E is higher than the US Oil and Gas industry average of 12.4x and also above an estimated fair P/E of 17x. This indicates the market is paying a strong premium to both peers and the level that regression analysis suggests could be more typical if sentiment cooled.
Explore the SWS fair ratio for Plains All American Pipeline.
Result: Price-to-Earnings of 22.9x (OVERVALUED)
Still, the bullish Plains All American Pipeline story can unravel if earnings growth stalls or if energy volumes weaken enough to challenge current cash flow assumptions.
Find out about the key risks to this Plains All American Pipeline narrative.
Another View on Plains All American Pipeline's Value
The P/E points to Plains All American Pipeline looking expensive, yet the SWS DCF model paints a very different picture. On that cash flow view, an estimated value of $73.76 per unit versus the $26.60 price screens as heavily undervalued. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
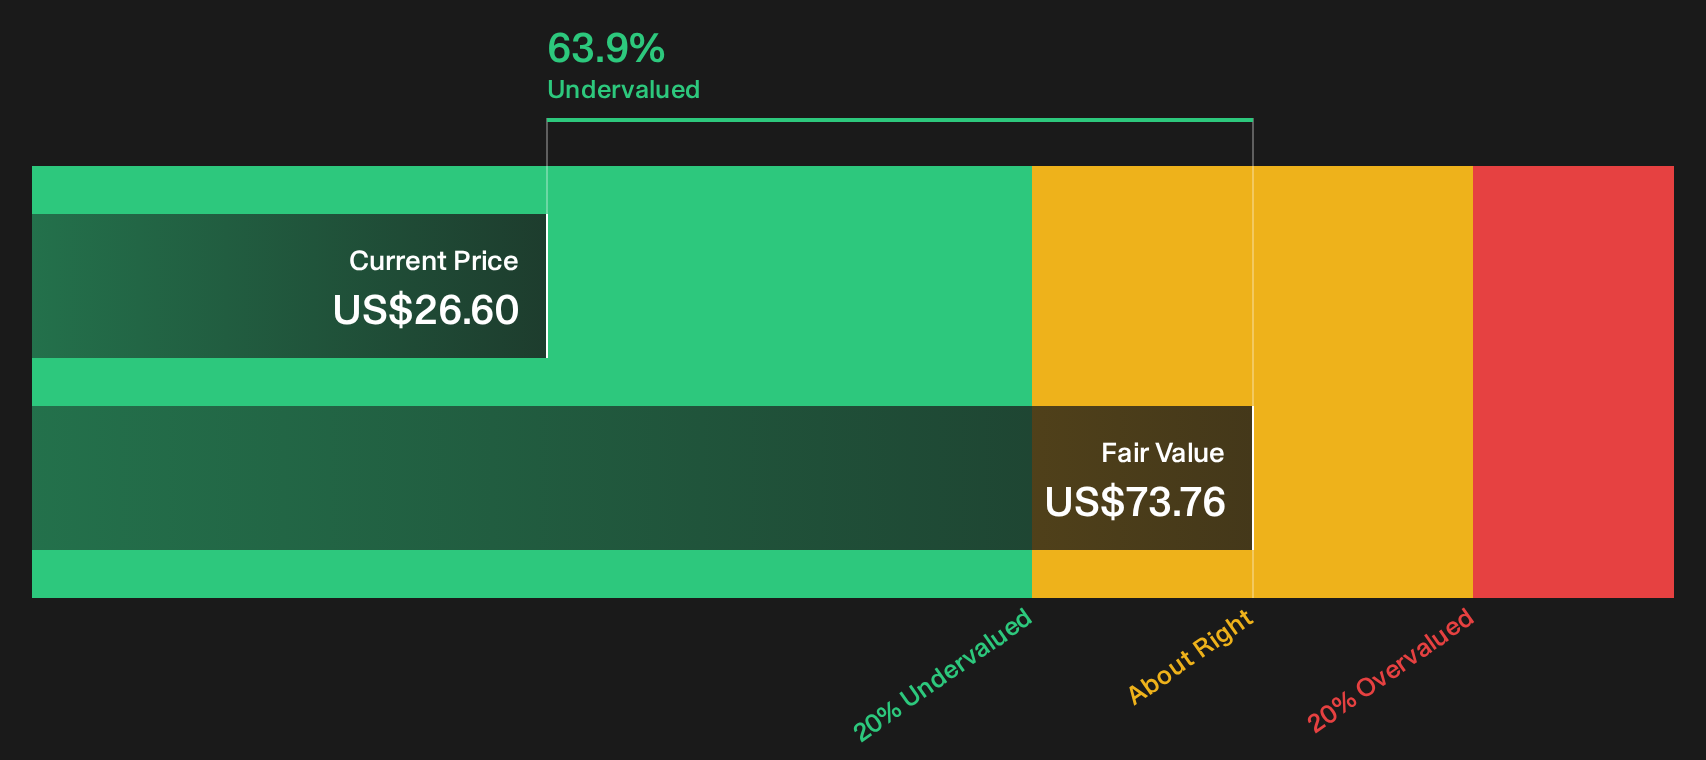
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Plains All American Pipeline for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Plains All American Pipeline can feel energizing or uncomfortable, depending on your risk appetite and time horizon. Move quickly to review the underlying numbers, weigh the upside and the issues, then ground your decision in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Plains All American Pipeline?
If Plains All American Pipeline has sharpened your focus on valuations, do not stop here. Broaden your watchlist now with fresh ideas filtered by quality and risk.
- Target potential turnaround opportunities by scanning 9 elite penny stocks with strong financials that already show stronger financial underpinnings than many peers.
- Focus on consistent income streams with a hand picked pool of 6 dividend fortresses that meet clearly defined yield and quality criteria.
- Prioritize resilience in tougher markets by filtering for a 32 resilient stocks with low risk scores that keeps financial risk scores front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com