


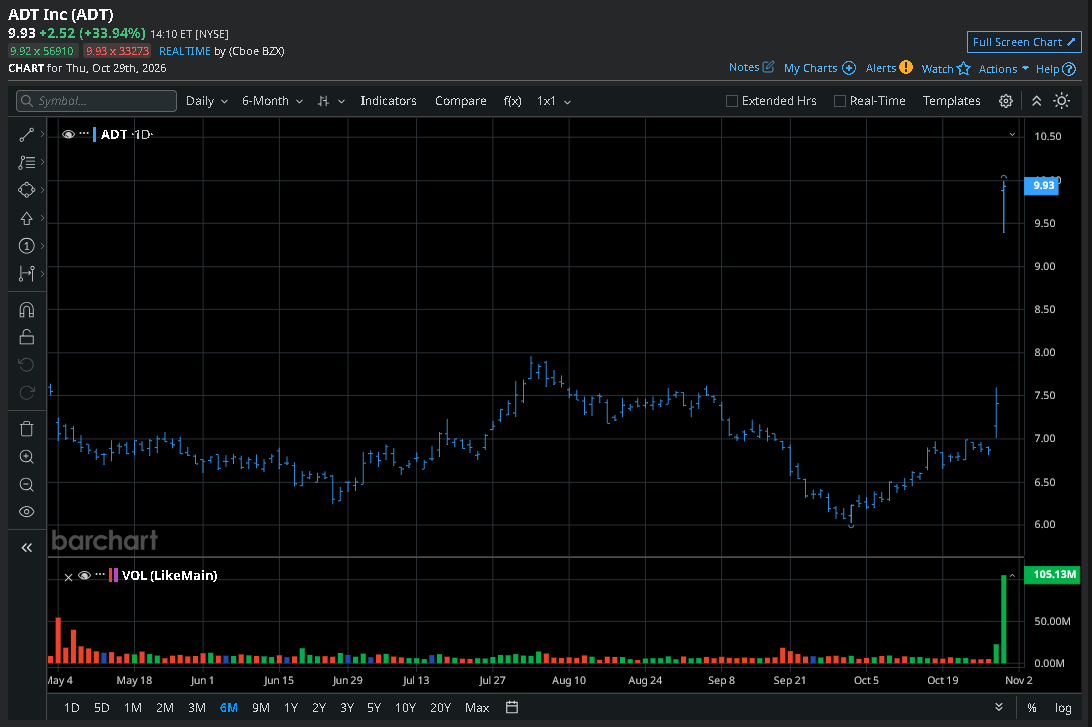
ADT (ADT) stock charged aggressively to the upside on Oct. 29 after Thrive Holdings agreed to take the home-security company private in a deal worth $15.3 billion in enterprise value. The agreement valued ADT shares at $10 each, representing about a 35% premium on their prior close.
Following today’s cosmic run, ADT shares are trading sharply above the price at which they started 2026.
Why ADT Stock Rallied on Thrive’s Announcement
Investors cheered the announcement primarily because of the premium Thrive Holdings has agreed to pay. Financing commitments come from funds managed by Apollo affiliates, and the agreement has no financing condition. Those provisions reduce funding uncertainty, although shareholder and antitrust approvals remain necessary for the transaction to be completed in the first quarter of 2027.
ADT can also solicit competing bids through Nov. 28, leaving room for a potentially richer offer.
For the business, Thrive brings long-term capital and engineering resources to strengthen products and customer service. Existing shareholders, however, would receive cash rather than participate in that future growth.
Is There Any Upside Left in ADT Shares?
Following today’s surge, ADT shares’ remaining upside looks relatively limited under the existing agreement. At $9.94, the company’s share price sits less than 1% below Thrive’s buyout price, leaving little room for additional gains without a competing bid.
And while that possibility remains open, ADT itself cautioned that a superior offer may never materialize. Investors buying now must, therefore, weigh a modest potential return against the risk of delays or a failed transaction.
The deal also changes which catalysts matter most. Upcoming quarterly earnings may influence confidence in ADT’s underlying value, but the buyout timetable should increasingly drive trading. Fresh buyers must consider how long their capital will remain committed before they receive the minor remaining upside.
Wall Street’s Consensus View on ADT
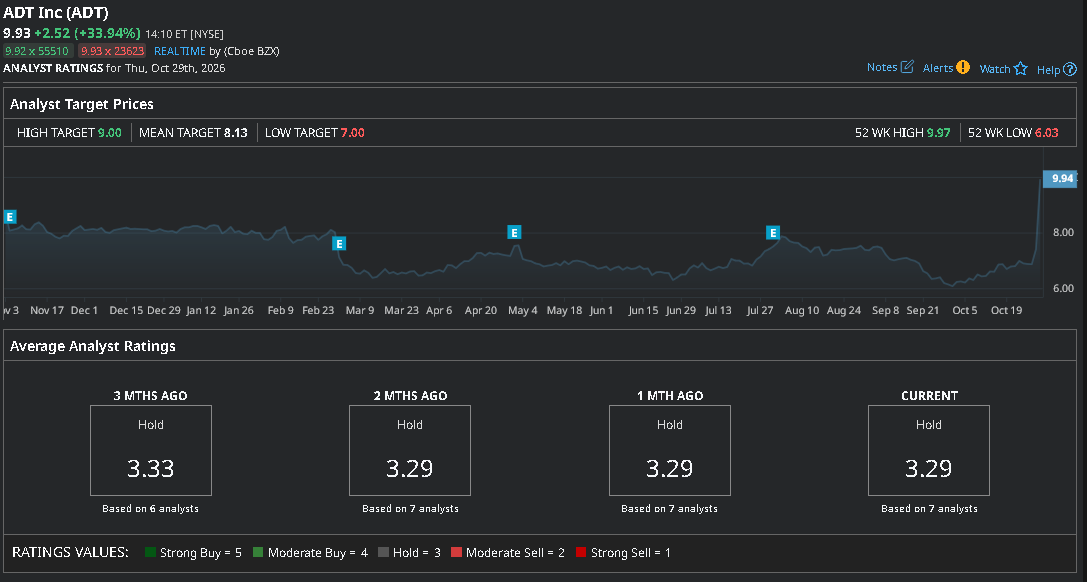
Heading into Oct. 29, Wall Street had a consensus “Hold” rating on ADT stock with a mean price target of about $8.13.
This means analysts did not expect ADT, as a standalone company, to be worth what Thrive has already valued it at, at least not in the near term.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.