


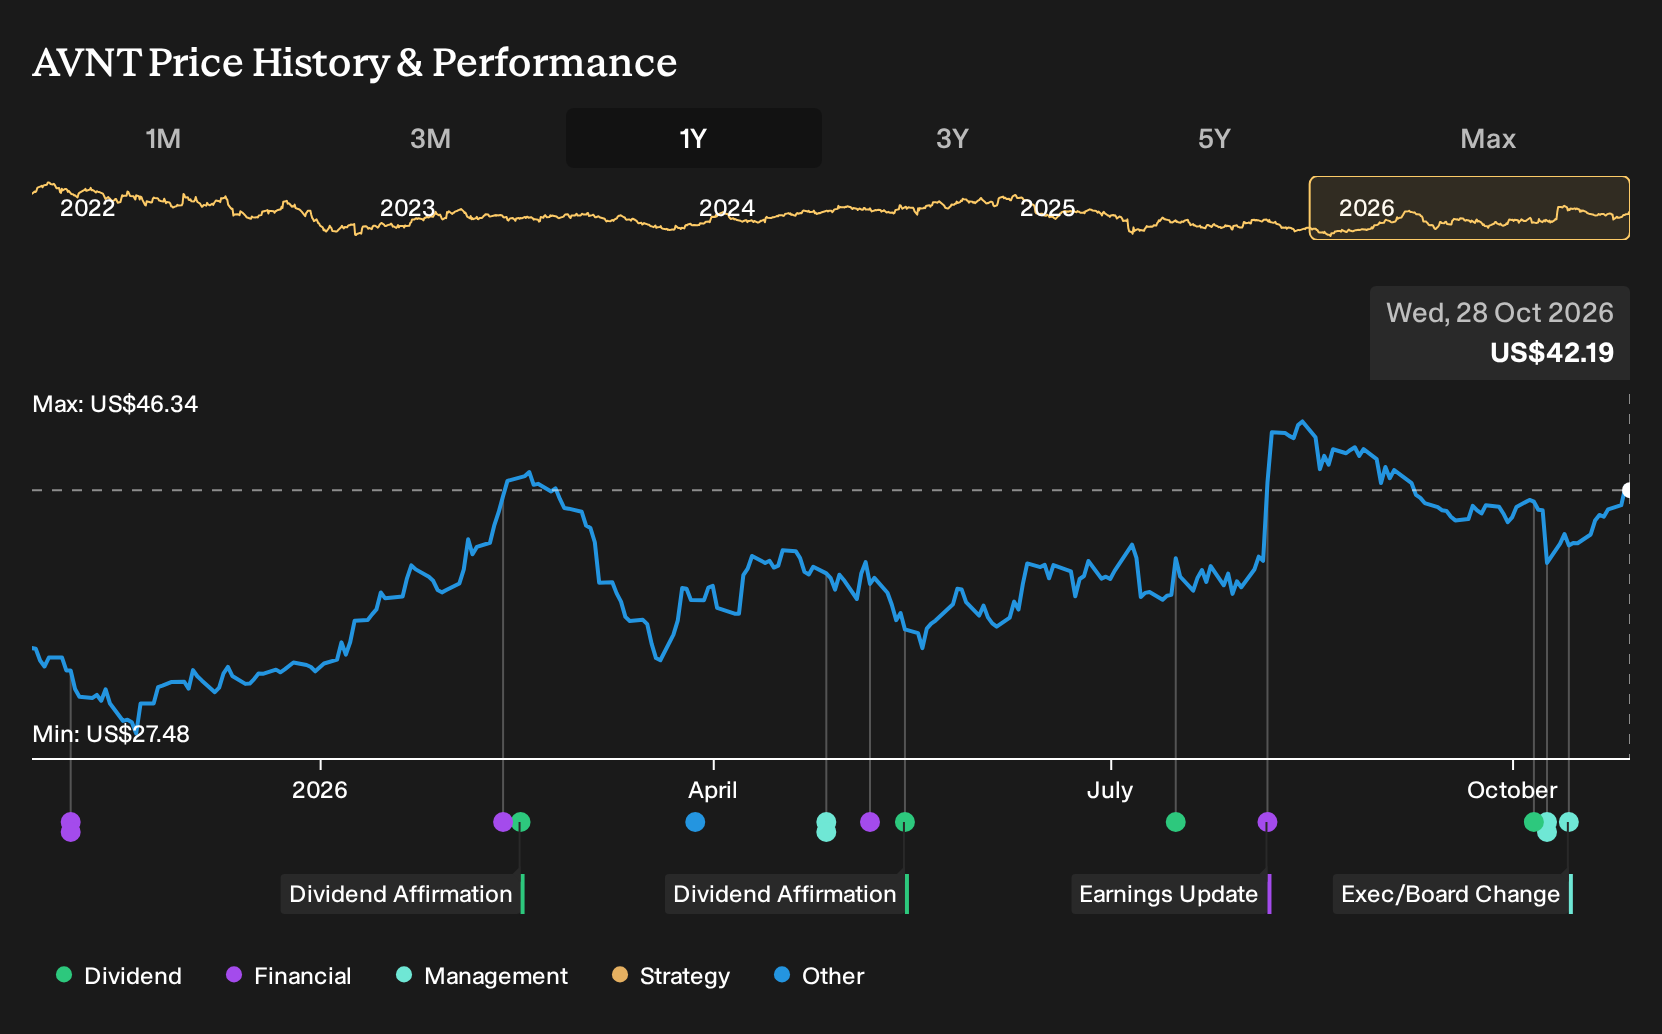
- Avient recently drew attention for offering a dividend yield that is higher than its industry and the S&P 500, with recent payout growth and a payout ratio that leaves room for reinvestment.
- The appointment of George T. Clark as Director of Investor Relations signals a tighter focus on how Avient explains its capital priorities and margin goals to the market.
- The investment narrative for Avient will now be evaluated in light of this stronger dividend profile and the new investor relations leadership.
Scan income-focused opportunities that share Avient's mix of yield, payout discipline, and reinvestment capacity by reviewing our hand picked 6 dividend fortresses.
Avient Investment Narrative Recap
To own Avient, you need to be comfortable with a materials specialist that is leaning into higher value electronics, healthcare and packaging formulations while still carrying exposure to cyclical transportation and other industrial uses. In the near term, the story hinges on converting that mix toward segments tied to data centers, non PFAS packaging and Asia, where recent orders have supported better margins.
The biggest near term catalyst is operational execution on those growth vectors and productivity programs, including the planned EMEA margin uplift and continued cost discipline. The main risk is that transportation related demand and slower industrial pockets stay weak enough to dilute that progress. The refreshed dividend narrative and communication change do not alter these operational swing factors in a material way.
The appointment of George T. Clark as Director of Investor Relations is the announcement that matters most for this news. A stronger dividend profile only resonates if investors clearly understand how Avient intends to balance shareholder payouts with debt reduction, margin goals and selective reinvestment in higher return projects.
Clark’s role as primary liaison with shareholders and analysts can shape how catalysts such as non PFAS adoption, electronics demand and productivity gains are framed against risks like softer transportation volumes and leverage constraints. Execution in the business still does the heavy lifting, but clearer communication around capital priorities and earnings quality can influence how quickly the market responds to operational results.
What The Current Avient Forecasts Assume
For anyone weighing Avient as an income idea with reinvestment upside, the analyst framework sitting behind the stock helps set expectations. Rather than a high growth story, the projections describe a materials specialist that grinds out modest top line increases while aiming for bigger changes in profitability over several years.
Consensus forecasts point to revenue expanding at 3.9% a year over the next three years, with profit margins moving from 5.1% today to 9.0% in that same window. Earnings are expected to reach US$338.5 million, or US$3.01 per share, by around 2029 compared with US$170.0 million now. That implies earnings a little more than doubling from today’s level, with a future P/E multiple of 17.5x on those 2029 numbers versus 22.2x on current earnings.
On the top line, analysts are effectively embedding a steady but unspectacular revenue climb supported by electronics, data center exposure and non PFAS packaging adoption, with productivity and mix improvement doing more of the work on the bottom line. For dividend focused investors, this profile pairs relatively modest assumed sales growth with quite a sharp shift in margin structure and cash generation, which can be relevant when thinking about how sustainable any future payout increases might be if those margin goals are not met.
The revenue and earnings blueprint that underpins the current price targets also assumes only very small share count growth of 0.17% a year over the next three years, along with ongoing use of cash to lower leverage. That frame matters for yield orientated portfolios, because it shapes how much room Avient might have to keep balancing dividends against debt paydown and selective reinvestment if trading conditions change or transportation heavy pockets of the portfolio stay sluggish longer than analysts currently assume.
Avient's narrative projects US$3.7b revenue and US$338.5 million earnings by 2029. This implies 3.9% yearly revenue growth and an earnings increase of about US$168.5 million from current earnings of US$170.0 million.
Uncover why Avient's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts on Avient lean heavily on defense and health care as extra growth engines. Before this dividend and investor relations news, they were penciling in around 5.0% annual revenue growth and about US$312.5 million in earnings by 2029. You can treat that as one energetic scenario and compare it with more cautious views.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Avient research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avient's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avient?
If Avient has put income, balance sheet strength and payout discipline on your radar, it can help to line it up against other opportunities that share similar traits. The Simply Wall St Screener lets you filter for those kinds of setups in a few clicks so you can build a watchlist that truly fits your approach.
- For investors who want income with resilience, you can start with companies that aim to support higher payouts over time by scanning our curated 6 dividend fortresses.
- If capital preservation ranks high for you, you could focus on businesses that pair steadier fundamentals with more measured risk using the 32 resilient stocks with low risk scores.
- When you want to broaden your Avient research with additional ideas that the wider market may be overlooking, you might review the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com