


Peloton Interactive has seen its share price swing sharply in recent years, and the stock closed at US$5.27 most recently. With Peloton down heavily over a longer horizon, the key issue now is whether that price is properly grounded in the earnings the business is generating.
- The share price has fallen 93.9% over the past 5 years, which puts the spotlight firmly on whether the earnings outlook can support even the current level.
- The business model is heavily tied to connected fitness hardware and subscription content, so the path for future profitability and cash generation may hinge on how efficiently Peloton converts its user base into sustainable earnings.
- The analysts covering Peloton Interactive have run their own numbers. See what analysts think Peloton Interactive's shares could be worth.
For investors, the debate is whether Peloton's present share price can be justified by its earnings profile when set against the Fair Ratio benchmark.
If you want to test the same earnings question beyond Peloton Interactive, you can also compare it with 26 high quality undervalued stocks.
Does Peloton Interactive Look Pricey on Earnings?
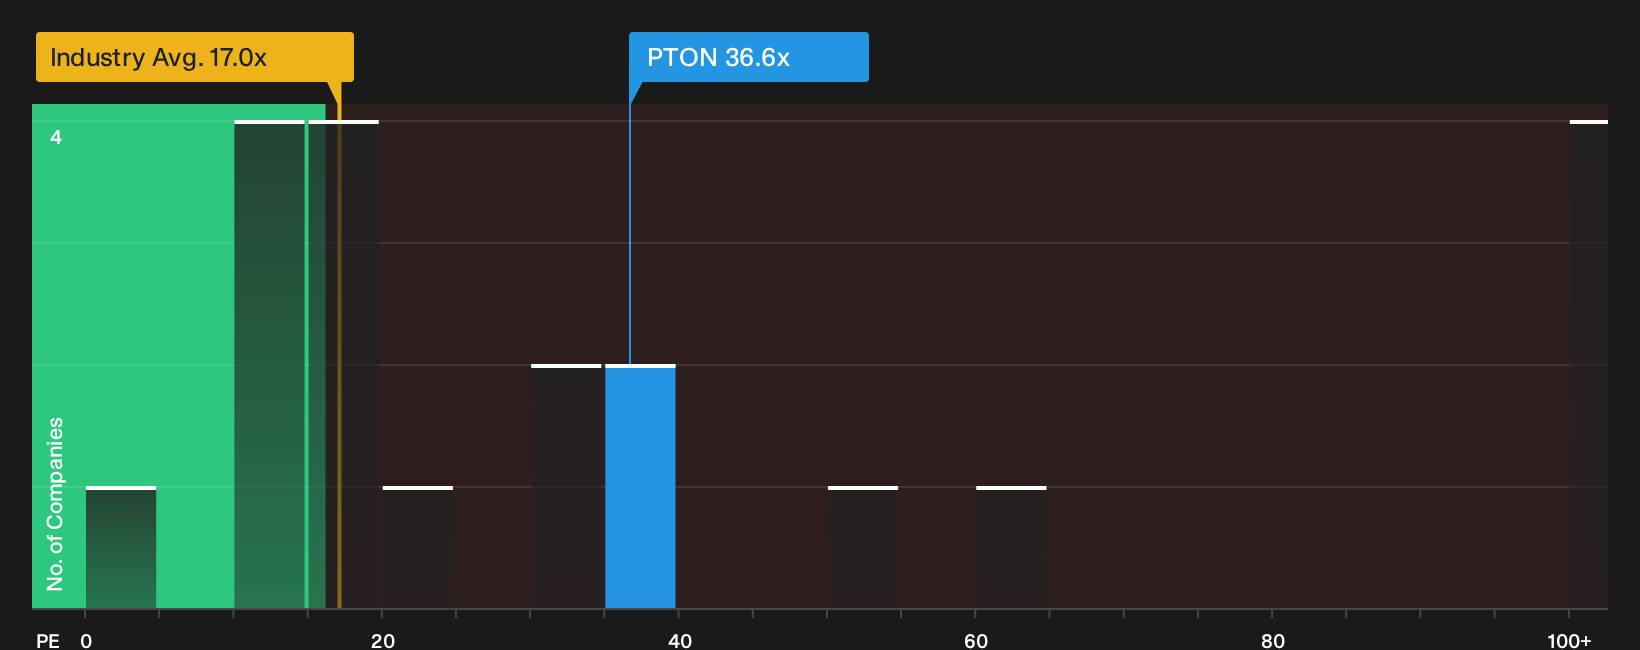
The P/E ratio is a useful starting point for Peloton Interactive because it anchors the share price directly to the earnings that support it. Peloton trades on a P/E of 36.6x, which is above the Leisure sector average of 17.0x and higher than the 20.6x level seen across peers. On raw comparison, the stock changes hands at a premium to the broader group of similar businesses.
The Fair Ratio benchmark, which blends Peloton Interactive’s growth profile, margins, size and risk into a tailored P/E yardstick, points to a lower multiple than the current 36.6x. That gap suggests the shares screen as overvalued against what this framework would usually assign to a company with these characteristics, even before you factor in any company specific execution questions. You can see how large that valuation gap is in more detail in the full model output. Explore the numbers behind Peloton Interactive's P/E valuation.
The Peloton Interactive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Peloton Interactive pick up where the P/E puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. Each viewpoint ties its number to a concrete path for Peloton Interactive's growth profile, profitability and risks, which you can revisit as fresh information comes through.
Community views on Peloton Interactive split sharply, with one group leaning into the wellness platform story and another fixated on subscription strain.
Bull case: 65% undervalued
"Integration of Skōp technology into Peloton Interactive’s fast growing Pilates category, where workout counts and time have risen by roughly mid 40% year over year..."
Discover why this Narrative puts Peloton Interactive at 65% undervalued.
Bear case: 32% overvalued
"Although new products such as the Cross Training Series, lower priced treadmills, connected Pilates offerings and AI driven Peloton IQ features are intended to refresh demand, gross subscriber additions are reported to be down about 78% from peak levels..."
Explore why this Narrative puts Peloton Interactive at 32% overvalued.
One more Peloton Interactive angle that could change your view
Before you decide what Peloton Interactive’s current price really means, it helps to know that our broader checks have surfaced specific issues that may matter to long term shareholders. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com