


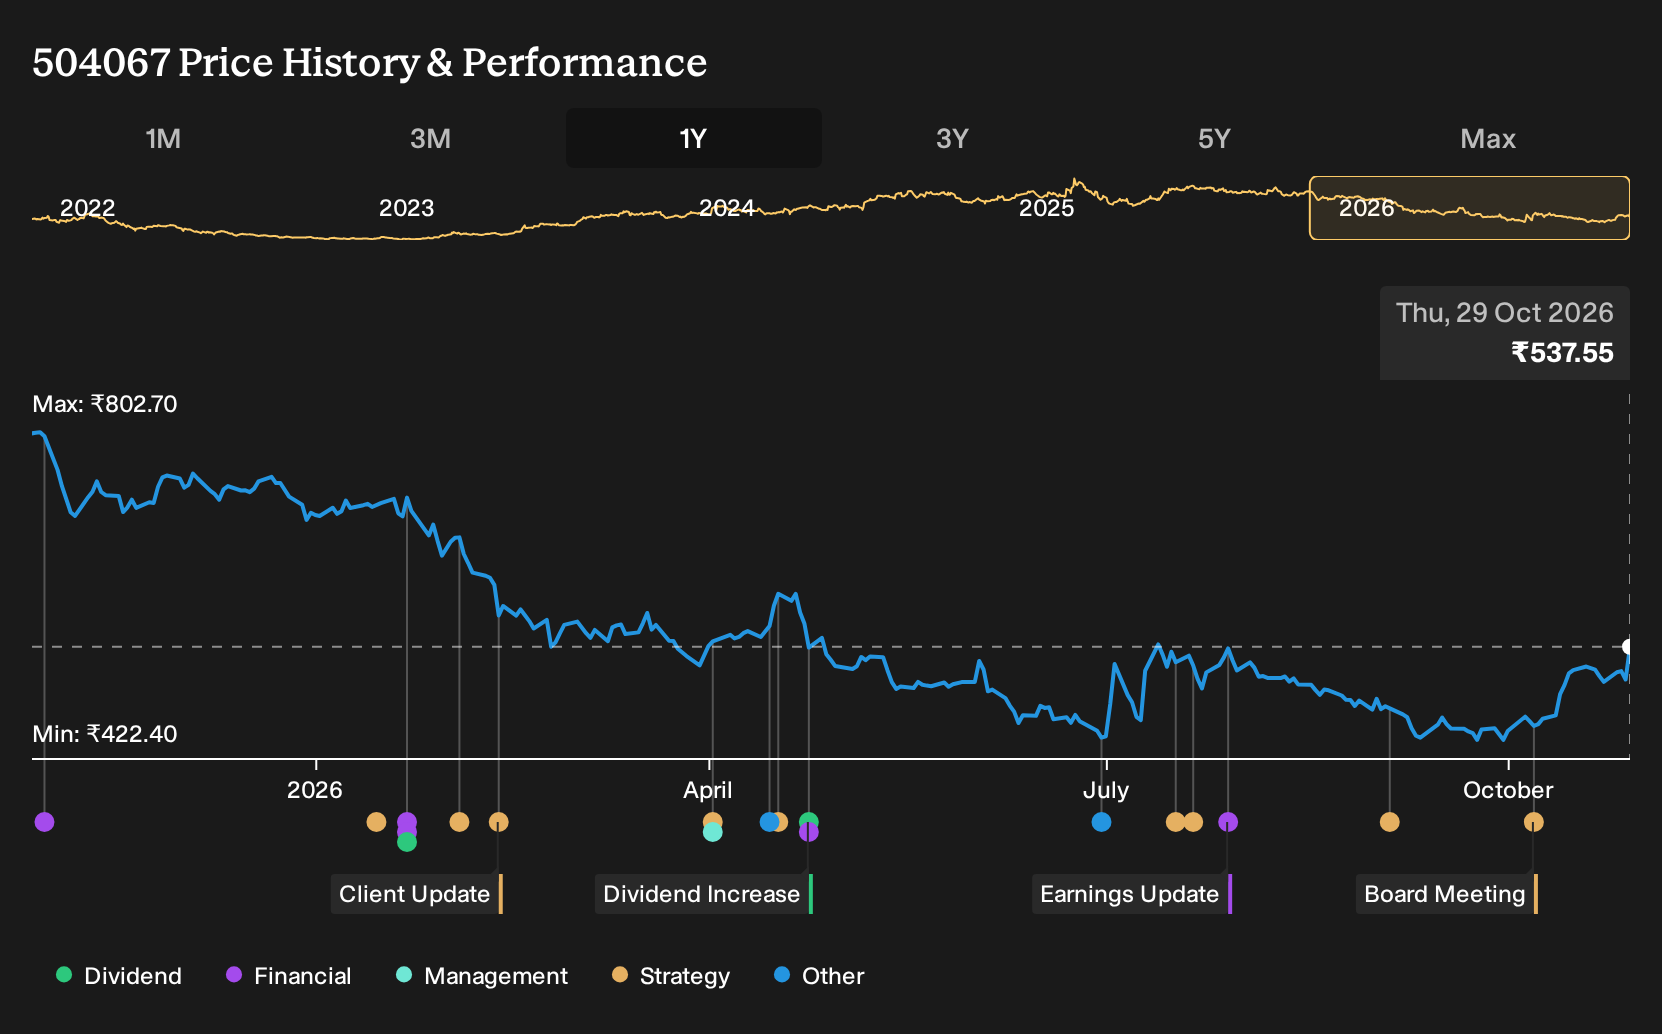
If you had looked at Zensar Technologies in late October 2025 and decided to sit it out, the choice might feel easier to justify today. For Zensar Technologies shareholders, the loss over the past year was 31.2%, including dividends. That result arrived even as later quarterly numbers showed higher revenue and profit but a thinner net margin by Q1 2027. What assumption about AI driven upside or margin resilience could you realistically have questioned at the start?
Zensar Technologies has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Really Arguing About On Zensar Technologies
The shares cost ₹802 at the start of the period, and anyone looking at Zensar Technologies then had to pick between two very different stories about how AI would reshape its business.
On the bullish side, one camp treated a Fair Value of ₹1,130, a price implied by their AI optimism, as reasonable if ZenAI accelerators and workforce wide GenAI training helped pull in larger, longer contracts and supported higher margins.
The more cautious view anchored around a Fair Value of ₹599, based on the idea that rapid AI adoption could chip away at traditional IT work and client concentration might leave Zensar exposed if a few major customers cut spending.
What The Results Put To The Test For Zensar Technologies
The clearest evidence for Zensar Technologies was the Q1 2027 report. Revenue reached ₹15,083m against ₹13,850m a year earlier and net income moved to ₹1,838m from ₹1,820m. Net margin slipped from 13.1% to 12.2%, so the period gave the bullish revenue story some support but challenged the idea of easy margin expansion from AI.
The useful takeaway is about testable claims. When any technology services stock sells an AI margin story, you can check it directly against reported net margin, not just higher sales or upbeat commentary.
What You Are Really Paying For In Zensar Technologies Today
Today Zensar Technologies trades at ₹538, and this Narrative’s Fair Value sits above the current price based on its own assessment rather than a proven truth.
The Narrative hinges on AI infused delivery and a mega deal led order book. A buyer today would need to believe that Zensar executes these large contracts while keeping margins supported.
"The narrative that Zensar Technologies is undervalued rests on current margins, cash of roughly US$317m to US$322m and the size of the mega deal and large-deal pipeline implying the share price does not fully reflect the earnings power those contracts could support once they are in steady state."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Zensar Technologies
Once you have mapped Zensar Technologies to AI projects, consider the next layer. What quietly keeps all that digital activity running without interruption?
Every model, app and private cloud still relies on computing, storage and resilient connections. That operational need does not hinge on one contract or pricing tier.
Another business concentrates on this less visible plumbing work behind the scenes. It designs hardware and software that help enterprises move information reliably at scale.
Think of it as digital infrastructure instead of a pure chip specialist. If demand for data movement keeps building, its role could quietly matter more.
The case is written up, with the assumptions it depends on. → Discover the AI infrastructure company one Narrative values 85% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com