


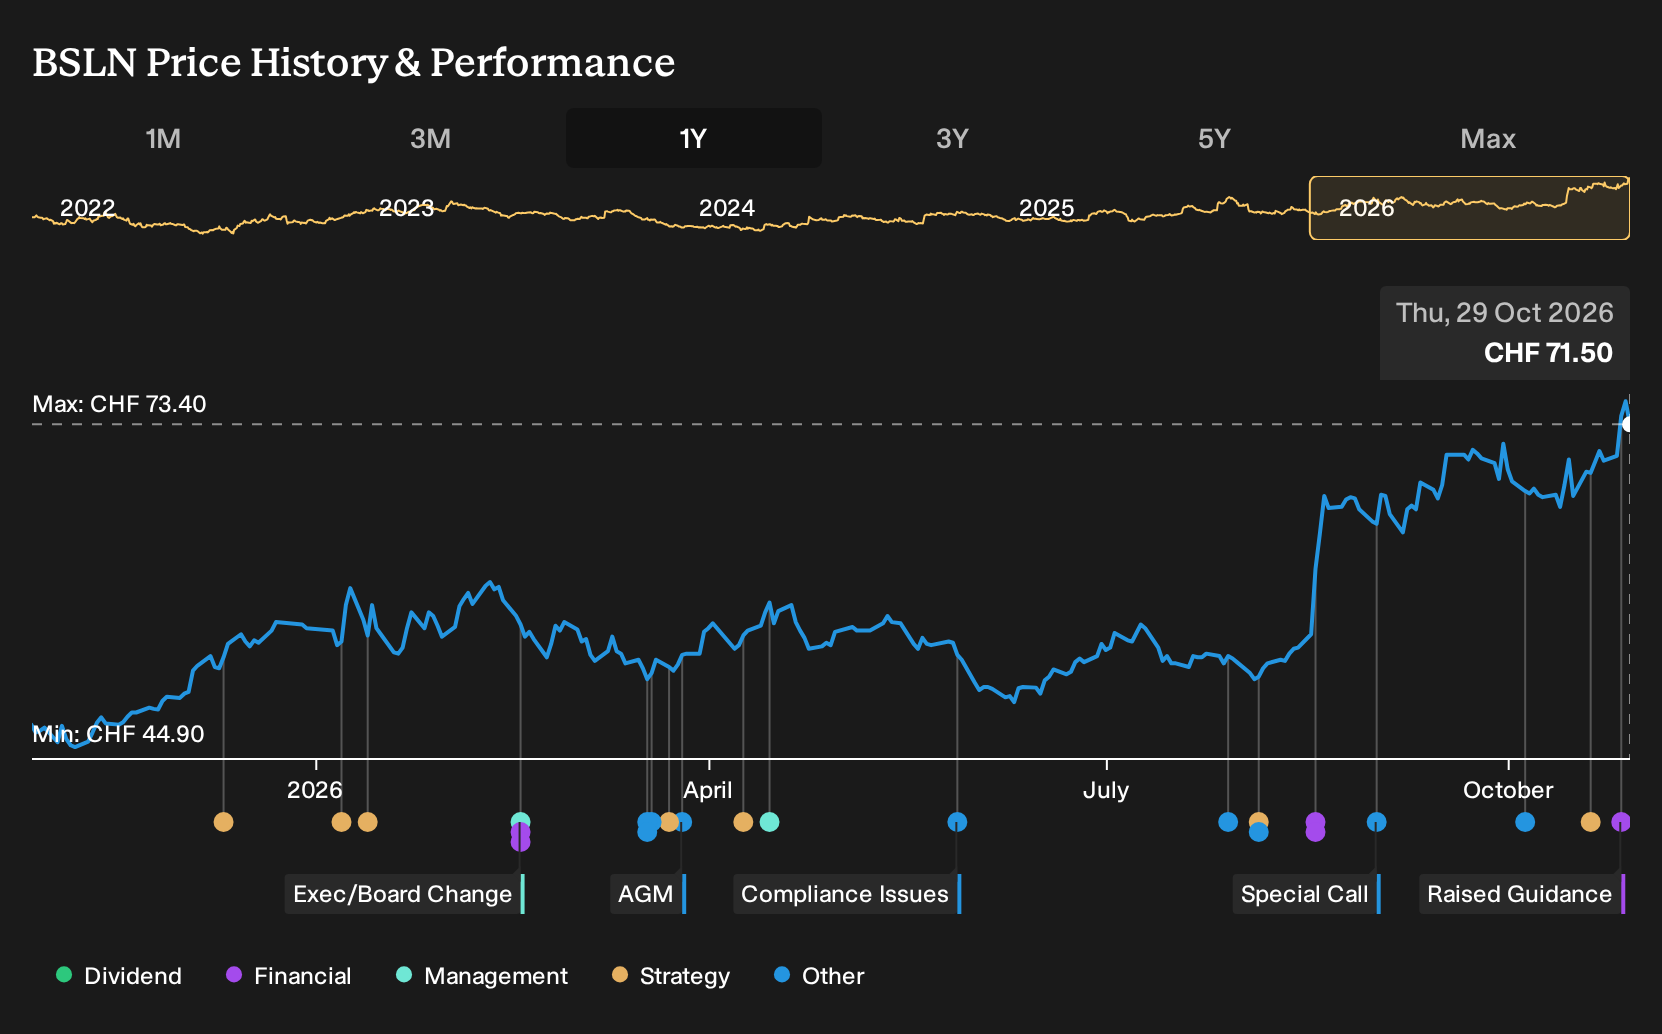
- Basilea Pharmaceutica raised full-year 2026 guidance, now projecting total revenue of CHF 310 million and operating profit of about CHF 115 million, both materially higher than its earlier outlook.
- This guidance reset points to stronger than previously signalled operating momentum, which may reflect firmer demand for key anti-infective products and tighter cost control.
- The focus now turns to how this uplifted 2026 profit outlook could reshape Basilea Pharmaceutica's broader investment narrative.
Scan how Basilea Pharmaceutica’s upgraded 2026 outlook compares with a curated list of solid balance sheet and fundamentals (207 results), which may also be pricing in stronger operating momentum.
Basilea Pharmaceutica Investment Narrative Recap
To own Basilea Pharmaceutica, you need to believe the anti infectives portfolio can offset future pressure from the loss of Cresemba exclusivity after 2027 and from earnings that analysts currently expect to decline over the next three years. The raised 2026 outlook points to firmer operational execution, but it does not remove that cliff risk.
The key near term swing factor remains how Cresemba and Zevtera perform while the firm still has protection and partner support, and whether costs stay disciplined enough to defend margins that already slipped from 30.8% to 21.2%. The biggest risk is any setback or delay across late stage assets like fosmanogepix or ceftibuten ledaborbactam that would limit replacement cash flows.
The most relevant recent development for this upgraded 2026 guidance is the October 20 announcement around extensive new data on fosmanogepix, isavuconazole and ceftobiprole presented at IDWeek 2026. That disclosure keeps attention on whether Basilea Pharmaceutica can convert scientific visibility into durable hospital use alongside Cresemba and Zevtera.
For catalysts, investors will likely watch how these data points influence physician adoption, real world safety perceptions and potential label or guideline decisions over time. The risk is clear. If outcomes, pharmacovigilance analyses or pediatric findings temper enthusiasm for any of these agents, the medium term revenue bridge beyond Cresemba exclusivity could look much weaker.
Basilea Pharmaceutica's analyst narrative points to revenue of CHF 203.3 million and earnings of CHF 12.3 million by 2029, based on a forecast yearly revenue decline of 6.3% and an earnings drop of CHF 40.1 million from CHF 52.4 million today.
Uncover how Basilea Pharmaceutica's fair value indicates a 38% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame fosmanogepix as the real swing factor for Basilea Pharmaceutica, not just Cresemba erosion. Before this guidance hike, they were already modelling CHF 214.4 million of revenue and CHF 10.3 million of earnings for 2029. Those estimates, set ahead of the new outlook, could shift as views evolve.
Explore 2 other Basilea Pharmaceutica fair value estimates, including one that suggests as much as 38% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Basilea Pharmaceutica research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Basilea Pharmaceutica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Basilea Pharmaceutica's overall financial health at a glance.
Looking for more investment ideas beyond Basilea Pharmaceutica?
Once you have a handle on Basilea Pharmaceutica, it can help to compare its setup with other opportunities that share some of the qualities you care about, whether that is balance sheet strength, income potential, or quieter compounders with solid fundamentals.
- If capital preservation sits near the top of your list, start with a 229 resilient stocks with low risk scores that screens for businesses with more resilient profiles.
- For investors who want income on top of potential capital gains, scan a curated set of 228 dividend fortresses that focus on higher yields with an eye on sustainability.
- If you are hunting for under followed opportunities, compare Basilea Pharmaceutica with a hand picked pool of 607 high quality undiscovered gems that pair strong fundamentals with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com