


PDI Gold (ASX:PDI) moved into focus after the company called on shareholders to back its existing board at the 20 November AGM and to oppose external nominee Stephen Mayne.
Recent trading shows that momentum in PDI Gold has been choppy, with the share price rising 2.44% over the last session and 9.38% across seven days, while the 30 day share price return is down 11.21%. However, the 1 year total shareholder return of 52.73% and 3 year total shareholder return of about 3.7x highlight how longer term investors have still seen strong gains as the A$4.20 share price reacts to both production ambitions at Kiniéro and the governance debate ahead of the November AGM.
Scan for other gold producers with similar governance profiles and production ambitions by reviewing our hand picked list of 35 elite gold producer stocks alongside PDI Gold.
After a sharp move and a A$4.20 quote against much higher valuation markers, the gap between market price and fair value estimates on PDI Gold is hard to ignore. How wide does that spread really run?
Most Popular Narrative: 44% Undervalued
The most followed narrative on PDI Gold pins fair value around A$7.44 per share, which sits well above the last close at A$4.20 and presents the current gap as unusually wide for a producer still bedding down a combined West African platform.
The merger with Robex creates a larger platform with two producing mines and the Bankan development project, which can support higher group gold output over time and provide a broader base for revenue and earnings.
Kiniero has moved from commissioning into ramp up, with ore throughput, recoveries and costs that management describes as exceeding plan. If sustained, this can support revenue and margin outcomes versus earlier project assumptions.
See why 3 investors see PDI Gold as 44% undervalued.
Result: Fair Value of A$7.44 (UNDERVALUED)
Still, the PDI Gold story depends heavily on receiving timely permits at Bankan and Mansounia, and on Kiniero sustaining its current operating performance without cost surprises.
Find out about the key risks to this PDI Gold narrative.
Another View: How PDI Gold Screens On Sales
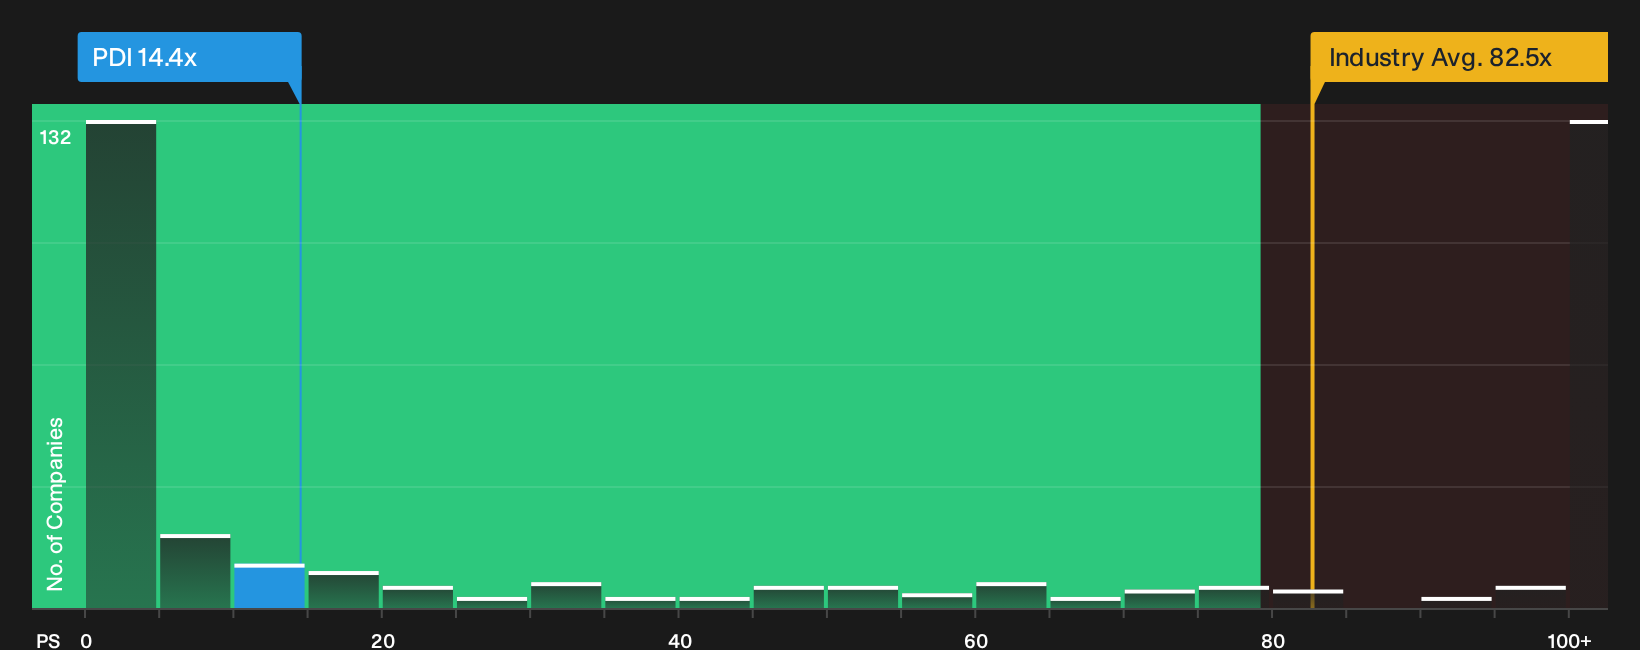
The first narrative leans heavily on fair value and future earnings. A different lens is the current P/S ratio. PDI Gold trades on about 14.4x sales against an estimated fair ratio of 4.4x and an Australian Metals and Mining average near 82.5x, which points to both valuation risk and relative sector support. Which anchor matters more for you at A$4.20?
For a deeper look at how this pricing stacks up against fundamentals over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in PDI Gold’s story so far. If you want to move fast and build your own stance, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond PDI Gold?
Do not stop at PDI Gold. Use the Simply Wall St screener to surface fresh opportunities that match your risk, income, and quality filters in minutes.
- Target potential mispricings by scanning a curated 2 high quality undervalued stocks that pairs quality fundamentals with compressed market expectations.
- Build a steadier income stream by reviewing a focused set of 4 dividend fortresses that aim to combine yield with resilience.
- Sleep easier at night by concentrating on a 6 resilient stocks with low risk scores that filters for stronger balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com