


- Hong Kong’s securities regulator previously approved the city’s first tokenized money market funds for 24/7 secondary trading, now accessible to retail investors through China Asset Management’s products listed on PantherTrade and tradable via Futu Holdings’ Futubull app.
- This move connects Futu Holdings more directly with Hong Kong’s regulated virtual asset infrastructure, linking its core brokerage app to round-the-clock tokenized fund activity and potential client engagement in Web3 products.
- Attention now turns to how Futu Holdings’ investment narrative could be influenced by its role in providing 24/7 access to tokenized fund trading.
Scan how Futu Holdings fits into the broader digital finance shift by lining it up against hand-picked fintech and platform stocks using the 18 high quality undiscovered gems.
Futu Holdings Investment Narrative Recap
Futu Holdings appeals to shareholders who think digital brokerage, wealth products and virtual assets can live inside one tightly integrated app. The tokenized money market access fits that story but does not rewrite it. The near term focus still sits on funded account growth, client asset mix and how much users engage with higher margin products.
The biggest swing factor remains whether trading activity and client assets hold up after a softer patch in new funded accounts. The main operational risk is still regulatory or legal pressure tied to China related business, which could weigh on volumes and profitability more than this tokenization step can offset.
The most relevant development alongside this news is PantherTrade’s full VATP license, which underpins the tokenized fund rollout. That license anchors Futu Holdings inside Hong Kong’s regulated virtual asset framework and supports a wider menu of digital wealth products that can sit next to its traditional brokerage and margin financing services.
Regarding potential catalysts, the VATP license and tokenized products only matter if they help attract higher AUM clients and broaden fee based income beyond pure trading. Execution risk is clear. Management needs to scale Web3 offerings without triggering fresh regulatory scrutiny or distracting from expansion in markets such as Singapore, Japan, Australia and Canada.
Futu Holdings' current analyst narrative focuses on revenues of HK$30.5b and earnings of HK$15.7b by 2029. This corresponds to an assumed 8.3% yearly revenue growth rate and an earnings increase of about HK$4.6b, from HK$11.1b today to the HK$15.7b consensus level in that forecast year.
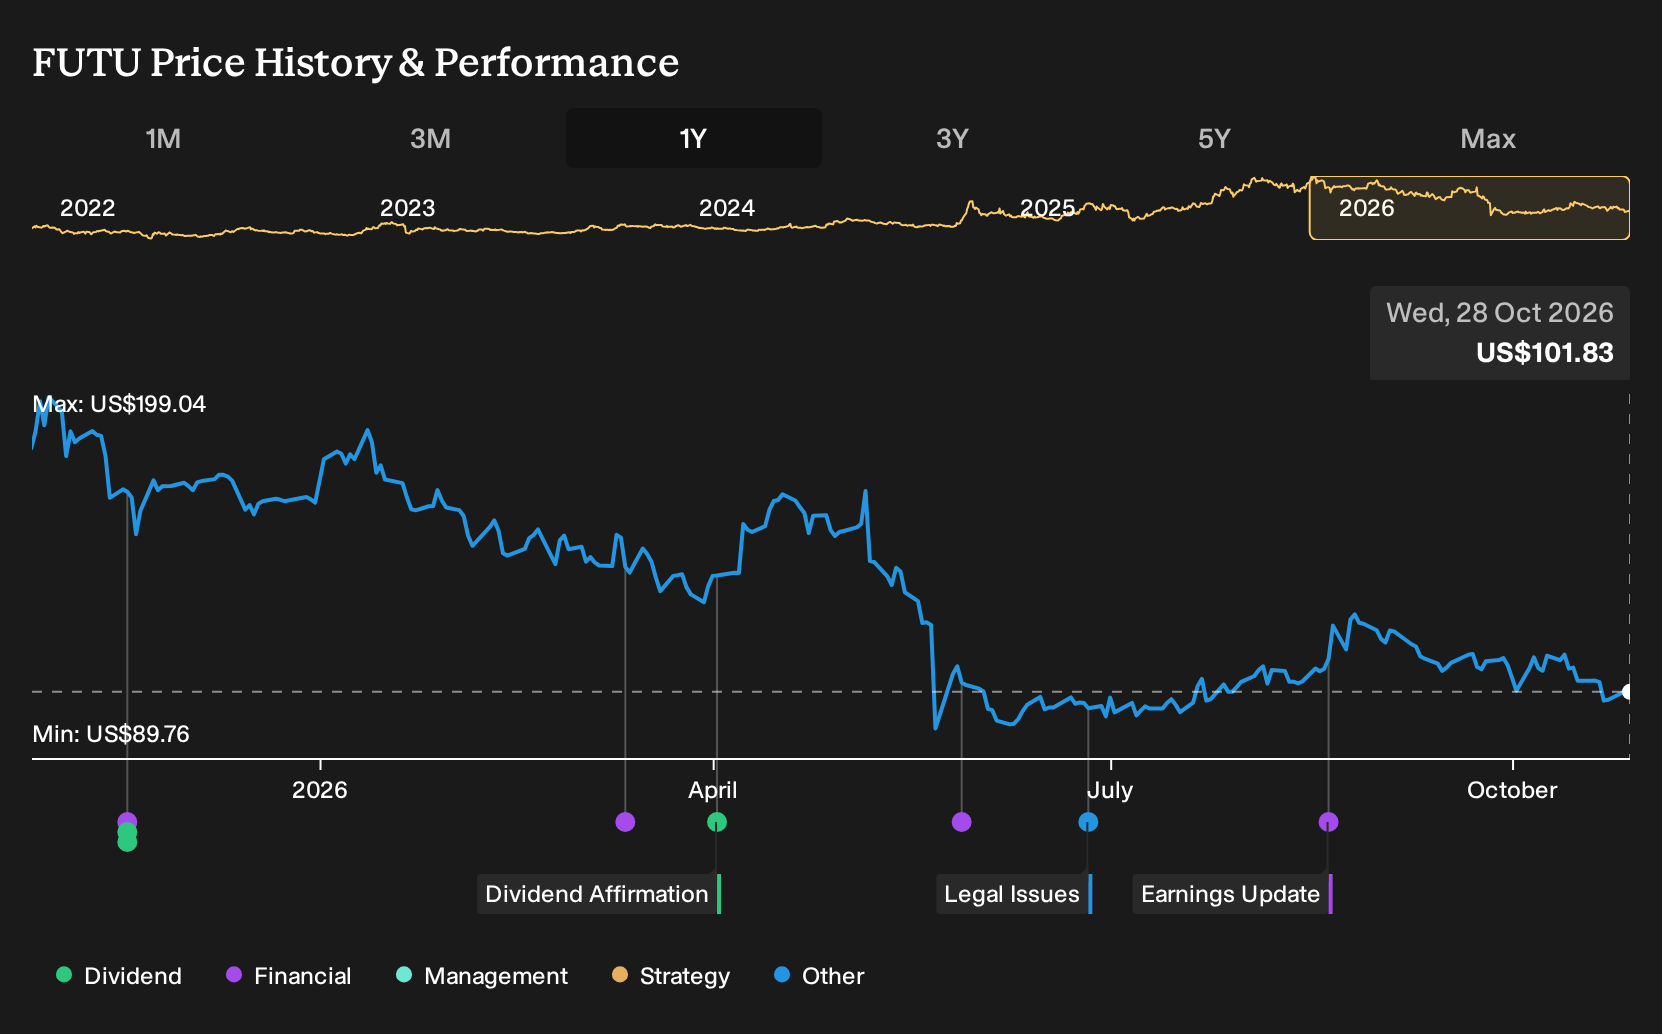
Uncover why Futu Holdings' fair value indicates a 58% potential upside to its current price. This gap could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate view says the bigger swing factor for Futu Holdings is not tokenized funds at all, but whether regulatory pressure keeps earnings closer to the low case of about HK$27.7b in revenue and HK$14.0b in profit by 2029. Those analysts read the same pre news data far more cautiously. Use that spread to test your own assumptions.
Explore 4 other Futu Holdings fair value estimates, including one that suggests it could be worth just $121.88.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Futu Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Futu Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Futu Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Futu Holdings?
Once you have a view on Futu Holdings, it can help to compare that thesis with other stocks that share similar qualities, whether you care most about value, resilience or income potential.
- If you want potential value with quality fundamentals, line up ideas using the 28 high quality undervalued stocks and see which businesses fit your risk and return preferences.
- For investors who care most about balance sheet strength and durability, start with the list of solid balance sheet and fundamentals (23 results) to filter for companies that keep financial risk in check.
- If reliable cash payouts matter to your plan, use the 6 dividend fortresses to focus on stocks offering higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com