


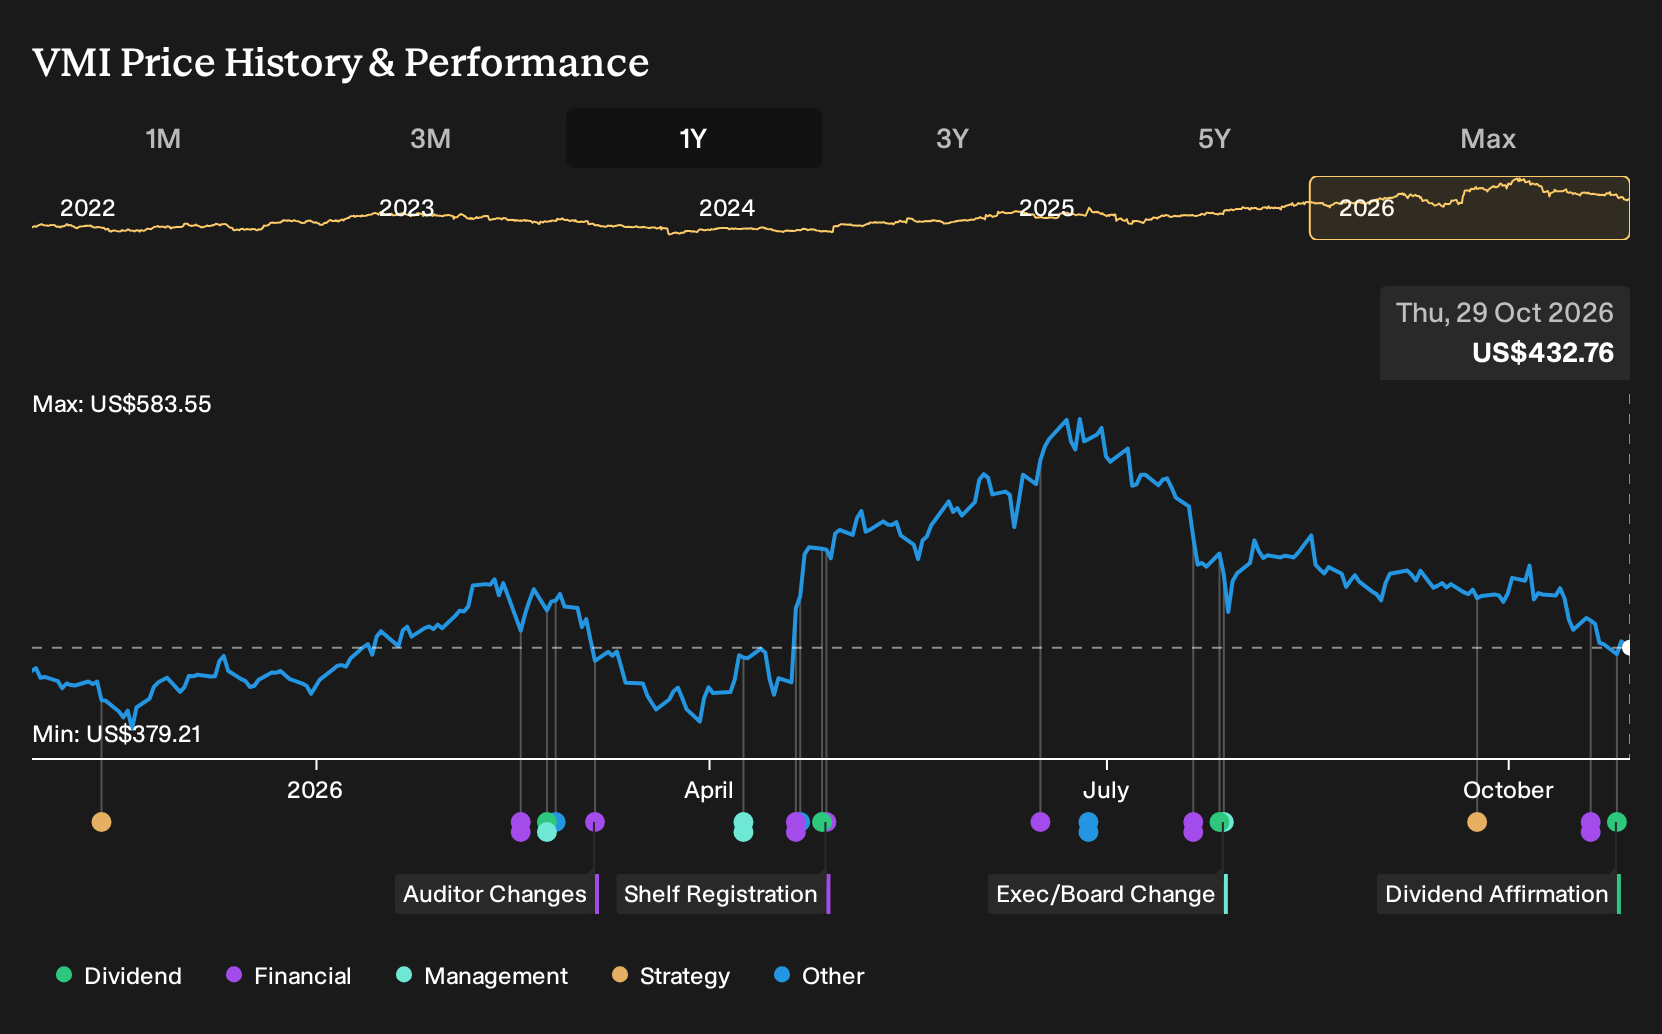
- Valmont Industries reported third quarter 2026 sales of US$1,103.8 million and net income of US$121.05 million, with diluted EPS from continuing operations of US$6.24, and also announced a US$0.77 per share quarterly dividend payable on January 15, 2027.
- The earnings update showed higher sales and earnings for both the quarter and the first nine months versus the prior year, while management reaffirmed full year 2026 net sales guidance of US$4.3b to US$4.45b, indicating confidence in the infrastructure focused order pipeline.
- The focus now turns to how Valmont Industries’ stronger third quarter profitability and raised adjusted earnings guidance may influence the broader investment narrative.
Scan how Valmont Industries fits into the current income story by comparing it with 6 dividend fortresses, which is built around steady cash flows and headline dividend yields.
Valmont Industries Investment Narrative Recap
For a shareholder in Valmont Industries, the big picture is about turning long term utility and infrastructure demand into steady, high margin earnings, while keeping input costs and execution under control. The third quarter numbers and higher adjusted earnings guidance point to an operation that is handling that balance for now. The near term swing factor remains how quickly utility projects convert from the US$6.7b pipeline into realized, profitable revenue.
On the risk side, raw material and freight inflation, plus weak telecom structures demand, still hang over the story. The recent earnings beat does not remove that exposure, especially given the lag in pricing through higher steel, zinc and diesel costs. If those pressures persist, they could offset some of the progress in infrastructure margins over the next few quarters.
The reaffirmed full year 2026 net sales outlook of US$4.3b to US$4.45b is the announcement that ties most directly to this earnings release. Management is effectively saying the order book and execution pace are strong enough to stick with the existing top line range after a quarter where infrastructure and coatings were key contributors.
For you, that guidance matters more than the usual quarterly noise, because it links directly to the utility capacity expansions and Agriculture margin work already under way. The January 2027 dividend of US$0.77 per share then sits on top of this operational story as a use of cash that depends on continued delivery against those revenue and profitability targets, rather than driving them.
Valmont Industries' narrative projects US$5.1b revenue and US$550.5 million earnings by 2029. This builds in 6.8% yearly revenue growth and a US$44.8 million earnings increase from US$505.7 million today.
Discover why Valmont Industries' fair value indicates a 44% potential upside to its current price, a gap that could narrow faster than many investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$335 to about US$637, so some contributors see Valmont Industries as heavily underpriced, while others lean toward a richer valuation. Set that spread against rising raw material and freight costs, and you get a reminder that opinions can diverge sharply. Explore those different viewpoints before deciding how this dividend and earnings story fits your own portfolio goals.
Explore 2 other Valmont Industries fair value estimates, including one that suggests as much as 23% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Valmont Industries research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Valmont Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valmont Industries' overall financial health at a glance.
Looking for more Valmont Industries sized investment ideas?
If the Valmont Industries story has you thinking about income, resilience, or underappreciated quality, use that curiosity to widen your opportunity set with the Simply Wall St Screener.
- For investors who care about dependable cash returns, compare Valmont Industries' payout profile against a broader universe of income opportunities with 6 dividend fortresses.
- If capital protection is high on your list, broaden your watchlist with 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- When you want to hunt for underfollowed quality, scan beyond well known tickers by reviewing 18 high quality undiscovered gems that combine solid fundamentals with quieter coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com