


In October 2026, the Asian markets have been navigating a landscape marked by volatility due to rising oil prices and concerns over AI-related expenditures, with small-cap stocks showing resilience amidst these challenges. As investors seek opportunities in this dynamic environment, identifying stocks that demonstrate strong fundamentals and adaptability to shifting market conditions becomes crucial for uncovering potential gems.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Shengda ResourcesLtd | 44.63% | 9.29% | 15.82% | ★★★★★☆ |
| Shandong Head GroupLtd | 48.27% | 6.77% | -13.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Infore Environment Technology Group | 28.47% | 4.58% | -7.19% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Ta Tun Electric Wire & Cable | 70.16% | 6.67% | 33.41% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
Bank of Qingdao (SEHK:3866)
Simply Wall St Value Rating: ★★★★★★
Overview: Bank of Qingdao Co., Ltd. offers personal and corporate banking as well as financial market services in the People’s Republic of China, with a market cap of HK$37.65 billion.
Operations: The bank generates revenue primarily through interest income from loans and advances, alongside fees and commissions from its financial services. Its cost structure includes interest expenses on deposits and borrowings, which significantly impact profitability. The net profit margin is a critical indicator of financial health, reflecting its ability to manage costs relative to revenue generation.
Bank of Qingdao, with total assets of CN¥874.6 billion and equity of CN¥57.9 billion, offers a compelling profile in the banking sector. It has a robust deposit base of CN¥600.7 billion and loans totaling CN¥432.3 billion, demonstrating solid operational footing. The bank's earnings grew by 17% over the past year, surpassing industry growth rates significantly at 8%. Moreover, it maintains an appropriate level of bad loans at just 0.9%, supported by a sufficient allowance for bad loans at 336%. Trading well below its estimated fair value by about 53%, this entity is positioned attractively against peers in its field.

VSTECS Holdings (SEHK:856)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: VSTECS Holdings Limited is an investment holding company that develops IT product channels and offers technical solution integration services across North Asia and Southeast Asia, with a market capitalization of approximately HK$11.15 billion.
Operations: The company's revenue streams are primarily derived from Enterprise Systems, generating HK$56.07 billion, followed by Consumer Electronics at HK$43.37 billion and Cloud Computing at HK$5.29 billion.
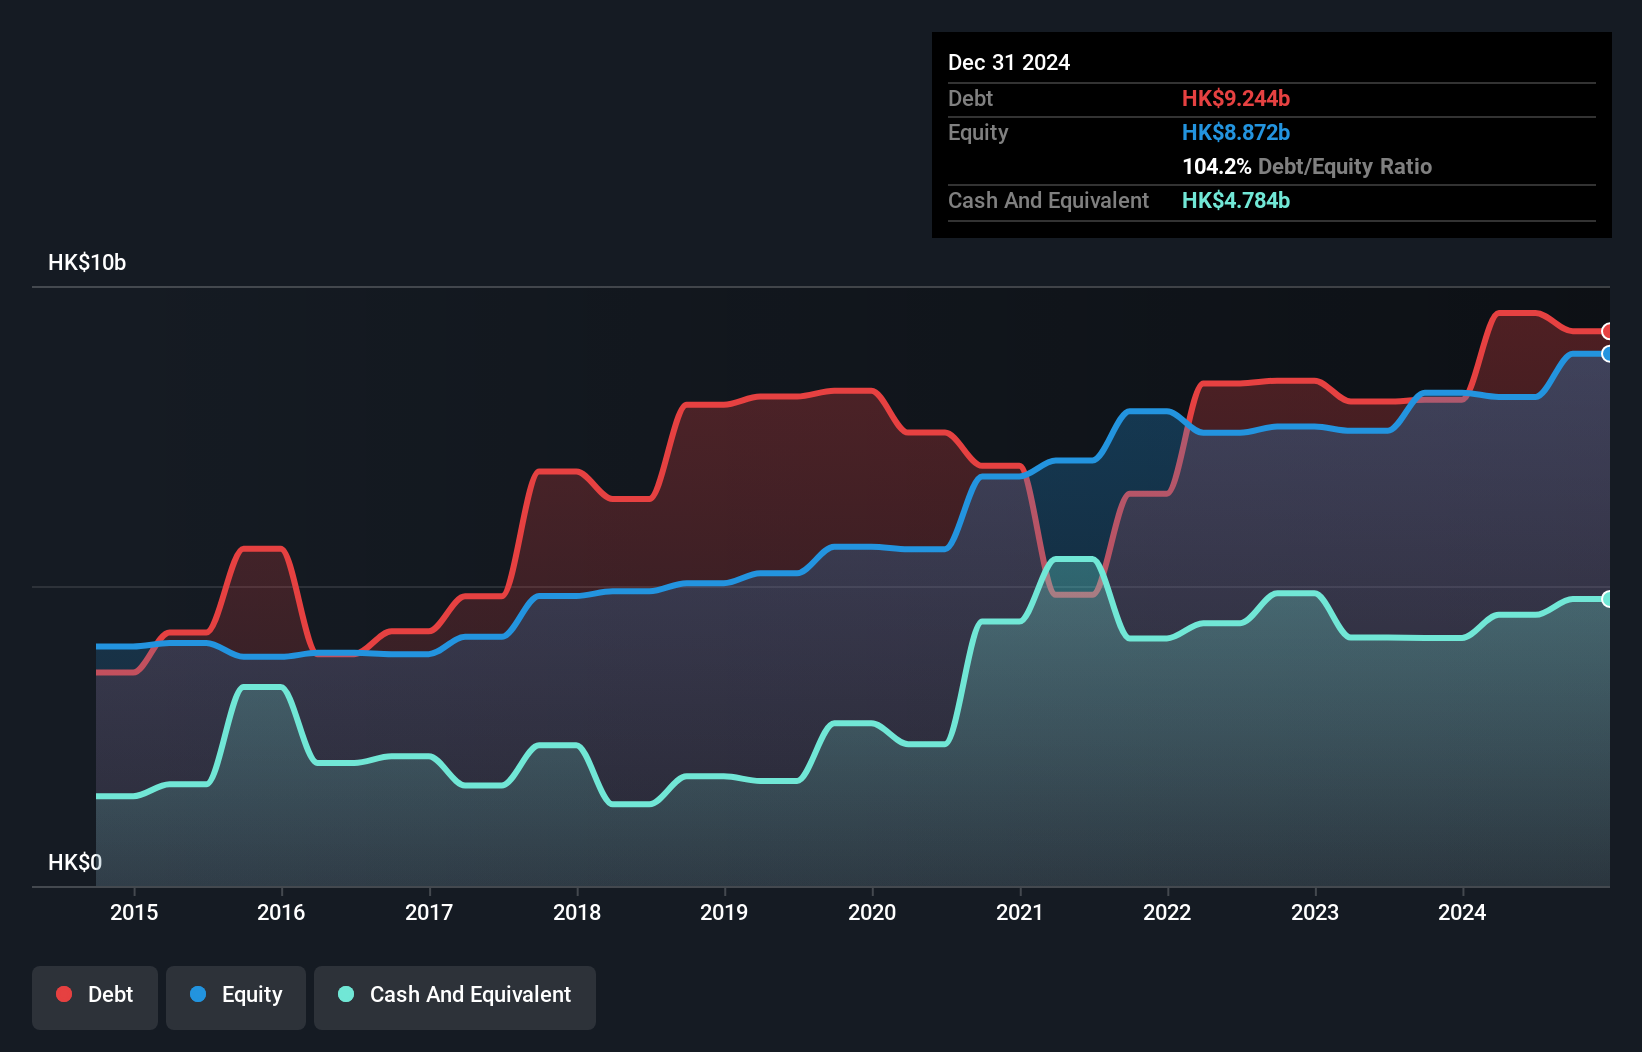
VSTECS Holdings is making waves in Southeast Asia's digital transformation, with a strong foothold in IT infrastructure and cloud solutions. Recent earnings for the half-year ending June 2026 showed sales of HK$52.61 billion, up from HK$45.52 billion last year, and net income increased to HK$914.91 million from HK$610.47 million previously. Basic earnings per share rose to HKD 0.66 from HKD 0.44 a year ago, reflecting solid growth despite challenges like competition and geopolitical risks. Analysts project annual revenue growth of 12%, though profit margins may dip slightly due to market dynamics and strategic shifts by vendors.
FreeBit (TSE:3843)
Simply Wall St Value Rating: ★★★★★☆
Overview: FreeBit Co., Ltd. operates as a supporting Internet and broadband business company with a market cap of ¥42.55 billion.
Operations: FreeBit generates revenue primarily from its Internet and broadband services. The company's financial performance includes a market cap of ¥42.55 billion, reflecting its position in the industry.
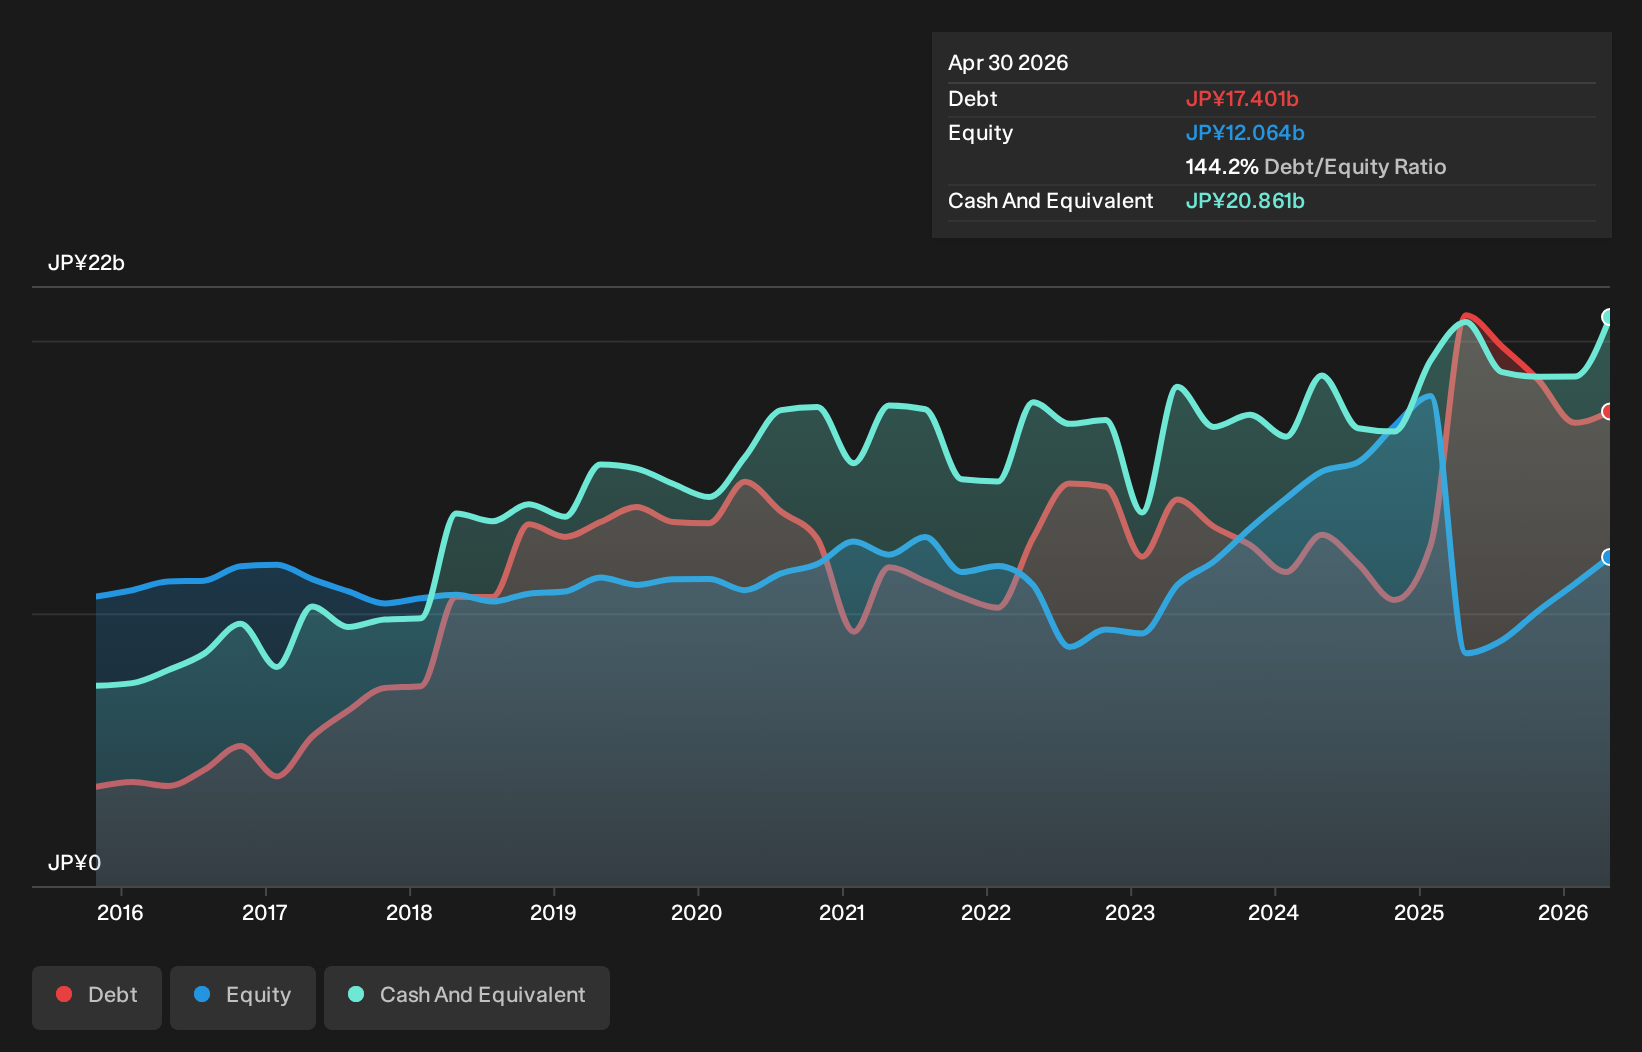
Recent developments at FreeBit highlight its dynamic nature, with earnings growth of 51% over the past year surpassing the Telecom industry average of 18%. The company is trading at a value perceived to be 52% below its fair estimate, suggesting potential for investors. However, internal challenges have emerged following an investigation into acquisition practices and compliance issues involving former CEO Mr. Ishida. Despite these hurdles, FreeBit's interest coverage ratio stands strong at 38x, indicating robust financial health amidst executive changes and delayed earnings announcements due to ongoing investigations.
- Delve into the full analysis health report here for a deeper understanding of FreeBit.
Gain insights into FreeBit's past trends and performance with our Past report.
Make It Happen
- Click here to access our complete index of 135 Asian Undiscovered Gems With Strong Fundamentals.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com