


In recent weeks, the Asian markets have experienced a notable shift in sentiment, with small-cap stocks showing resilience amid global volatility and concerns over AI investment spending. As investors seek opportunities to diversify and strengthen their portfolios, identifying small-cap companies that exhibit strong fundamentals and insider confidence can be particularly appealing in this dynamic environment.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.9x | 21.27% | ★★★★★★ |
| Charter Hall Long WALE REIT | 8.7x | 12.4x | 38.22% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.7x | 0.9x | 40.59% | ★★★★★☆ |
| Centurion | 15.6x | 3.0x | 20.96% | ★★★★☆☆ |
| Australian Finance Group | 8.2x | 0.3x | 9.92% | ★★★★☆☆ |
| Universal Robina | 11.8x | 0.7x | 26.62% | ★★★★☆☆ |
| Clover | 15.8x | 1.7x | 48.52% | ★★★☆☆☆ |
| Citicore Energy REIT | 12.6x | 9.6x | 30.05% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 107.4x | 3.1x | 44.95% | ★★★☆☆☆ |
| Cettire | NA | 0.2x | 4.73% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
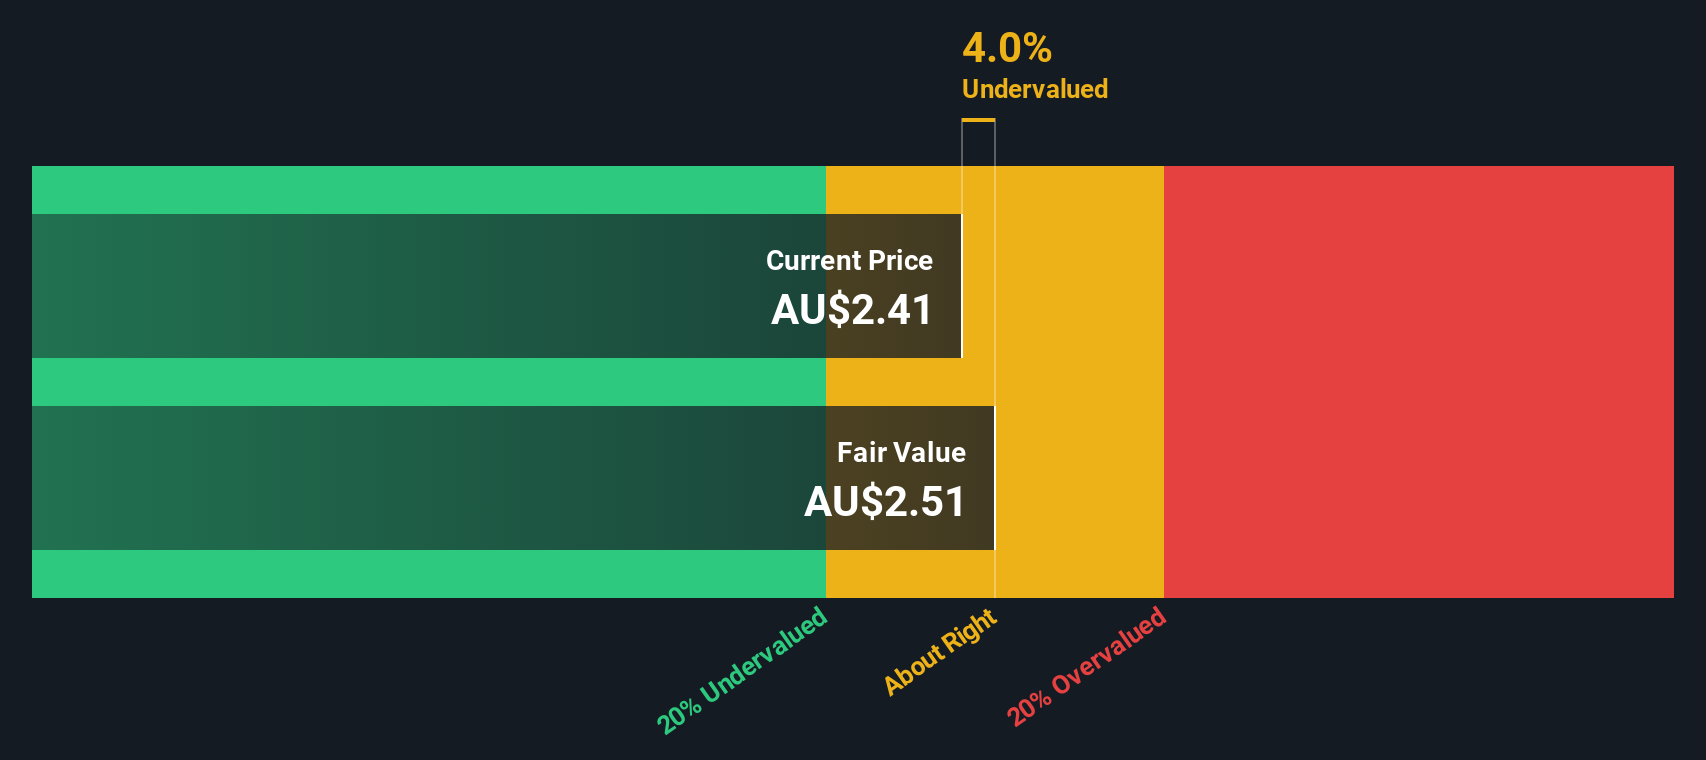
Cogstate (ASX:CGS)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Cogstate is a company that specializes in cognitive science and technology, focusing on providing solutions for clinical trials and healthcare, with a market cap of A$0.23 billion.
Operations: Cogstate generates revenue primarily from its Clinical Trials segment, accounting for $58.37 million, and a smaller portion from Healthcare services at $2.50 million. The company's net income margin has shown variability, with recent figures around 0.19%. Operating expenses are significant, with General & Administrative costs being a major component. The gross profit margin has fluctuated over time but recently stands at approximately 57.53%.
PE: 34.7x
Cogstate, a small company in Asia, showcases potential with its recent financial performance and strategic outlook. Reporting a net income increase to US$11.9 million for the year ending June 2026, it also announced an annual dividend of A$0.04 per share. Insider confidence is evident as executives have been purchasing shares over the past year, reflecting their belief in future growth prospects. With projected revenue growth and strong earnings visibility for FY27, Cogstate's focus on technology and capital allocation could enhance its market position amidst positive industry conditions.
- Take a closer look at Cogstate's potential here in our valuation report.
Review our historical performance report to gain insights into Cogstate's's past performance.
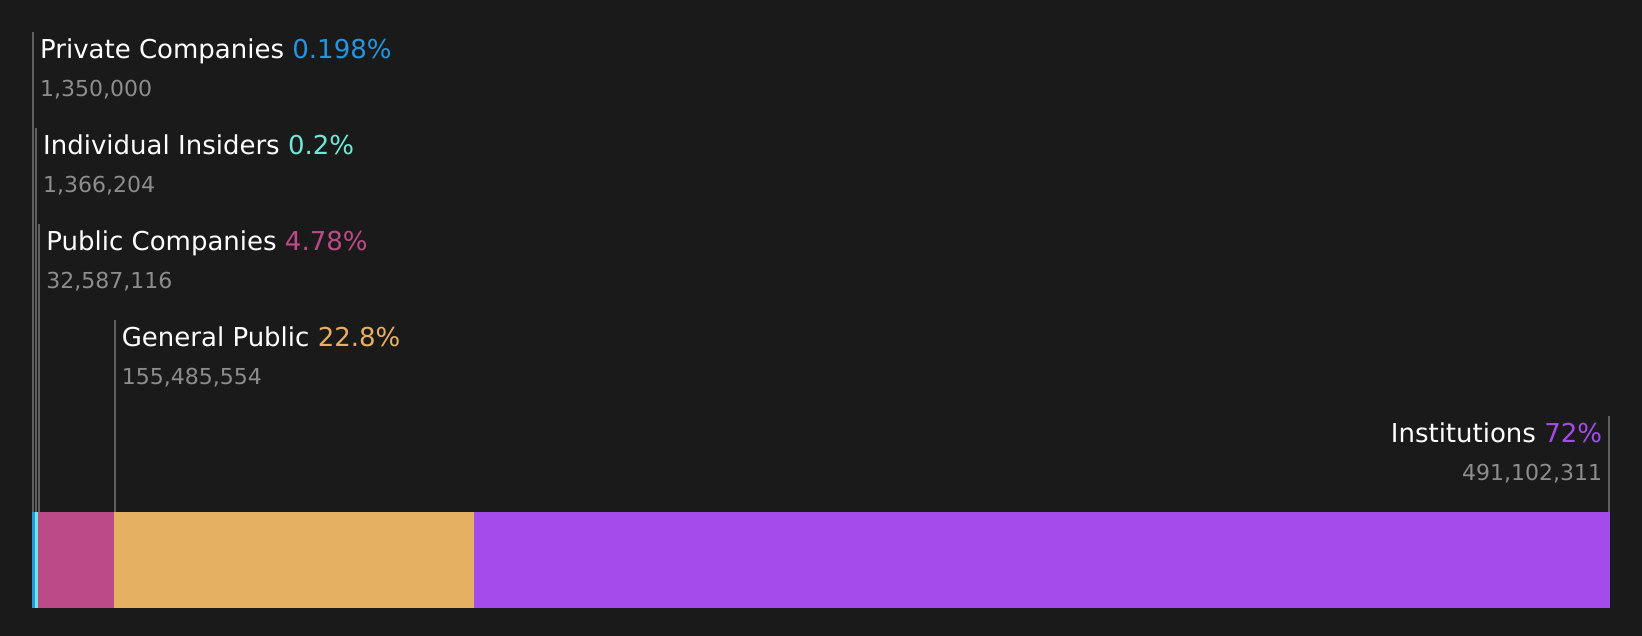
Lendlease Group (ASX:LLC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Lendlease Group is a global property and infrastructure company with operations spanning development, investments, and construction, boasting a market capitalization of A$6.60 billion.
Operations: Lendlease Group generates its revenue primarily from Construction (A$3.87 billion), followed by Development and Capital Release Unit segments. The company experienced fluctuations in its net income margin, with a notable decline to -13.80% by June 2026, influenced by increased non-operating expenses. Gross profit margin showed variability over the years, reaching 8.05% in the same period. Operating expenses have been significant across periods, impacting overall profitability despite diverse revenue streams.
PE: -2.1x
Lendlease Group, a smaller player in the Asian market, has seen insider confidence with share purchases over the past year. Despite reporting a net loss of A$749 million for the year ending June 2026, there's optimism as earnings are forecast to grow by 80.67% annually. Recent board changes include Gary Lennon joining as an independent director from November 2026, bringing strategic expertise. Upcoming amendments to company bylaws may signal strategic shifts at their November meeting.
- Get an in-depth perspective on Lendlease Group's performance by reading our valuation report here.
Gain insights into Lendlease Group's past trends and performance with our Past report.
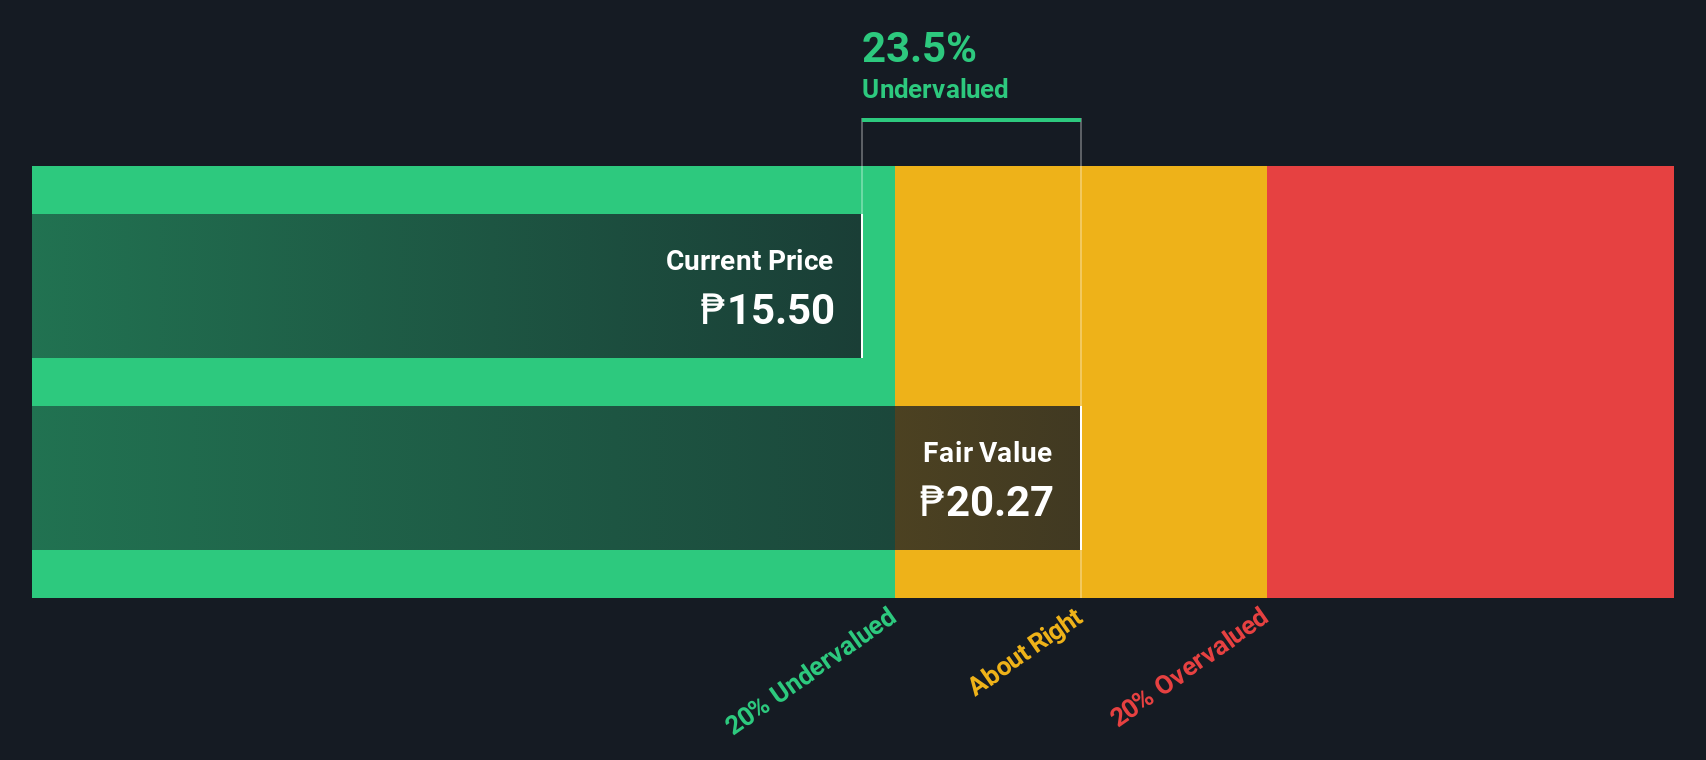
Maynilad Water Services (PSE:MYNLD)
Simply Wall St Value Rating: ★★★★★★
Overview: Maynilad Water Services operates as a provider of water and wastewater services, with a market cap of ₱12.34 billion.
Operations: The company's primary revenue stream is from water and wastewater services, generating ₱37.41 billion in the latest period. The cost of goods sold amounted to ₱5.24 billion, resulting in a gross profit margin of 85.99%. Operating expenses are significant, with general and administrative expenses contributing notably to the total operating costs of ₱10.08 billion. Net income reached ₱16.26 billion, reflecting a net income margin of 43.48%.
PE: 7.8x
Maynilad Water Services, a key player in the water utility sector, recently reported a rise in six-month revenue to PHP 19.11 billion from PHP 18.35 billion last year, reflecting solid financial performance despite challenges. However, its reliance on external borrowing poses risks due to higher liability exposure without customer deposits. The company's strategic move into New Clark City through a public-private partnership with K-Water could enhance growth prospects over the next 25 years if successful.
Turning Ideas Into Actions
- Gain an insight into the universe of 63 Undervalued Asian Small Caps With Insider Buying by clicking here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com