


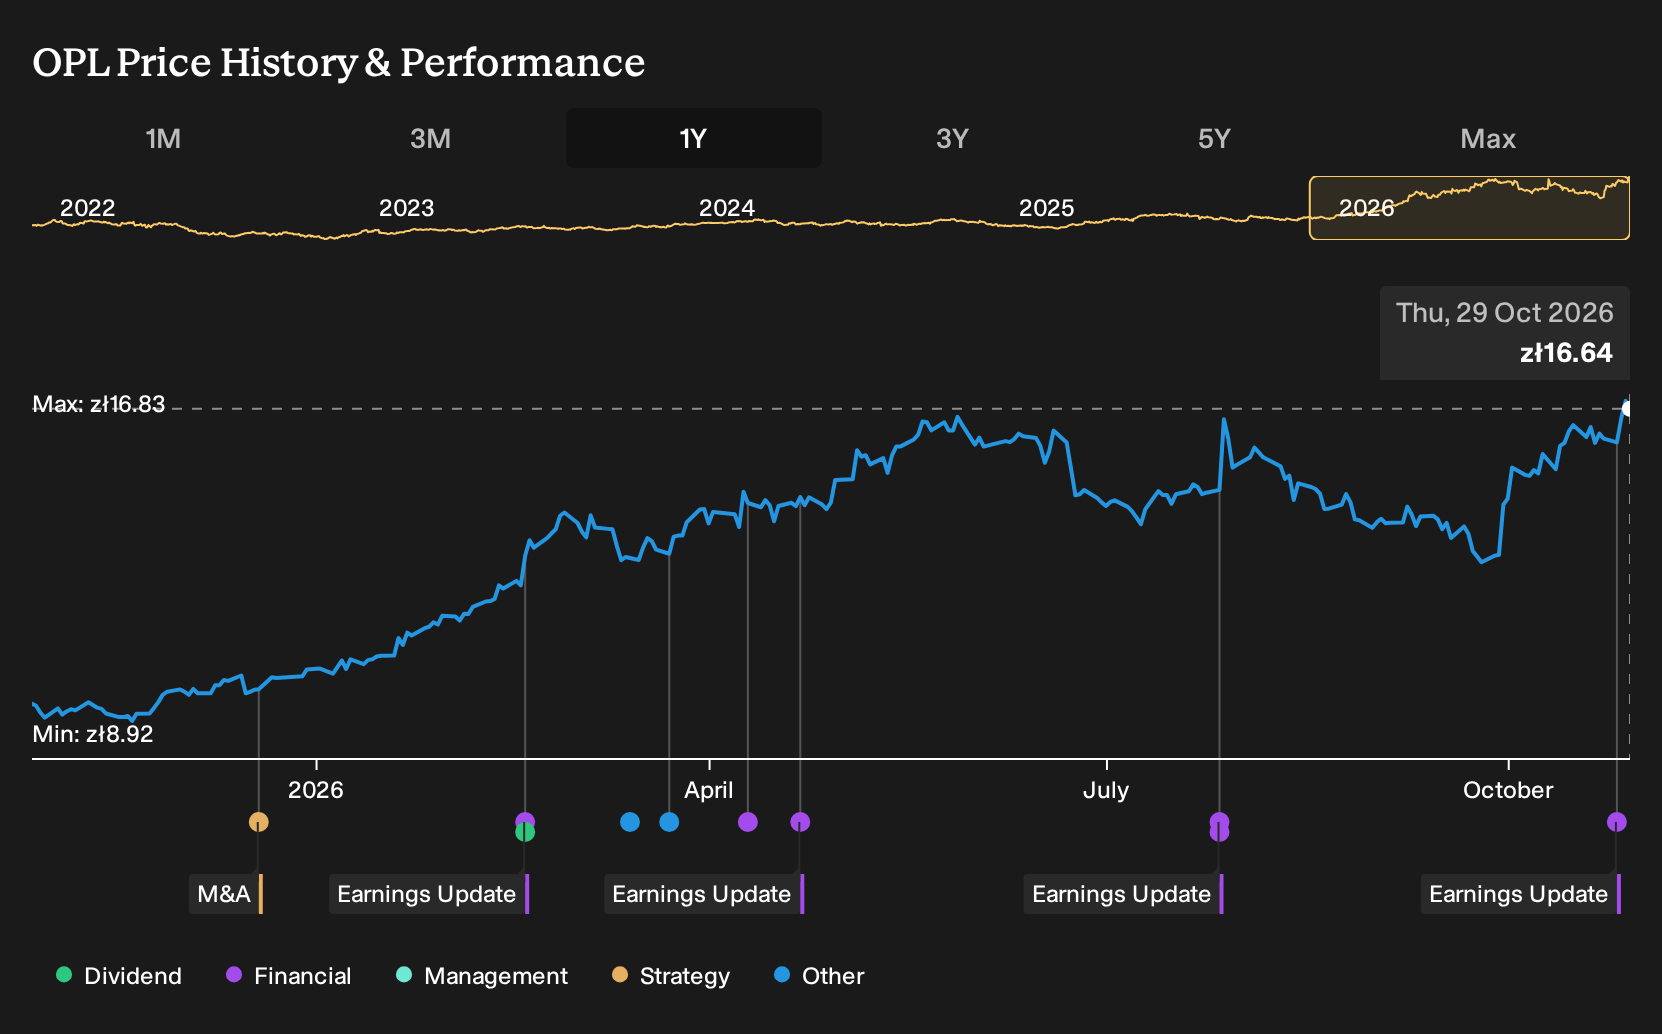
If you only skimmed Orange Polska headlines, the FiberCo joint venture and ongoing fiber rollout might have sounded like just another infrastructure story. Holding Orange Polska over the past year would have returned 89.8%, including dividends. If you had been weighing a purchase a year ago, you would have needed to believe those network investments and digital bets justified that kind of outcome. Were the Q2 2026 results enough to support that belief, or did buyers expect something even stronger?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Orange Polska. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Orange Polska Investors Were Weighing
The shares cost PLN9.29 at the start of the period, and anyone looking at Orange Polska had to choose which story felt more realistic.
The bullish narrative put fair value at PLN10.8 and leaned on accelerating fiber and 5G rollout. It assumed the network build and digital services could support 3.5% annual revenue growth and a profit margin move from 7.2% to 8.7% by 2028.
The bearish view anchored fair value at PLN6.1 and focused on demographic pressure and legacy decline. It assumed only 2.1% yearly revenue growth and argued that high capital needs for fiber and 5G would keep free cash flow under strain.
What The Orange Polska Results Actually Tested
The cleanest datapoint was Orange Polska lifting total revenue from PLN3,158m in Q2 2025 to PLN3,500m in Q2 2026, which supported a bullish narrative that assumed healthier top line trends. Net income also moved up from PLN274m to PLN281m. The catch is that net margin slipped from 8.7% to 8.0%, so the evidence pointed in both directions.
The whole debate focused on profitable growth, not just higher sales. When you review another telecom, check whether net income and the margin on that profit move in step with any revenue increase before placing too much weight on a growth-led thesis.
What Orange Polska's Price Already Assumes After The Run
Orange Polska now trades at PLN16.64, well above where the past year began. This Narrative’s Fair Value sits below that level based on its own modelling. The key tension is not whether the business is viable, but how much of its current execution story is already in the quote.
The selected Narrative argues that a buyer today is effectively assuming steady postpaid ARPU gains, convergence momentum and project driven cash generation keep holding up. The real question is how those moving parts behave if competition, weaker project flow or cost creep hit at the same time.
"The main thing that has to go right is that Orange Polska needs to keep turning strong core telecom, IT&IS and wholesale performance, together with flat indirect costs, into recurring EBITDAaL and organic cash flow growth. The current numbers, including guidance for low to mid single digit revenue growth, EBITDAaL growth above 6% and organic cash flow of at least PLN 1.2b in 2026, imply a share price that already reflects continued execution without major setbacks."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Past Orange Polska
Once you understand Orange Polska, you start noticing other network stories. One sits far above cell towers, focused on space, satellites and computing power.
Telecoms fight for coverage on the ground. This other business pursues a similar goal in orbit and low Earth skies.
Its satellites aim to provide broadband and direct connections to regular phones. The same group is also putting effort into AI hardware and software.
Those pieces link into one infrastructure stack that is still taking shape. If that buildout works, its role in connectivity and computing could look very different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 44% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com