


Everest Group just released Q3 2026 numbers and the stock rose 3.5% to US$400.59 by the close. The move appears driven more by emotion than detail. Investors saw a headline beat on after tax operating earnings per share of US$7.62 and bought the stock. The twist is that this rally arrived in a quarter defined by a heavy Casualty reserve build of about US$600m and wider loss costs, which squeezed profitability far more than the price action suggests.
Love Everest Group's underwriting reach but worried about large reserve swings and loss costs eating into earnings quality? Check out the list of solid balance sheet and fundamentals stocks (22 results) for insurers and financial stocks that pair disciplined reserving with stronger balance sheet support.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$3,713m vs. US$4,348m (down 14.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$233m vs. US$252m (down 7.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$6.12 vs. US$6.09 (up 0.5%)
- Combined Ratio (Q3 2026 vs. Q3 2025, group level): Not disclosed vs. 103.4% (prior period reference only, driven by elevated loss activity in 2025)
Everest Group chose to book reserves far above its own estimates. Ask Charlie what Everest Group’s $850m reserve buffer really signals.
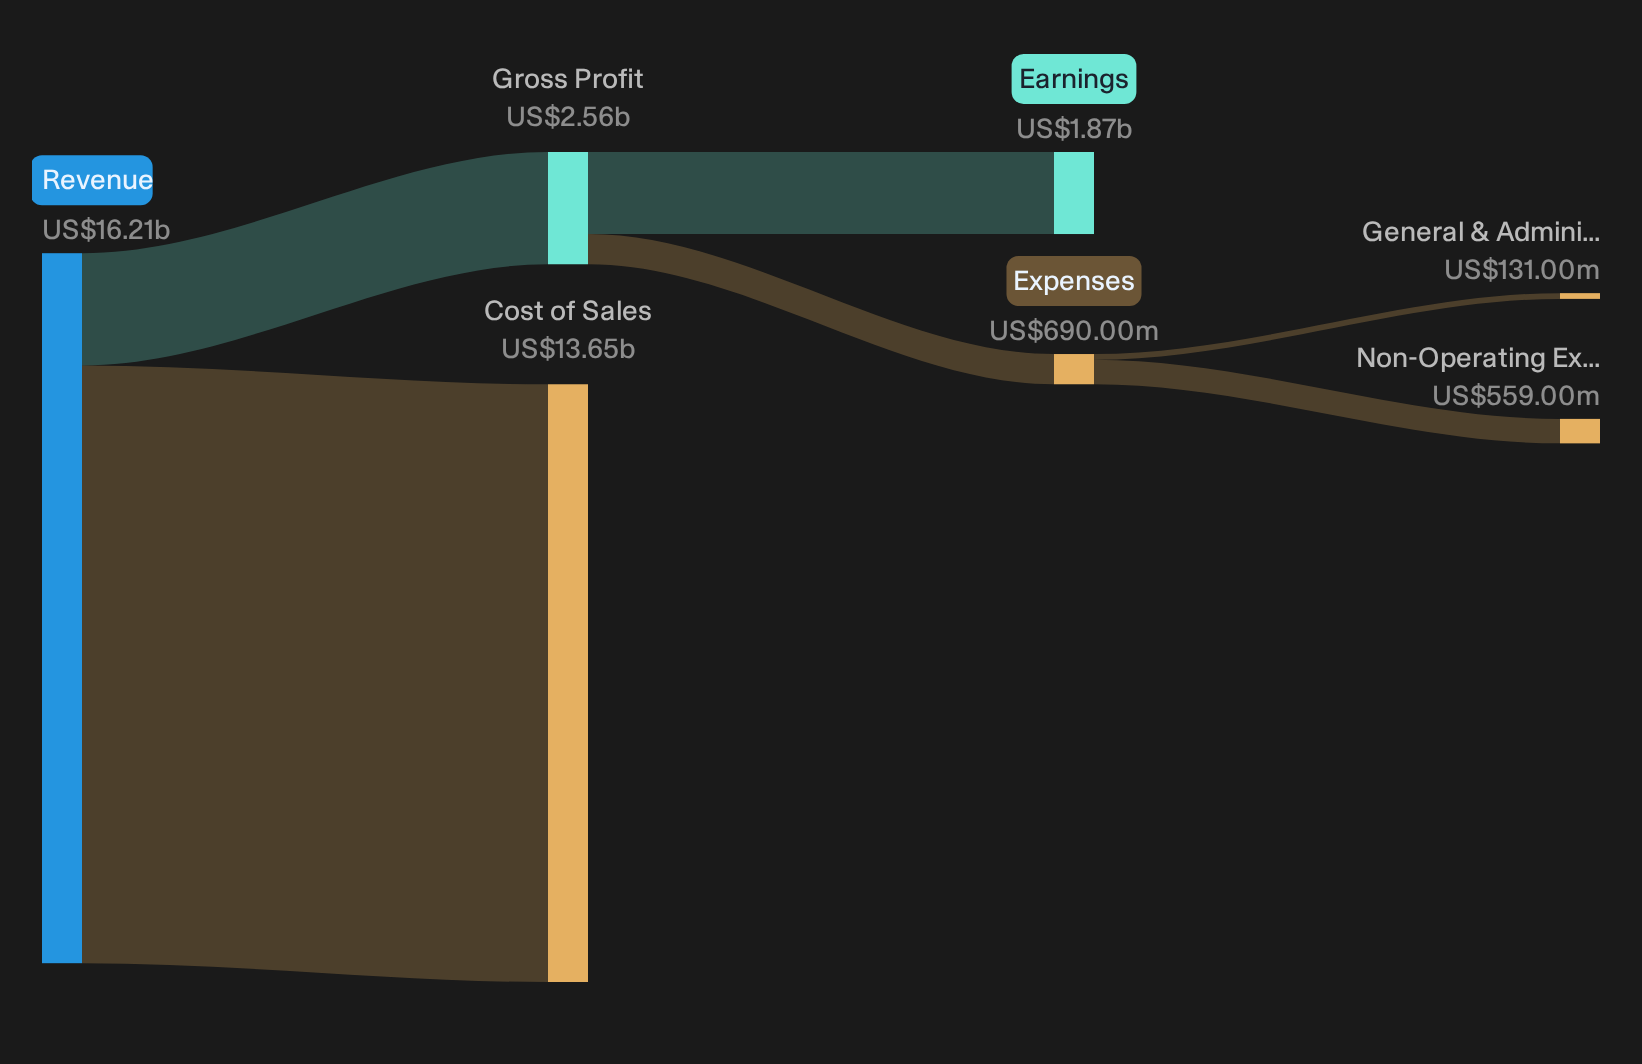
Everest Group: Testing The Capital And Mix Shift
The bullish pitch is that Everest Group can reshape its portfolio and still keep returns intact. The key claim centers on underwriting mix and capital tools.
"Everest Group is reshaping its portfolio toward short tail property, specialty lines and selected international business while reducing U.S. casualty writings by over US$1.2b since 2024. This shifts earned premium toward areas that have recently supported a 90% combined ratio across core operations and can influence future net margins and earnings quality."
Q3 shows partial follow through. Core gross written premium of US$3.7b is lower, with reinsurance treaty down and U.S. casualty pulled back. Global Wholesale & Specialty still posts a 97.3% combined ratio and better attritional losses, yet group profitability is pressured by reserve actions and catastrophe losses, so the cleaner mix is not yet translating into cleaner earnings.
Everest Group: Reserve Risk Still Pulls Against Upside
The bear case focuses on casualty reserves and Legacy runoff as persistent drags on Everest Group.
"Everest Group increased its North America casualty treaty reserves by just under US$200m and raised its Baltimore Bridge collapse reserves by about US$55m, which signals persistent elevated loss trends in older accident years and a risk that future reserve additions could again absorb earnings and reduce net income and book value growth."
Q3 developments support that concern. Management strengthened Casualty reserves by about US$600m and recorded roughly US$268m of net unfavorable development. Earnings of US$233m and revenue of US$3,713m both fell short of expectations. Legacy remains a drag with several years of runoff ahead. Securities class actions tied to past reserving add legal and reputational overhang even as management now books US$850m above actuarial central estimates.
One Narrative disagrees with today's price. → See where this Narrative says Everest Group should trade.
Hunt For Stronger Balance Sheets
Everest Group just reminded investors that reserves and loss costs can quickly affect headline earnings. The real opportunity could be in finding stocks that could be low debt before the market corrects them.
- Company 1 - 23% below our estimate - embeds AI assistants into workplace tools so enterprise customers shift workflows onto its cloud stack.
- Company 2 - 32% below our estimate - supplies chips and software stacks data center operators use when expanding AI capacity faster than power infrastructure.
- Company 3 - 43% below our estimate - converts a record backlog of technology-heavy data center builds into modular projects that keep mechanical and electrical crews busy.
Three companies from the same screener. Open every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com