


- UCB reported that the FDA approved a once daily, self administered ZILBRYSQ autoinjector for adult gMG patients who are anti AChR antibody positive, adding to the existing prefilled syringe option.
- The new autoinjector, supported by bioequivalence data and high satisfaction scores, may influence ZILBRYSQ treatment adherence, device related costs and long term patient support models for UCB.
- We will now assess how UCB's investment narrative might evolve as the ZILBRYSQ autoinjector broadens self administration options for gMG patients.
UCB Investment Narrative Recap
To own UCB, you need to believe the company can keep shifting its mix toward higher value neurology and immunology drugs while managing U.S. pricing pressure and loss of exclusivity on older products. The ZILBRYSQ autoinjector fits that story only modestly, by broadening a recent rare disease launch rather than moving the profit needle on its own.
The near term focus still sits on BIMZELX execution, rebate intensity in the U.S. and whether new modalities progress cleanly through late stage trials. The biggest risk remains high R&D spend tied to a concentrated pipeline. If uptake or trial outcomes disappoint, earnings and margin ambitions could come under strain.
The ZILBRYSQ autoinjector approval most directly connects to UCB's broader push into higher margin biologics and disease modifying therapies. It shows the group working to make complex treatments more usable, which matters for real world adherence and can influence how efficiently fresh launches offset revenue pressure from generic erosion in products such as BRIVIACT.
For catalysts, this device option sits alongside larger drivers such as BIMZELX and the neurology and immunology pipeline, including programs such as galvokimig, ATG 201 and rezanecel. Execution risk is similar. Each asset needs clean data, timely approvals and practical uptake to justify current earnings growth expectations and the investment into manufacturing and AI enabled support infrastructure.
UCB's current analyst narrative points to €11.4 billion in revenue and €3.3 billion in earnings by 2029, based on 10.2% yearly revenue growth and an earnings increase of about €1.1 billion from €2.2 billion today.
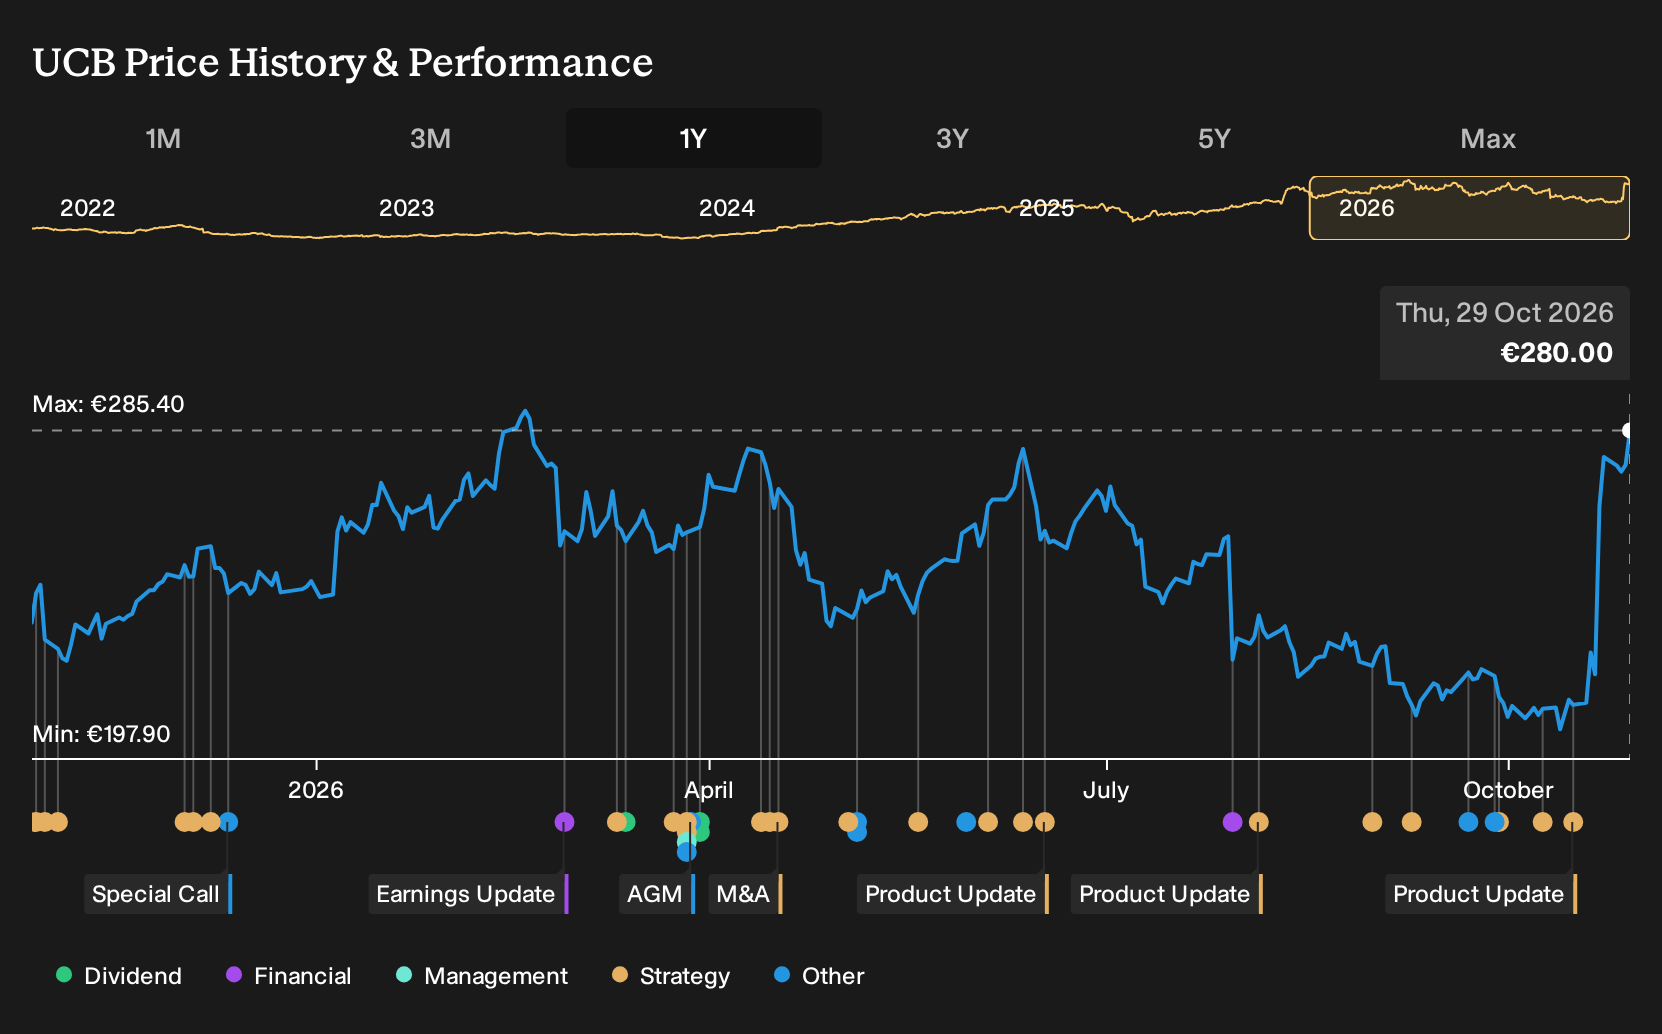
Uncover how UCB's fair value indicates a 3% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternative, more optimistic angle focuses on how devices like the ZILBRYSQ autoinjector could help UCB deepen rare disease engagement rather than just protect margins. The most bullish analysts were already modeling about €11.7b in 2029 revenue and €3.6b in earnings before this news, so you may see those views shift further as expectations adjust.
Explore 5 other UCB fair value estimates, including one that suggests potential upside of up to 108% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UCB research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UCB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UCB's overall financial health at a glance.
Looking for more investment ideas beyond UCB?
Once you have formed a view on UCB, it can help to compare that conviction against a wider set of companies that share some of the qualities you care about most, whether that is resilience, income, or the chance to back earlier stage stories with room to grow.
- If you want potential growth stories at earlier stages of their journey, scan a curated group of 129 elite penny stocks with strong financials that already show stronger financial profiles than many peers.
- For investors who care most about resilient balance sheets and cleaner fundamentals, filter for companies in our list of solid balance sheet and fundamentals (205 results) and see which ones match your risk tolerance.
- If the goal is to uncover opportunities the wider market may be overlooking, sort through a focused set of 606 high quality undiscovered gems that pair solid business quality with less analyst attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com