


Highwoods Properties came into this Q3 2026 report with investors weighing its income appeal against worries about office demand. The stock closed up 4.4% to US$30.50 after the numbers hit, a confident move for an office real estate investment trust that has divided opinion. The headline was clear. Funds From Operations, the key profit yardstick for REITs, landed at about US$100.1m while management nudged full year FFO guidance higher. The market cheered first. Now the question is how much of this strength is durable and how much is being paid for in the balance sheet.
Love the income story at Highwoods Properties but still uneasy about office demand and balance sheet risk? Check the list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
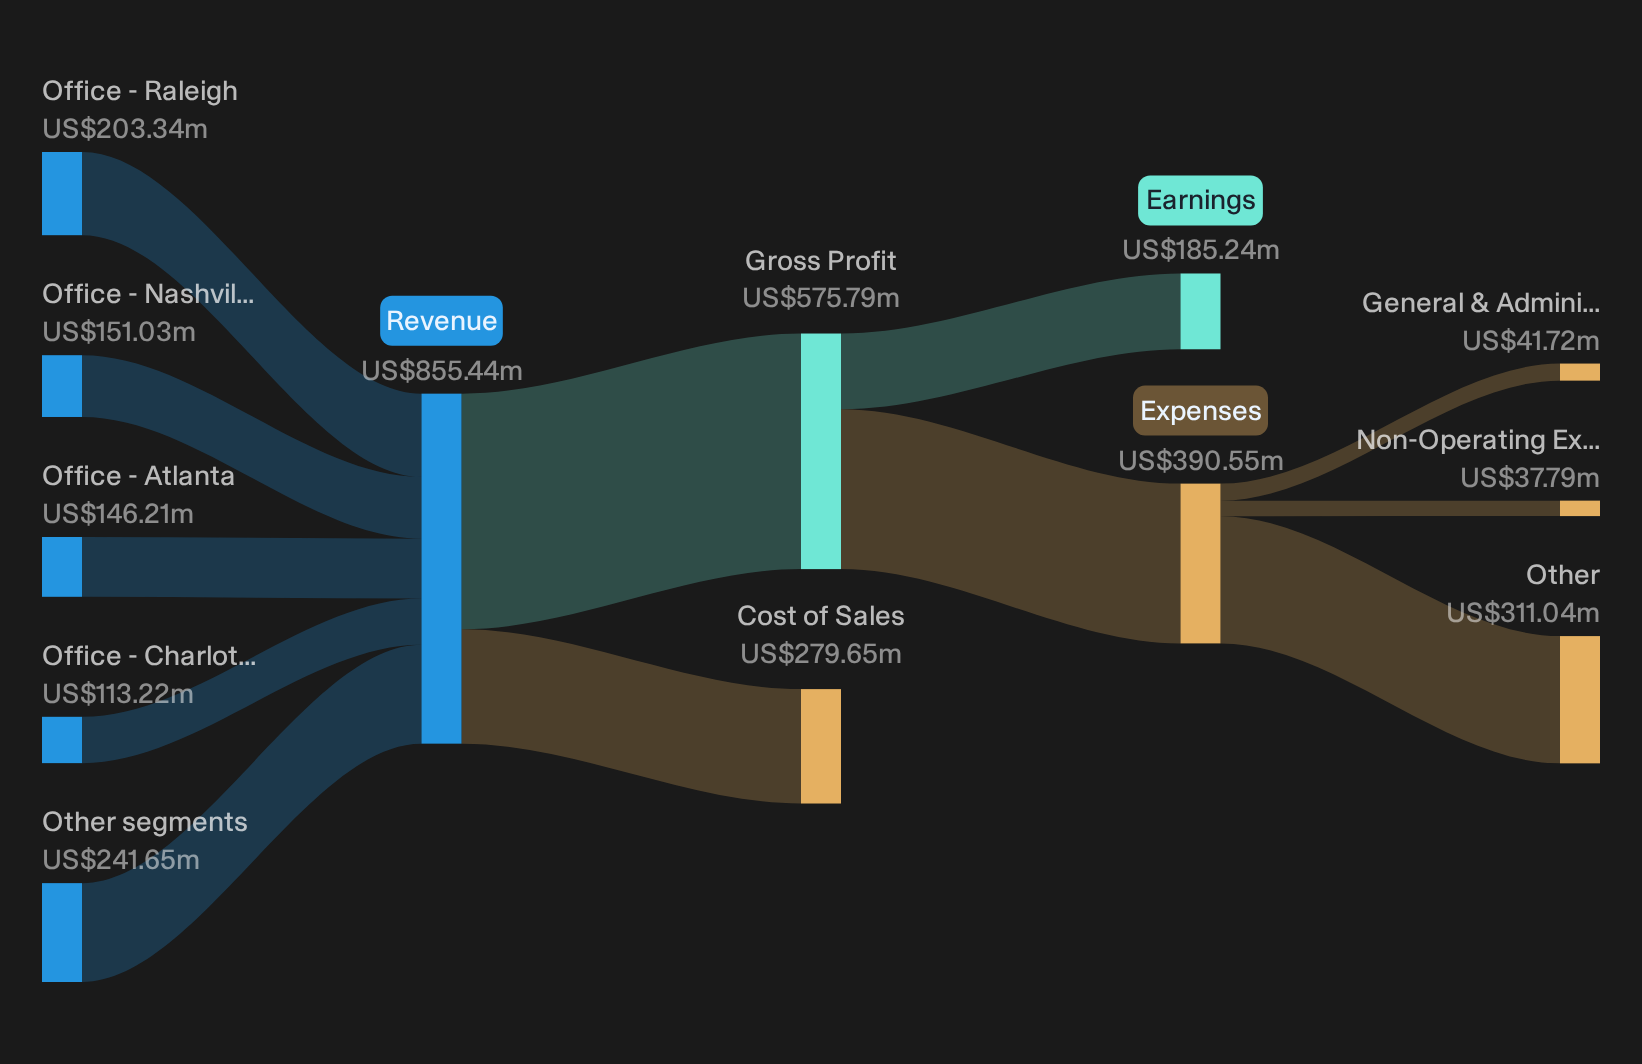
- Total Revenue (Q3 2026 vs Q3 2025): US$218.951m vs. US$202.371m (up about 8.2%)
- Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): US$31.75m vs. US$12.877m (up about 146.5%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.2878 vs. US$0.1188 (up about 142.2%)
- Funds From Operations (FFO, Q3 2026 vs Q3 2025): US$100.082m vs. US$94.799m (up about 5.6%)
Earnings only tell part of the story, especially for a REIT like Highwoods Properties, where recurring cash flows shape both income appeal and valuation discussions. If you focus on Highwoods Properties' cash generation rather than the earnings print, the stock could be a slight 11% undervalued.
Highwoods Bull Case Leans On Leasing And Recycling
The bullish story around Highwoods Properties leans heavily on execution in a tight Sunbelt office market. At its core is a claim that rent resets and portfolio upgrades can carry cash flows even when sentiment toward offices is cautious.
"Large embedded lease mark to market opportunities, including assets such as The Terraces in Dallas with more than 30% rent upside and several acquisitions with rents roughly 15% below market, which gives a visible path for revenue growth and potential expansion in NOI as leases roll."
Q3 leasing data lines up with that ambition. GAAP rent growth of 29% on second generation deals, higher net effective rents, a 130 bps occupancy lift and a 90.1% lease rate all point to that mark to market thesis actively playing out rather than sitting on paper.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Highwoods Bear Case: Asset Sales Still Drag On Growth
Bears argue Highwoods Properties is leaning too hard on selling buildings to fund its upgrade plan, with risk that deals slip or clear at weak prices.
"Although the rotation into newer, higher quality Sunbelt assets and out of older or noncore buildings is intended to improve growth, execution relies on selling roughly US$200 million of assets at acceptable pricing. Any slowdown in buyer demand would weigh on near term cash flow and FFO."
Q3 shows this concern is not fully resolved. Dispositions of US$386m already exceed the original target, yet another US$100m to US$250m still needs to close and timing is already described as slower. FFO guidance only edges higher, which suggests the heavy recycling program is not yet translating into visibly stronger growth.
Hunt Quiet Disconnects Before They Close
Highwoods Properties just showed how quickly sentiment can change when cash flow and guidance shift together. The real opportunity sits in hunting for stocks that could be undervalued before that gap narrows.
- Company 1 - 15% below our estimate - targets hyperscale data center buildouts as customers secure power, wiring and fit outs.
- Company 2 - 25% below our estimate - embeds AI centric networking gear and infrastructure into long term enterprise contracts for data center upgrades.
- Company 3 - 20% below our estimate - expands a teahouse network by selling franchise systems and supply chains to beverage operators.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com