


Parsons has built a reputation as a premium priced federal technology and infrastructure contractor, with a P/E of 35.3x that asks investors to pay up for quality. Q3 2026 results landed with record adjusted EBITDA and margins, yet the stock slipped 2.4% to close at US$49.33. That gap between a higher valuation and a soft one day reaction is the story. Earnings and cash generation looked healthy. The question now is whether the market is reassessing how much it is willing to pay for that profile.
Like the quality profile at Parsons but uneasy paying a 35.3x P/E for it after a muted price reaction? Compare that mix of premium valuation and earnings strength with stocks in our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
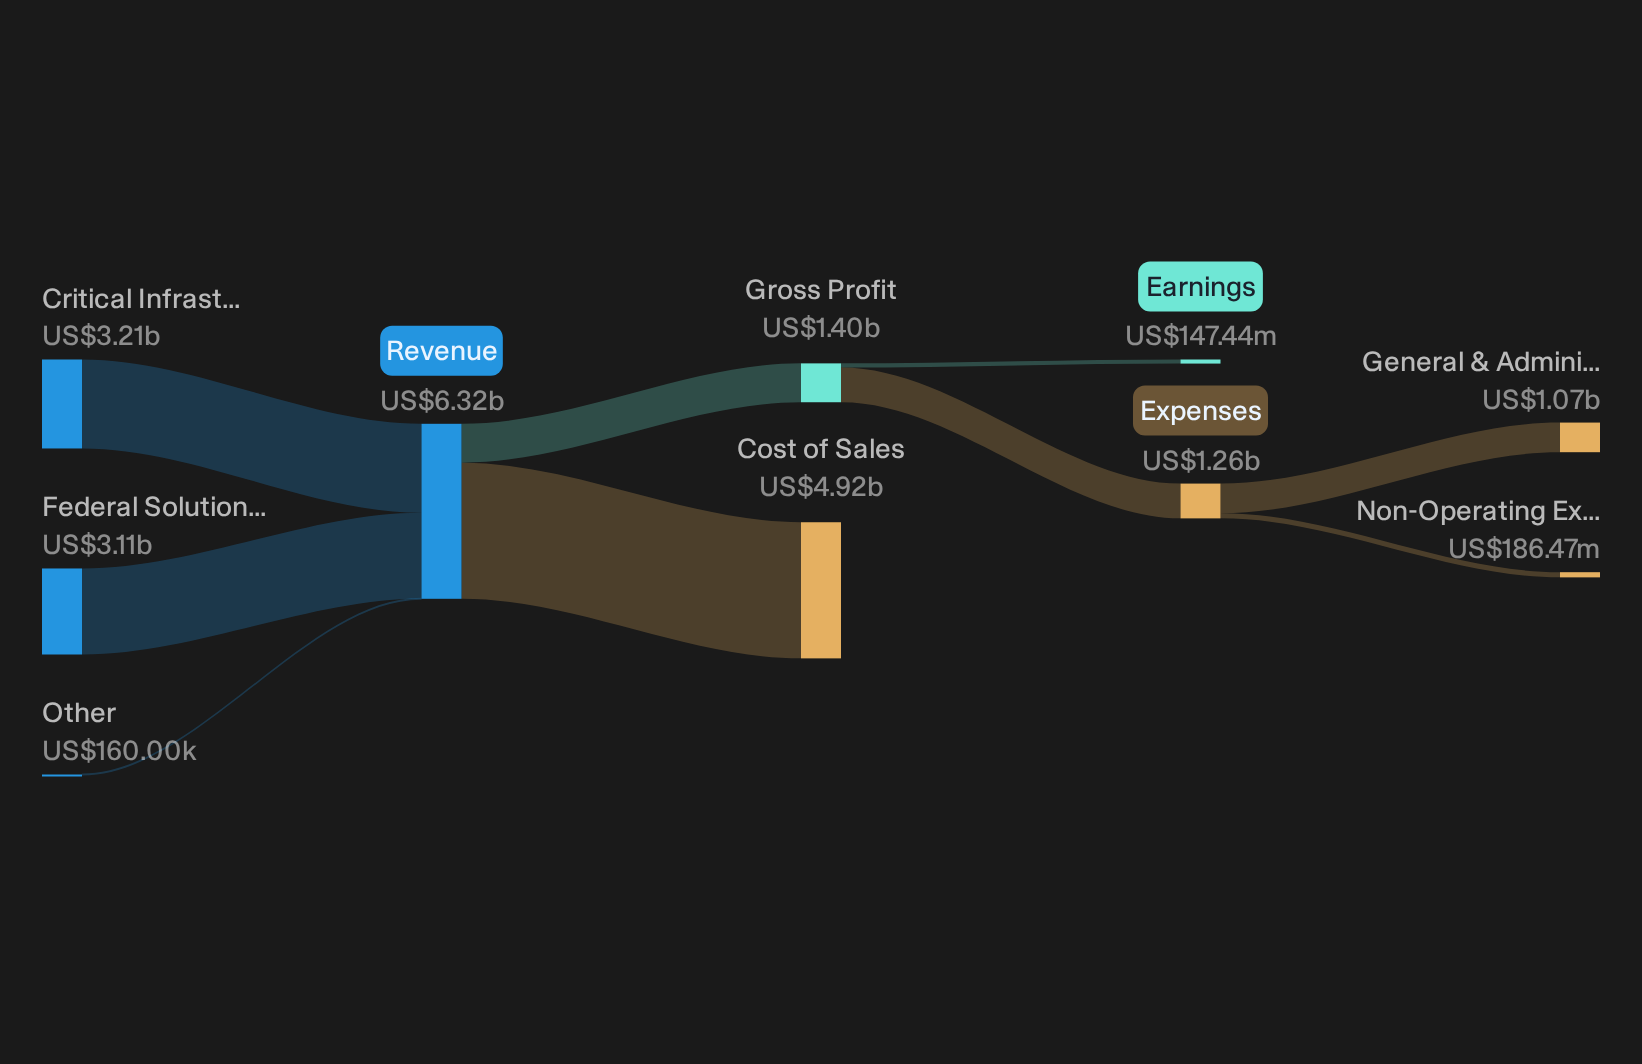
- Revenue (Q3 2026 vs. Q3 2025): US$1,650.5m vs. US$1,621.7m (up 1.8%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$54.2m vs. US$64.1m (down 15.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.51 vs. US$0.60 (down 15.0%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 10.2% vs. 9.8% (up 0.4 percentage points), with adjusted EBITDA at US$168m in Q3 2026
Tired of skimming through dense earnings summaries and still feeling unsure what really changed at Parsons this quarter? Get the full visual breakdown of Parsons' valuation picture in an easy chart-based view with the company report for Parsons.
Parsons’ Product Pivot Is Finally Showing Up In Margins
The bullish pitch around Parsons hinges on mix shift, not just more contracts.
"Scaling of Parsons’ AI enabled product portfolio, with roughly $350 million of expected 2026 product revenue and a plan for 20% to 30% growth in 2027 at margins above the corporate average, gives the company room to shift mix toward higher margin, more repeatable revenue and potentially lift earnings quality beyond what contract services alone imply."
Federal Solutions now carries roughly US$350m of product revenue and product margins are cited above 20%. Q3 adjusted EBITDA margin reached 10.2%, while Critical Infrastructure hit 11.1%. Federal Solutions margin was flat at about 9.2%. Even so, record corporate margins and 130% free cash flow conversion indicate that the product pivot is already helping earnings quality, even if segment uplift is gradual.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Parsons Bear Case: Cash Strain Eases, Backlog Fragility Lingers
Bearish investors worry Parsons’ product push could starve cash generation just as legacy projects still bite into earnings.
"Despite management pointing to a mix shift toward higher margin, product oriented offerings in Federal Solutions, the decision to build roughly US$30 million of strategic inventory and the associated cut to 2026 operating cash flow guidance indicate that scaling this portfolio could tie up more working capital than expected."
Q3 tells a more mixed story. Operating cash flow reached US$269m with 130% free cash flow conversion over twelve months, so the feared cash squeeze is not evident. The bigger miss to the bearish script sits in execution risk. The remote contracts divestiture removes one loss making pocket, yet the Canadian JV still carries schedule and weather risk and no further charge is assumed in guidance. Backlog conversion anxiety has not vanished either. Revenue grew modestly, and book to bill stayed near 1.1x, but Federal margins held flat at about 9.2% despite product revenue around US$350m. Parsons is showing progress on cash and portfolio clean up, although the core concern about how efficiently awards turn into higher margin, recurring revenue remains only partially answered.
Hunt For Mispriced Earnings Power
Parsons recently illustrated how a rich P/E ratio can coincide with a muted share price response. The focus now is on stocks that may be undervalued relative to their underlying earnings power.
- Company 1 - 50% below our estimate - build an aviation aftermarket platform that integrates acquired businesses into higher margin engine and component programs.
- Company 2 - 31% below our estimate - leverage optical and solar supply agreements that link customer prepayments to future digital and energy infrastructure projects.
- Company 3 - 26% below our estimate - expand a low cost digital banking platform where rising customer numbers and revenue per account support an improving efficiency ratio.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com