


Waste Management stock went into this Q3 2026 report with a mixed tape, down over the past week but ahead roughly 11% across the last month. The print landed with a jolt. Shares closed up 2.6% today as investors reacted to a steady grind higher in earnings per share and a business that continues to convert trash collection into cash flow.
The real story is profit quality. Q3 basic EPS of about US$2.06 and net income of US$820 million fit a year where trailing earnings and margins have been firming, even as the valuation and debt load keep expectations high.
Love Waste Management’s steady earnings grind but wary of paying up for a business with a rich valuation and meaningful leverage on the balance sheet? Compare it with peers that are screened for stronger fundamentals and pricing power in our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$6,846 million vs. US$6,443 million (up about 6.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$820 million vs. US$603 million (up about 36.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.06 vs. US$1.50 (up about 37.4%)
- Operating EBITDA Margin (Q3 2026): approximately 31% in the quarter, with underlying margin expansion supported by pricing and cost control
Free cash flow is up 42% even as diesel bites. Ask Charlie what drove Waste Management’s surge in free cash flow.
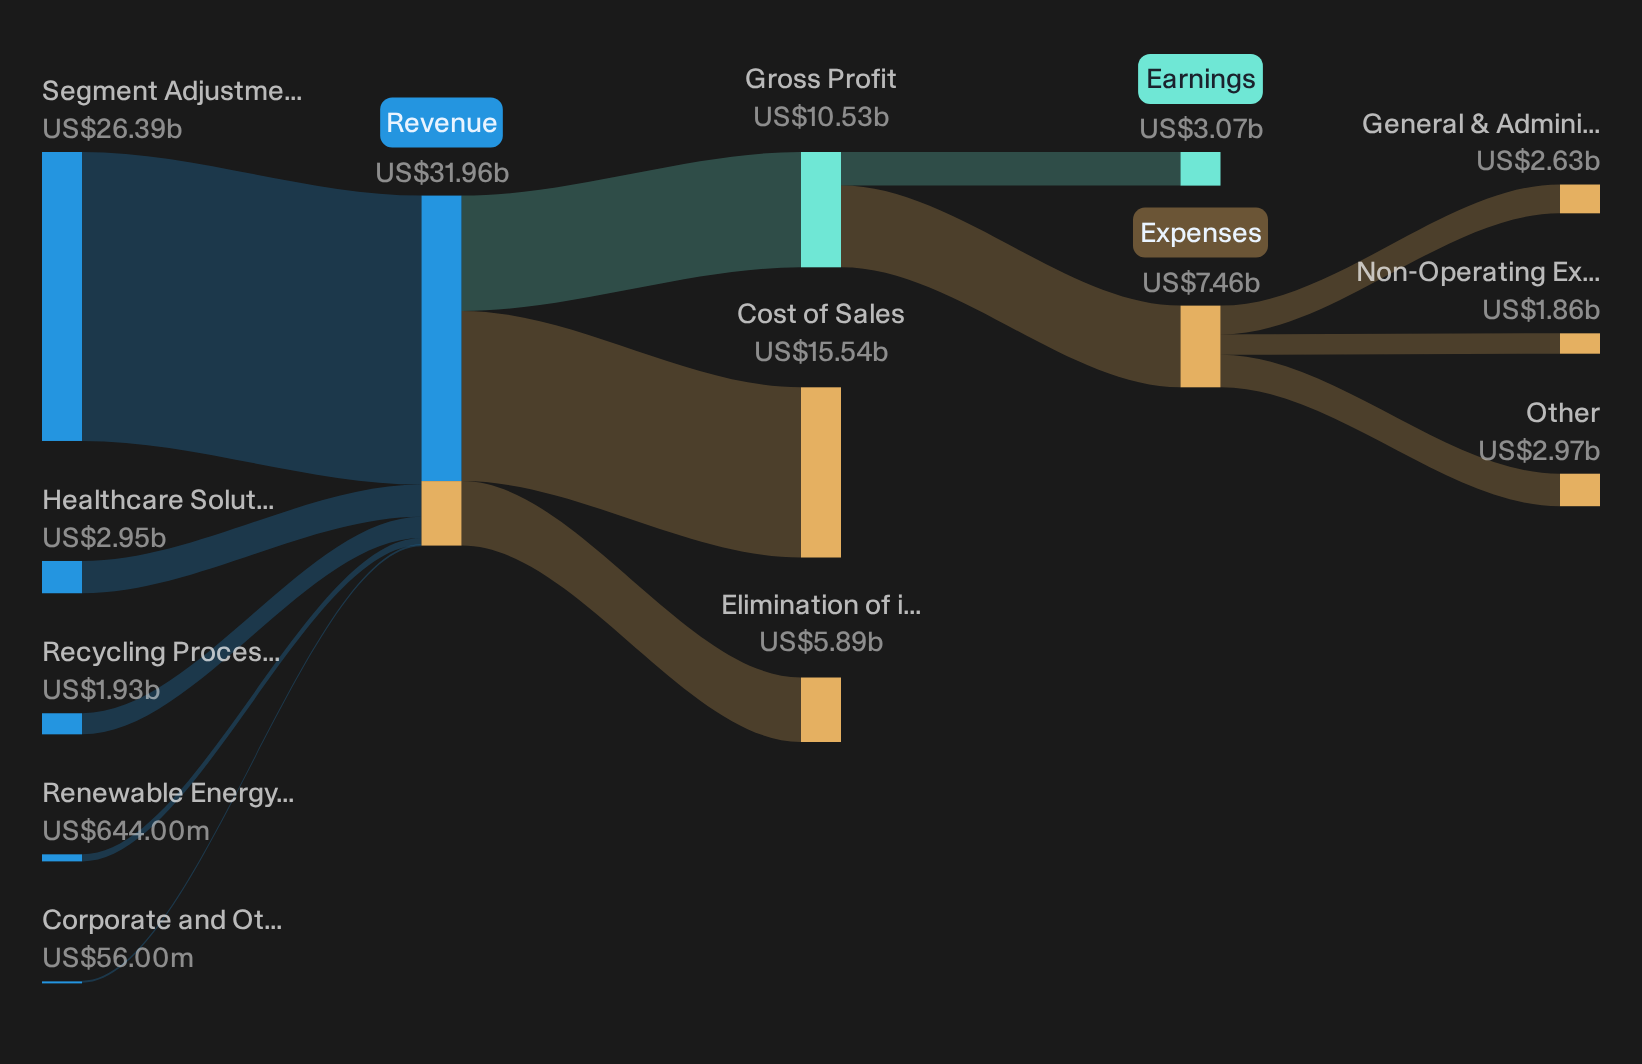
Waste Management automation thesis meets key margin tests
Supporters argued that Waste Management’s tech and recycling capex would harden profitability. The latest Q3 numbers go some way to proving that out.
"The implementation of technology to supplement the workforce and optimize cost structures remains a key differentiator for Waste Management, with onboard computing, SmartTruck and AI tools helping keep operating expenses under 60% of revenue for six consecutive quarters and supporting higher net margins."
Operating EBITDA margin of about 31% and SG&A at 9.3% of revenue align with that claim. Pricing held firm, and Healthcare Solutions EBITDA rose 33%, with recycling EBITDA up 40%, which suggests automation and digital tools are now flowing through to segment level profitability and free cash flow above 50% of EBITDA.
RNG and healthcare risks still on the radar
The bear story has focused on whether high spend in healthcare and renewable natural gas really turns into cash generation without new headaches.
"The acquisition of Stericycle initially lifted leverage above the target range. Although leverage is now back to about 2.96x and share repurchases have resumed, any shortfall in the planned US$300m synergy program or slower progress toward the targeted SG&A ratio in Healthcare Solutions could limit the earnings contribution expected from this deal and reduce future flexibility in capital allocation."
Leverage of 2.92x sits inside the stated band and buybacks plus dividends together reached US$2.72b over nine months. Healthcare SG&A already improved to 15.2% of revenue and EBITDA in that unit climbed 33%. That tilts this quarter toward execution progress, although the full US$300m synergy target remains untested.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Cash Engines
Waste Management just showed how steady execution and a strong capital return program can still move a mature stock. The real opportunity is spotting companies that could be undervalued before the market adjusts.
- Company 1 - 43% below our estimate - grows cross border payment volumes for large online platforms while pushing transactions toward higher margin products and automation.
- Company 2 - 16% below our estimate - expands manufacturing capacity to capture demand for AI driven data center optics and higher value photonics programs.
- Company 3 - 32% below our estimate - builds massive AI focused cloud infrastructure as new supercluster contracts reshape its role in large scale computing projects.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com